Crossroads Insurance & Investments
  • HOME
  • SERVICES
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING FOR YOUNG FAMILIES
      • ESTATE PLANNING FOR RETIREES & MATURE FAMILIES
      • CHARITABLE GIVING
      • MANULIFE ONE
    • NEW IMMIGRANTS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
      • SUCCESSION PLANNING
      • GROUP BENEFITS
        • HEALTH BENEFITS
        • RETIREMENT BENEFITS
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
    • INSURANCE
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • MORTGAGE LIFE INSURANCE
      • LONG TERM CARE
      • CROSS BORDER INSURANCE
    • INVESTMENT
      • REGISTERED EDUCATION SAVINGS PLAN
      • TAX FREE SAVINGS ACCOUNT
      • REGISTERED RETIREMENT SAVINGS PLAN
      • REGISTERED RETIREMENT INCOME FUND
      • ANNUITIES
  • ABOUT
    • ABOUT
    • PROCESS
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
    • CALCULATORS
  • CONTACT
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

    Tag Archive for: retirement

    Posts

    Retirement Planning

    August 1, 2023/in Blog, Family, health benefits, life insurance, Retirees, retirement, rrsp/by Crossroads Financial Inc.

    brandableContent

    Most of us understand the benefits of sensible retirement planning. Still, it doesn’t feel relatively straightforward when it comes to creating your retirement strategy and putting it into effect. The reality is that, while there are lots of variables to consider, it isn’t as challenging to create an effective plan for retirement as you may think.

    Firstly, let’s consider the merits of a retirement plan. Firstly, the plan will aid you in setting clear goals for your retirement, such as the age that you want to finish work and what you want your retirement to look like in terms of lifestyle. Secondly, it will help you establish how much you need to save to have a retirement that meets your objectives. Thirdly, a plan will allow you to choose your investment options wisely.

    How you know how much you need to save is a common question. This depends on three factors:

    • Your age. It makes sense that starting to save for retirement when you are younger means that you need to save less money than starting later in life.

    • Benefits available to you. There is a range of federal government benefits that you might be eligible for, such as the Canada Pension Plan or Old Age Security.

    • Your plans for your retirement will inevitably affect how much you need to save to fund it.

    If you haven’t started saving for your retirement yet or have less in your retirement savings plan than you would like, take a look at our top tips to accelerate your savings.

    • Make the most of RRSPs and TFSAs to minimize your tax bill and make your money grow faster.

    • Take advantage of any pensions or savings plans that your workplace offers, as your employer’s contributions can add extra value to your fund.

    • Look at your spending habits to identify opportunities to cut back outgoings and save more.

    • Think about putting spare money into your retirement fund.

    Taking steps to create an effective retirement plan is a decision that will pay off as you approach later life, allowing you to have the savings for the retirement that you deserve.

    Talk to us; we can help.

    https://crossroadsfinancial.ca/wp-content/uploads/2023/08/Retirement-planning.png 281 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2023-08-01 06:00:002023-08-01 06:23:55Retirement Planning

    Retirement Planning for Business Owners – Checklist

    October 1, 2021/in Blog, Business Owners, corporate, health benefits, life insurance, long term care, pension plan, rrsp, Tax Free Savings Account/by Crossroads Financial Inc.

    As a business owner, one of your challenges is learning how to balance between reinvesting into the business and setting money aside for personal savings. Since there are no longer employer-sponsored pension plans and the knowledge that retirement will come eventually, it’s important to have a retirement plan in place.

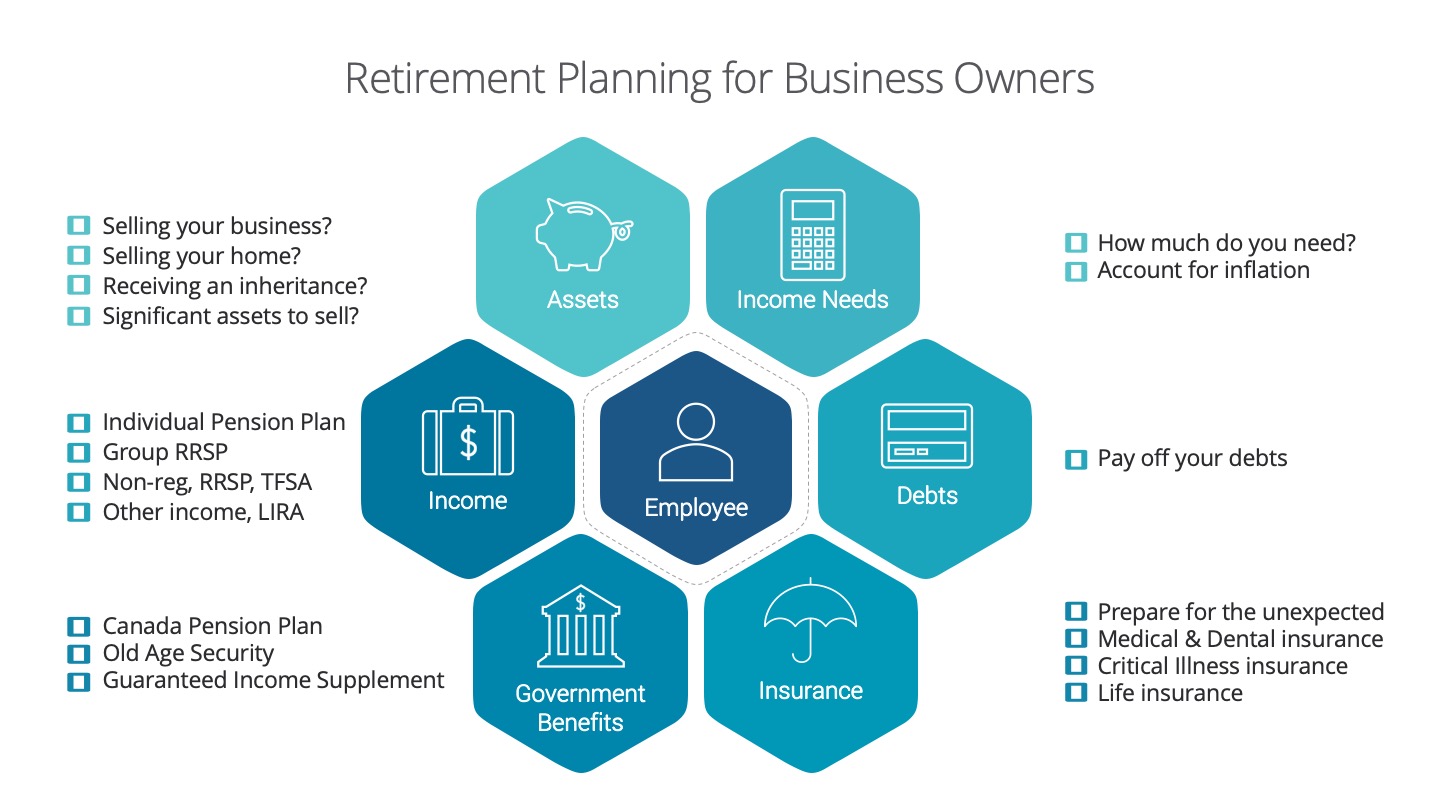
    We’ve put together an infographic checklist that can help you get started on this. We know this can be a difficult conversation so we’re here to help and provide guidance to help you achieve your retirement dreams.

    Income Needs

    • Determine how much income you will need in retirement.

    • Make sure you account for inflation in your calculations.

    Debts

    • You should try to pay off your debts as soon as you can; preferably before you retire.

    Insurance

    • As you age, your insurance needs change. Review your insurance needs, in particular your medical and dental insurance because a lot of plans do not provide health plans to retirees.

    • Review your life insurance coverage because you may not necessarily need as much life insurance as when you had dependents and a mortgage, but you may still need to review your estate and final expense needs.

    • Prepare for the unexpected such as a critical illness or a need for long-term care.

    Government Benefits

    • Check what benefits are available for you upon retirement.

    • Canada Pension Plan- decide when would be the ideal time to apply and receive CPP payments. Business owners are in a unique position to control how much can be contributed to CPP by deciding to pay salary or dividends. (Dividends don’t trigger CPP contributions.)

    • Old Age Security- check pension amounts and see if there’s a possibility of clawback.

    • Guaranteed Income Supplement- if your income is low enough, you could apply for GIS.

    Income

    • Are you a candidate for an individual pension plan (IPP)? IPPs can provide higher contributions than typically permitted to an RRSP and the ability to create a lifelong pension.

    • Check if your business is a candidate for a group RRSP or company pension plan. This is a great way for you to build retirement savings and provide benefits for your employees and business too.

    • Make sure you are saving on a regular basis towards retirement- in an RRSP, TFSA, or non-registered. Since you can control how you get paid, salary or dividends, dividends are not considered eligible income to create RRSP room, therefore you should make sure you have the optimal mix of both to achieve your financial goals.

    • Ensure your investment mix makes sense for your situation.

    • Don’t forget to check if there are any other income sources.  (ex. rental income, side hustle income, etc.)

    Assets

    • The sale of your business can be part of your retirement nest egg. Therefore, you should make sure you know the valuation of your business and your plan to sell the business to your family, employees, partners or a third party. You should also know when you decide to sell your business too.

    • Are you planning to use the sale of your home or other assets to fund your retirement?

    • Will you be receiving an inheritance?

    One other consideration that’s not included in the checklist is divorce. This can be an uncomfortable question, however divorce amongst adults ages 50 and over is on the rise and this can be financially devastating for both parties.

    Next steps…

    • Contact Us about helping you get your retirement planning in order so your retirement dreams can be achieved.

    https://crossroadsfinancial.ca/wp-content/uploads/2021/10/retirementPlanningBO.jpeg 810 1440 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2021-10-01 06:00:002021-10-01 06:06:07Retirement Planning for Business Owners – Checklist

    Do you REALLY need life insurance?

    August 1, 2021/in Blog, Business Owners, Family, individuals, life insurance/by Crossroads Financial Inc.

    You most likely do, but the more important question is, What kind? Whether you’re a young professional starting out, a devoted parent or a successful CEO, securing a life insurance policy is probably one of the most important decisions you will have to make in your adult life. Most people would agree that having financial safety nets in place is a good way to make sure that your loved ones will be taken care of when you pass away. Insurance can also help support your financial obligations and even take care of your estate liabilities. The tricky part, however, is figuring out what kind of life insurance best suits your goals and needs. This quick guide will help you decide what life insurance policy is best for you, depending on who needs to benefit from it and how long you’ll need it. 

    Permanent or Term? 

    Life insurance can be classified into two principal types: permanent or term. Both have different strengths and weaknesses, depending on what you aim to achieve with your life insurance policy. 

    Term life insurance provides death benefits for a limited amount of time, usually for a fixed number of years. Let’s say you get a 30-year term. This means you’ll only pay for each year of those 30 years. If you die before the 30-year period, then your beneficiaries shall receive the death benefits they are entitled to. After the period, the insurance shall expire. You will no longer need to pay premiums, and your beneficiaries will no longer be entitled to any benefits.

    Term life insurance is right for you if you are: 

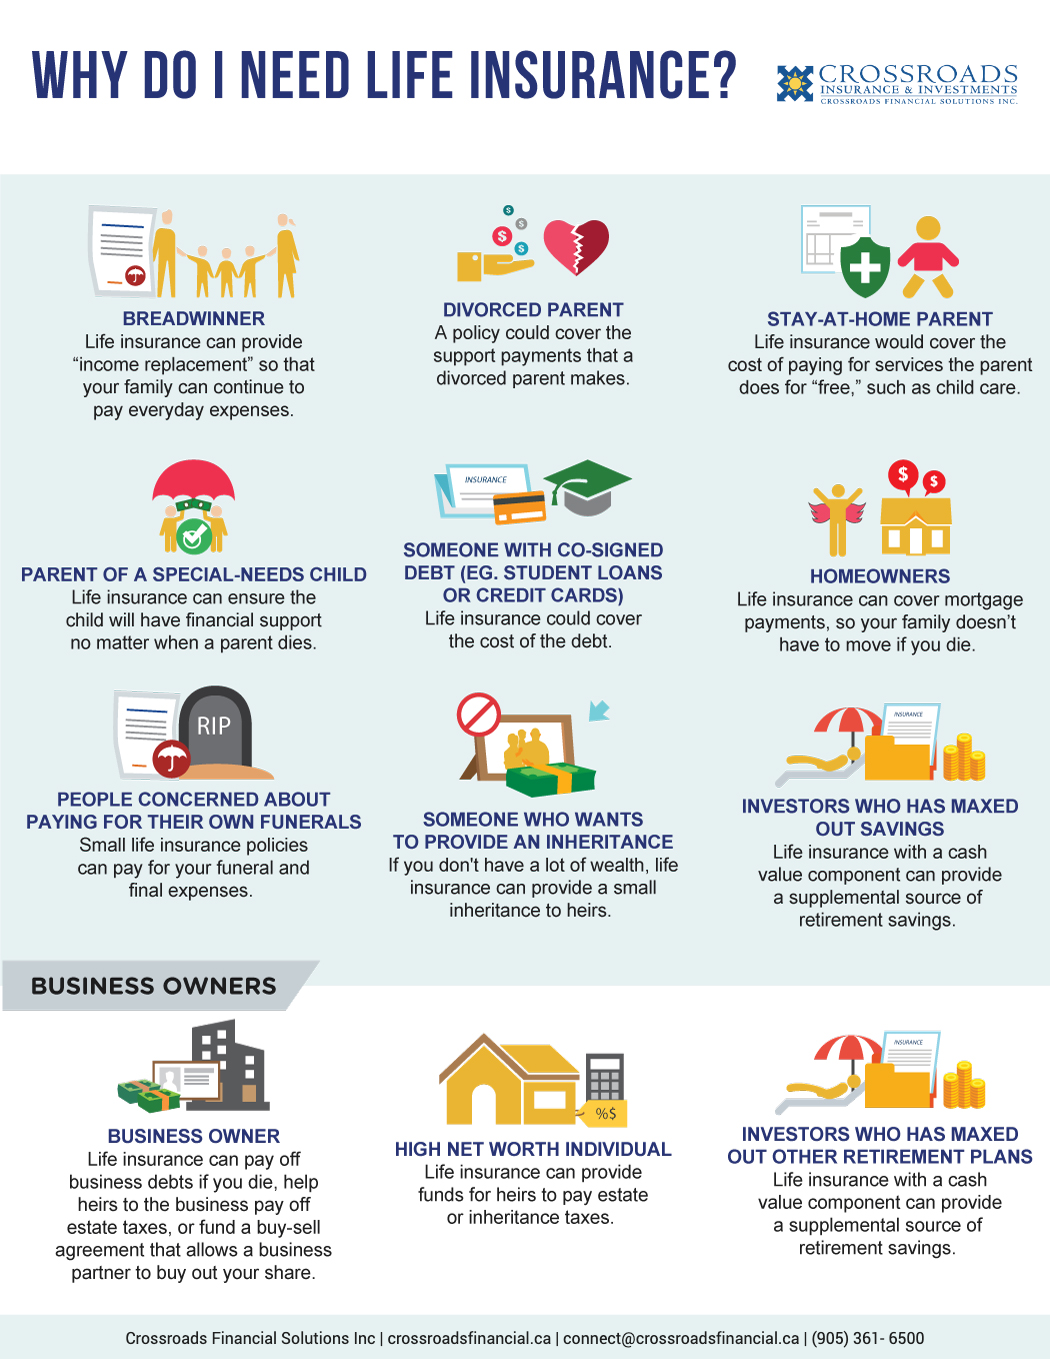
    • The family breadwinner. Death benefits will replace your income for the years that you will have been working, in order to support your family’s needs.

    • A stay-at-home parent. You can set your insurance policy term to cover the years that your child will need financial support, especially for things that you would normally provide as a stay-at-home parent, such as childcare services.

    • A divorced parent. Insurance can cover the cost of child support, and the term can be set depending on how long you need to make support payments.

    • A mortgagor. If you are a homeowner with a mortgage, you can set up your term insurance to cover the years that you have to make payments. This way, your family won’t have to worry about losing their home.

    • A debtor with a co-signed debt. If you have credit card debt or student loans, a term life insurance policy can cover your debt payments. The term can be set to run for the duration of the payments. 

    • A business owner. If you’re a business owner, you may need either a term or permanent life insurance, depending on your needs. If you’re primarily concerned with paying off business debts, then a term life insurance may be your best option. 

    Unlike term life insurance, a permanent life insurance does not expire. This means that your beneficiaries can receive death benefits no matter when you die. Aside from death benefits, a permanent life insurance policy can also double as a savings plan. A certain portion of your premiums can build cash value, which you may “withdraw” or borrow for future needs. You can do well with a permanent life insurance policy if you: 

    • …Have a special needs child. As a special needs child will most likely need support for health care and other expenses even as they enter adulthood. Your permanent life insurance can provide them with death benefits any time within their lifetime.

    • …Want to leave something for your loved ones. Regardless of your net worth, permanent life insurance will make sure that your beneficiaries receive what they are entitled to. If you have a high net worth, permanent life insurance can take care of estate taxes. Otherwise, they will still get even a small inheritance through death benefits.

    • …Want to make sure that your funeral expenses are covered. Final expense insurance can provide coverage for funeral expenses for smaller premiums.

    • …Have maximized your retirement plans. As permanent life insurance may also come with a savings component, this can also be used to help you out during retirement.

    • …Own a business. As mentioned earlier, business owners may need either permanent or term, depending on their needs.

    A permanent insurance policy can help pay off estate taxes, so that the successors can inherit the business worry-free. Different people have different financial needs, so there is no one-sized-fits-all approach to choosing the right insurance policy for you. Talk to us now, and find out how a permanent or term life insurance can best give you security and peace of mind. 
    https://crossroadsfinancial.ca/wp-content/uploads/2021/08/do-you-really-need-life-insurance-coverImage.png 500 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2021-08-01 06:30:002021-08-01 06:36:09Do you REALLY need life insurance?

    Book a Meeting

    Search Blog Posts

    Search Search

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    Categories

    • 2020
    • 2020 Only
    • 2021
    • 2022
    • 2022 Only
    • 2023
    • 2024
    • 2025
    • 2026
    • Accountants
    • Blog
    • Budget
    • Business Owners
    • business owners
    • buy sell
    • Center of Influences
    • Charitable Gifting
    • Coronavirus
    • Coronavirus – Associates
    • Coronavirus – Practice Owners
    • Coronavirus – Practice Owners
    • Coronavirus – Retired
    • Coronavirus – Retiring
    • Coronavirus – Students
    • corporate
    • critical illness insurance
    • Debt
    • dental benefits
    • disability
    • disability insurance
    • Estate Planning
    • Family
    • farmers
    • financial advice
    • Financial Planning
    • Government Budget
    • Group Benefits
    • health benefits
    • incorporated professionals
    • individuals
    • Insurance
    • Investment
    • life insurance
    • long term care
    • mortgage
    • Ontario Only
    • pension plan
    • personal finances
    • Professional Corporations
    • Professionals
    • rdsp
    • Registered Education Savings Plan
    • Retirees
    • retirement
    • rrsp
    • tax
    • Tax Free Savings Account
    • travel insurance

    Get in Touch

    Crossroads Financial Solutions Inc.
    Tel: (905) 361- 6500
    Email: connect@crossroadsfinancial.ca
    TF: 1-877-607-6237

    4255 Sherwoodtowne Blvd, Suite 102
    Mississauga, Ontario
    L4Z 1Y5

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    About

    Everyone has their own dreams. Protecting those goals is our mission. We believe there is no “One Size Fits All” when it come to planning your insurance needs and investment goals.
    We encourage you to have a discovery meeting with us.

    ©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
      Scroll to top Scroll to top Scroll to top