Crossroads Insurance & Investments
  • HOME
  • SERVICES
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING FOR YOUNG FAMILIES
      • ESTATE PLANNING FOR RETIREES & MATURE FAMILIES
      • CHARITABLE GIVING
      • MANULIFE ONE
    • NEW IMMIGRANTS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
      • SUCCESSION PLANNING
      • GROUP BENEFITS
        • HEALTH BENEFITS
        • RETIREMENT BENEFITS
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
    • INSURANCE
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • MORTGAGE LIFE INSURANCE
      • LONG TERM CARE
      • CROSS BORDER INSURANCE
    • INVESTMENT
      • REGISTERED EDUCATION SAVINGS PLAN
      • TAX FREE SAVINGS ACCOUNT
      • REGISTERED RETIREMENT SAVINGS PLAN
      • REGISTERED RETIREMENT INCOME FUND
      • ANNUITIES
  • ABOUT
    • ABOUT
    • PROCESS
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
    • CALCULATORS
  • CONTACT
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

    Archive for category: life insurance

    Why Life Insurance Should Be Part Of Your Estate Planning

    September 1, 2026/in Blog, Estate Planning, life insurance/by Crossroads Financial Inc.

    Why Life Insurance Should Be Part Of Your Estate Planning

    You’ve worked hard and managed your money carefully throughout your life. So rest easy knowing that you will have more than enough assets to fulfill your needs during your retirement years.

    You also need to think beyond your retirement years and consider what will happen to your assets after your death. For example, it is essential to consider whether your assets could result in tax liabilities for your heirs.

    Generally, there are three types of assets during estate planning:

    1. Capital assets – shares in public or private companies, or real estate such as a second home or cottage.

    2. Income-producing assets – assets that produce income, such as RRSPs and RRIFs.

    3. Non-taxable assets – such as cash, TFSAs, your principal residence, and the proceeds from a life insurance policy.

    How can life insurance help my heirs cover their tax liabilities?

    There’s an old saying that there are only two things certain in life – death and taxes. So naturally, you do not want your loved ones to be burdened with tax liabilities when they inherit capital or income-producing assets from your estate. In most situations, the estate may not have enough cash to leave to your heirs to cover those tax liabilities.

    Providing the means to cover tax liabilities upon your death is where life insurance can be such a valuable part of estate planning. With life insurance, you can both guarantee your heirs have the funds when they need them, as well as receive the death benefit tax-free. In addition, your heirs won’t have the stress of how they’ll come up with the money to pay taxes on any assets they inherit.

    Are there any other reasons I should include life insurance as part of my estate planning?

    Since life insurance death benefit is tax-free, it is an excellent source of liquidity to include in your estate planning. Your heirs can use the funds for a variety of purposes, including:

    • Paying off debts

    • Covering funeral expenses

    • As a source of income – If your family has suddenly gone from two income-earners to one, this can significantly affect their standard of living.

    • Provide funding for a considerable expense, such as college or university tuition.

    We can help with estate planning

    If you’d like to include life insurance as part of your estate planning but aren’t sure where to start – we can help you with that! We’ll talk to you about different types and amounts of life insurance coverage to see what works for you – call us or email us today!

    https://crossroadsfinancial.ca/wp-content/uploads/2026/09/Why-Life-Insurance-should-be.png 281 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-09-01 13:30:452026-09-01 13:30:52Why Life Insurance Should Be Part Of Your Estate Planning

    What Is Life Insurance and How Does It Work?

    May 1, 2026/in Blog, Estate Planning, Family, life insurance/by Crossroads Financial Inc.

    What Is Life Insurance and How Does It Work?

    Have you ever wondered what would happen to your family’s finances if you were no longer here? It’s not an easy thought. But it is an important one. Life insurance is designed to protect the people you care about most if something unexpected happens.

    Many people avoid this topic because it feels uncomfortable or confusing. The good news is that life insurance is actually quite simple once you break it down.

    What Is Life Insurance?

    Life insurance is a contract between you and an insurance company. You pay a regular payment called a premium. In return, the insurance company agrees to pay a lump sum of money to someone you choose (your beneficiary) if you pass away.

    That lump sum is called a death benefit. In most cases, it is paid tax-free to your beneficiary.

    Think of life insurance like a safety net. You hope it is never needed. But if it is, it can help your family stay financially stable during a very difficult time.

    Millions of Canadians have some form of life insurance coverage. For many families, it plays an important role in protecting income and covering large expenses.

    How Does Life Insurance Work?

    The process is straightforward.

    First, you apply for coverage. The insurance company reviews details such as your age, health, lifestyle, and sometimes your occupation. This helps them decide your premium and whether you qualify.

    Once approved, you begin paying premiums. As long as you keep paying, your coverage remains active.

    If you pass away while the policy is active, your beneficiary files a claim. The insurance company reviews the claim and then pays out the death benefit.

    Your beneficiary can use the money for any purpose, such as:

    • Paying off a mortgage

    • Covering funeral expenses

    • Replacing lost income

    • Paying off debt

    • Supporting children’s education

    The goal is to reduce financial stress at a time when your family is already dealing with emotional loss.

    The Two Main Types of Life Insurance

    Most people choose between two main types of coverage: term life insurance and permanent life insurance.

    Term Life Insurance

    Term life insurance covers you for a set period of time, such as 10, 20, or 30 years.

    It is usually the most affordable option, especially for young families. If you pass away during the term, the policy pays out. If the term ends and you are still living, the coverage ends unless you renew it.

    Term insurance works well for temporary needs. For example:

    • Protecting your income while your children are young

    • Covering a mortgage while the balance is high

    • Replacing income during your working years

    It is simple and focused on protection.

    Permanent Life Insurance

    Permanent life insurance covers you for your entire lifetime, as long as premiums are paid.

    It also includes a savings feature called cash value. Over time, this value can grow on a tax-deferred basis.

    Permanent coverage is usually more expensive than term coverage. However, it can support longer-term goals such as:

    • Covering final expenses

    • Leaving money to family or a charity

    • Helping manage taxes at death

    • Supporting estate planning goals

    The right type of coverage depends on your needs, timeline, and budget.

    How Much Coverage Do You Need?

    This is one of the most common questions people ask.

    A good starting point is to ask: If I were gone tomorrow, what financial gap would my family face?

    You may want to consider:

    • Your mortgage balance

    • Other debts

    • Ongoing living expenses

    • Childcare costs

    • Future education expenses

    • Final expenses

    Some people use a simple guideline like 10 times their annual income. But that is only a starting point. Your personal situation matters more than any rule of thumb.

    For example, someone with no dependents and little debt may need very little coverage. A household with young children and a large mortgage may need much more.

    The goal is to match coverage with real responsibilities.

    Is Life Insurance Expensive?

    Many people assume life insurance costs more than it does. In reality, term coverage can be very affordable, especially if you are young and in good health.

    Your premium is based on factors such as:

    • Age

    • Health history

    • Smoking status

    • Coverage amount

    • Type of policy

    The younger and healthier you are when you apply, the lower your premium is likely to be.

    Waiting can increase the cost. Health can change over time. Securing coverage earlier can help lock in lower rates.

    Who Should Consider Life Insurance?

    Life insurance is not necessary for everyone. But it is important for many people.

    You may want to consider coverage if:

    • Someone depends on your income

    • You share debts with a partner

    • You have children

    • You own a home

    • You want to leave money behind for loved ones

    Even stay-at-home parents may need coverage. If they were not there, the cost of childcare and household support could be significant.

    In Canada, life insurance benefits are generally paid tax-free to beneficiaries. This helps ensure that the full amount can be used for its intended purpose.

    Final Thoughts

    Life insurance is a practical tool. It helps protect the people you care about from financial hardship if something unexpected happens. It can provide stability, cover major expenses, and support your family’s future.

    If you are unsure whether you need coverage, start by reviewing who depends on you and what financial responsibilities you carry. A short conversation can bring clarity and peace of mind.

    If you would like to explore how life insurance fits into your overall strategy, I would be happy to guide you through the options and help you make an informed decision.
    This is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

    https://crossroadsfinancial.ca/wp-content/uploads/2026/05/What-Is-Life-Insurance-and-How-Does-It-Work.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-05-01 11:13:542026-05-01 11:14:10What Is Life Insurance and How Does It Work?

    Personal Life Insurance Planning

    June 2, 2025/in Blog, life insurance/by Crossroads Financial Inc.

    Personal Life Insurance Planning

    When thinking about life insurance, one of the most important steps is figuring out how much coverage you need. Everyone’s situation is unique, but a helpful starting point is understanding your coverage options and thinking about the areas of your life that need protection.

    Understanding the Different Types of Life Insurance

    There are four main types of life insurance: Term, Term to 100, Universal Life, and Whole Life. Here’s how they compare:

    Term Life Insurance

    Term life insurance provides coverage for a specific number of years—typically 10, 20, or 30 years. It offers fixed premiums for the length of the term, and if renewed, premiums will increase based on your age. This type of insurance provides a fixed death benefit during the coverage period and does not build any cash value.

    Ideal For: Families with children, people with mortgages or temporary debts

    Death Benefit – Common Uses: Income replacement, mortgage protection, child education

    Term to 100

    Term to 100 offers lifetime coverage with level premiums that are payable until age 100. It is a cost-effective way to get permanent insurance, as it does not accumulate cash value. The policy provides a death benefit as long as premiums are paid.

    Ideal For: Those wanting lifetime coverage without investment features

    Death Benefit – Common Uses: Final expenses, estate taxes, leaving a small legacy

    Universal Life Insurance

    Universal life insurance is a flexible form of permanent insurance that includes both a death benefit and a tax-advantaged investment component. You can adjust your premium payments and death benefit within certain limits. The policy’s cash value depends on how much you contribute and the performance of the chosen investments. Funds can be used for investment growth, savings, personal use, and retirement planning.

    Ideal For: People who want long-term coverage with savings but require flexibility

    Death Benefit Uses: Advanced estate planning, long-term wealth transfer

    Cash Value Uses: Emergency funding, retirement planning, education funding, large purchases

    Whole Life Insurance

    Whole life insurance provides permanent coverage with level premiums and a death benefit. It also builds cash value over time, which you can borrow against, withdraw from, or use to help pay premiums. The cash value may be accessed for emergencies, supplementing retirement income, large purchases, or other long-term needs.

    Ideal For: People who want long-term coverage with savings

    Death Benefit Uses: Estate planning, legacy, long-term protection

    Cash Value Uses: Emergency funding, retirement planning, education funding, large purchases

    brandableContent

    The need for life insurance

    Once you understand your options, the next step is identifying the purpose of the insurance in your life. Most needs fall into three main categories:

    Dependents

    Whether it’s young children, a spouse, or even elderly parents, many families have one or more people who depend on their income. In these cases, life insurance plays an important role in maintaining the household’s financial stability. It can help pay for groceries, monthly bills, childcare, tuition, or even a car replacement down the road. Think of it as a financial bridge that helps your family maintain their standard of living while they adjust to life without your income.

    Debts

    Do you have a mortgage? A home equity line of credit? Maybe a personal loan or credit cards with balances that carry over month to month? If something unexpected were to happen, life insurance can ensure those debts don’t fall on your family’s shoulders. A properly structured policy can provide enough to pay off major liabilities, giving your family financial breathing room and the security of keeping their home or lifestyle intact.

    Final Expenses

    End-of-life costs often catch families off guard. Between funeral expenses, legal and accounting fees, final tax returns, and probate costs, the total can easily reach into the tens of thousands. A life insurance policy can provide immediate funds to help cover these costs without dipping into savings or relying on credit. For many retirees or aging parents, this is one of the biggest reasons to have a policy—even a small one.

    Bringing It All Together

    Choosing the right life insurance depends on your personal and family goals. Whether you’re protecting your home, your loved ones’ lifestyle, or planning for future expenses, there’s a policy that fits your needs.

    If you’re not sure where to start, a good first step is reviewing your current debts, thinking through future costs, and considering who depends on you.

    We’re here to help you choose the right coverage—get in touch.

    Disclaimer

    This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

    https://crossroadsfinancial.ca/wp-content/uploads/2025/06/Personal-Life-Insurance-Planning-FI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2025-06-02 14:29:082025-06-02 14:29:28Personal Life Insurance Planning

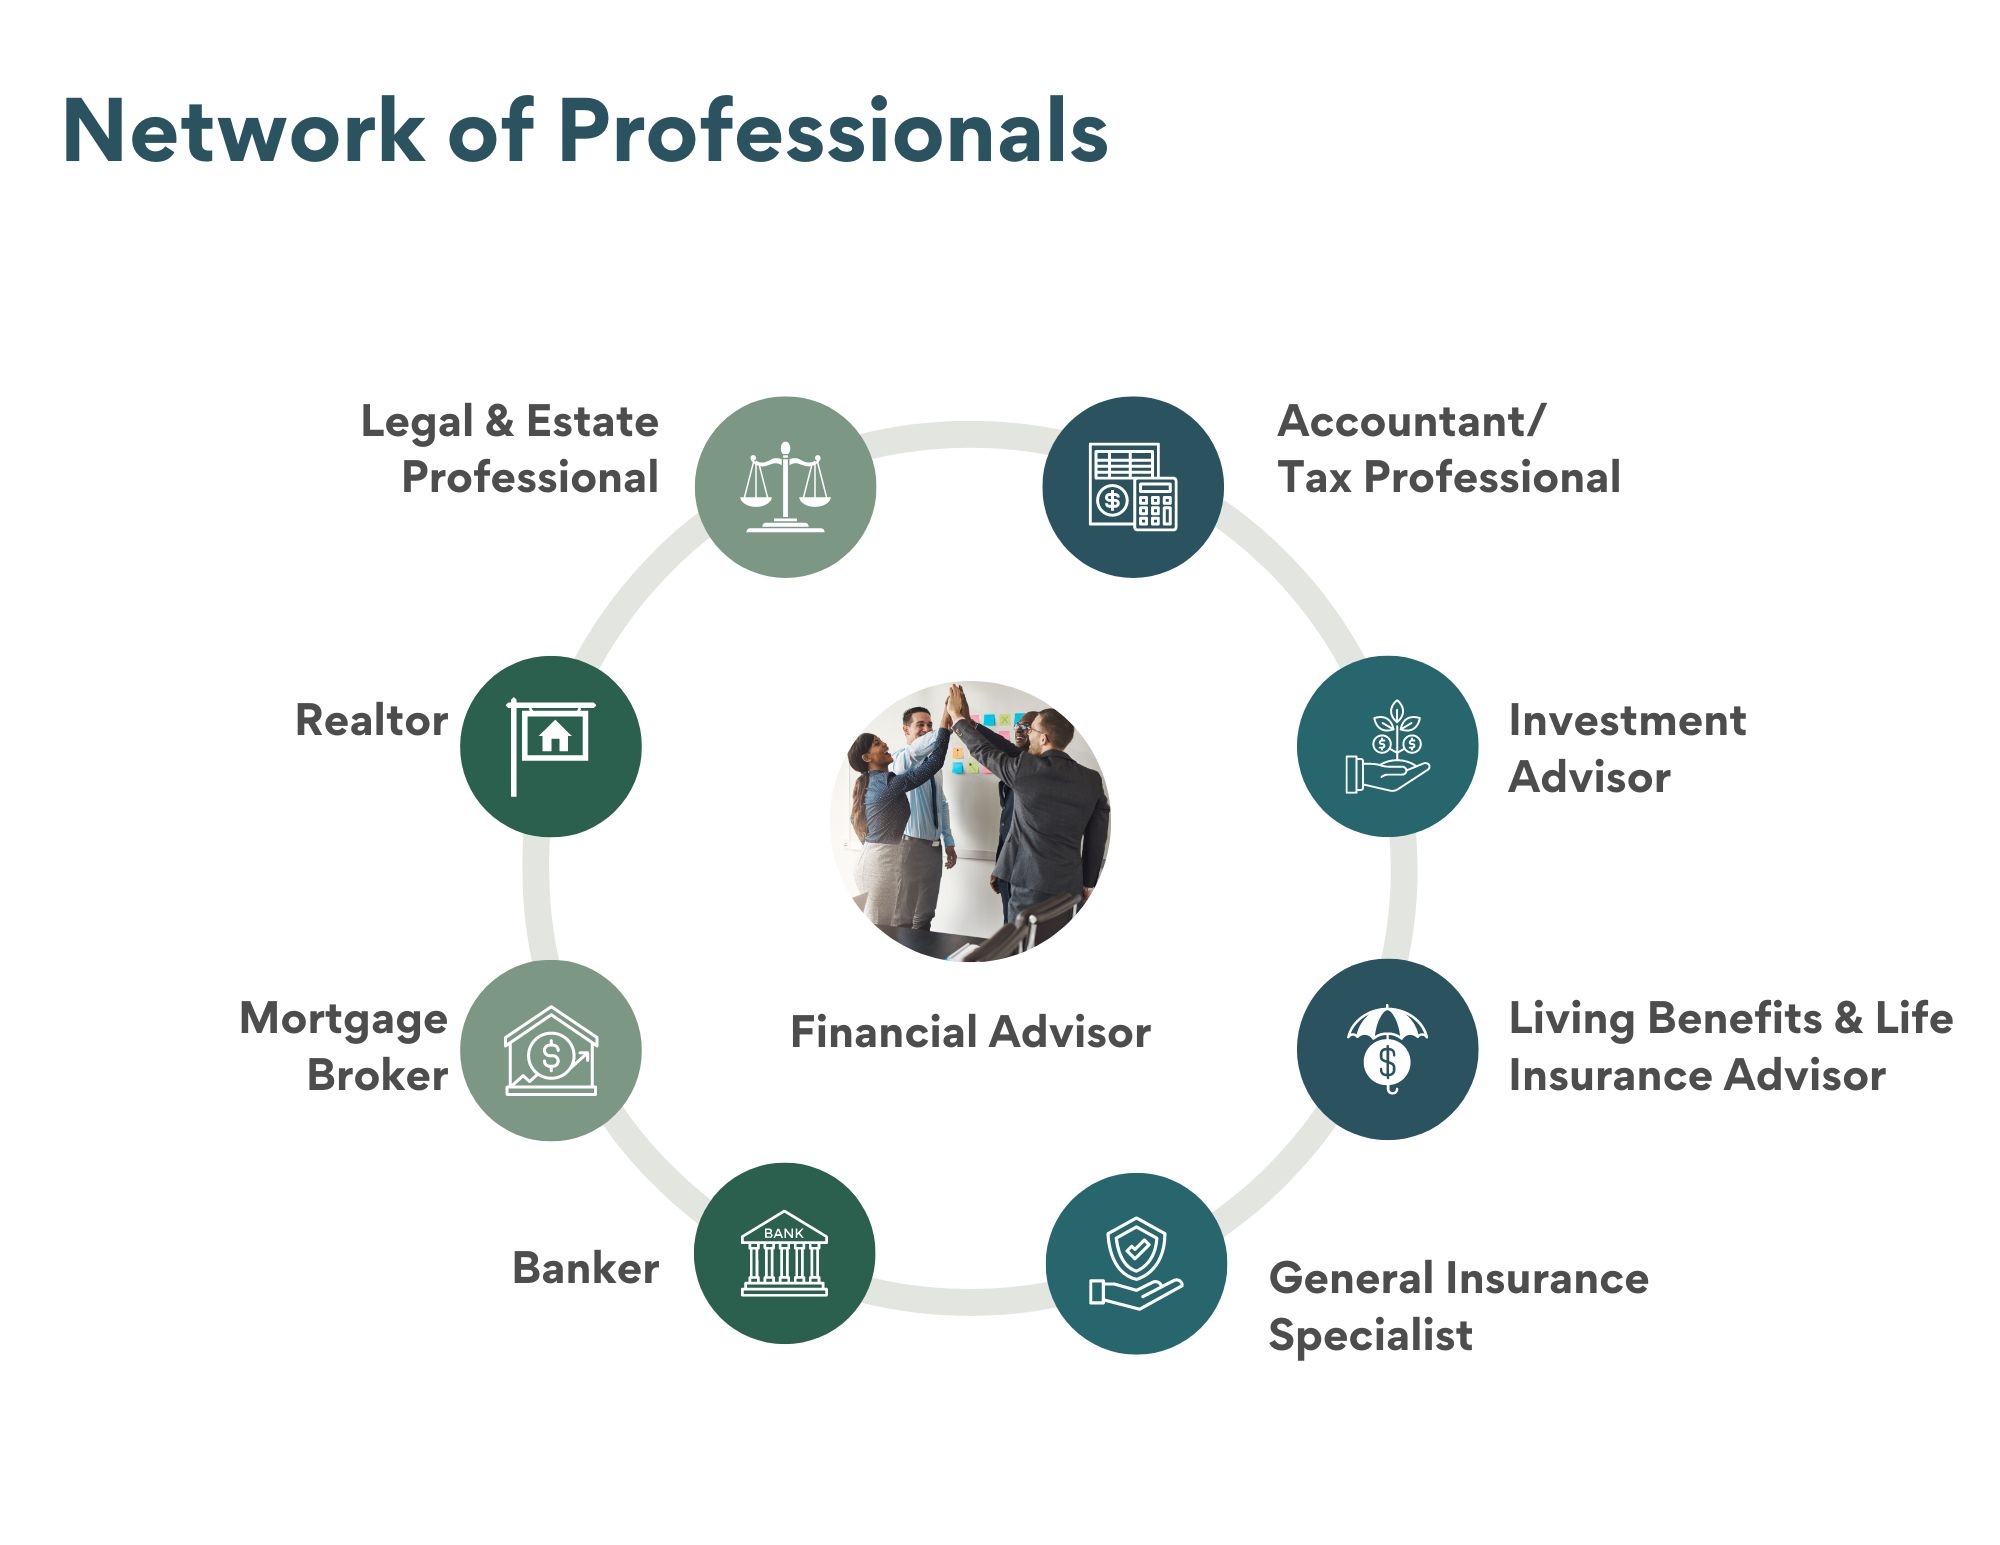
    Network of Professionals

    June 3, 2024/in Accountants, Blog, Business Owners, Center of Influences, Estate Planning, Family, farmers, financial advice, Financial Planning, incorporated professionals, individuals, Insurance, Investment, life insurance/by Crossroads Financial Inc.

    Our Network of Professionals

    As a financial advisor, my primary goal is to help you achieve financial clarity. I do this by accessing a network of dedicated professionals, each bringing their unique expertise to the table. Together, we provide personalized advice and services that help you make informed decisions and secure your future.

    Financial Advisor

    Think of me as your financial coordinator. I help you figure out your goals, create plans to achieve them, and keep everything on track. Whether it’s planning for retirement, managing investments, or saving for a major purchase, I have access to a network of professionals who ensure every aspect of your financial life works together smoothly.

    Accountant/Tax Professional

    Having an accountant or tax professional in your financial network is essential for keeping your financial records in order. They handle tasks like bookkeeping, preparing financial statements, and assisting with tax planning. Their role is particularly important during tax season. They help you file your taxes accurately and on time, taking the stress out of the process. By optimizing your tax strategies and ensuring everything is reported correctly, they help you save money. Their skills are invaluable for both your immediate needs and long-term financial planning.

    Investment Advisor

    Investment advisors focus on building and managing investment portfolios tailored to your short-term, medium-term, and long-term goals. They thoroughly research the market, evaluate investment opportunities, and offer valuable insights to help you create a well-rounded portfolio. Whether you’re saving up for a major purchase, planning for retirement, or aiming for other financial milestones, they assist in choosing the right investment vehicles, such as RRSPs, TFSAs, RRIFs, and non-registered accounts, to support your financial stability and future needs.

    Life Insurance and Living Benefits Advisor

    Life insurance and living benefits advisors are here to help you protect your greatest asset: yourself. Their job is to make sure you and your family are financially secure if unexpected events occur. These advisors walk you through different insurance options, including disability insurance, critical illness insurance, and life insurance, to find the coverage that fits your needs best. By understanding your unique situation and recommending the right policies, they provide you with peace of mind, knowing that you have a safety net in place for life’s uncertainties.

    General Insurance Specialist

    General insurance specialists cover a wide range of insurance needs, including auto, property, travel, and liability insurance. They assess your risks and recommend policies that provide the protection you need. Their advice helps you understand your options, compare quotes, and select the best policies to safeguard your assets, ensuring you are well-protected in various aspects of your life.

    Banker

    Bankers are there to help you navigate a wide range of financial services, especially when it comes to getting loans and credit products. They offer advice on securing personal loans, understanding credit options, and managing debt effectively. Whether you’re looking to finance a major purchase, consolidate debt, or build your credit, bankers provide the support and guidance you need to make informed financial decisions.

    Mortgage Broker

    Mortgage brokers assist you in securing financing for property purchases by accessing multiple lenders on your behalf. They assess your financial situation, compare mortgage products from various sources, and recommend the best options for you. With their ability to shop around and understand different interest rates, loan terms, and application processes, they ensure you get the best possible mortgage deal, making homeownership more accessible and affordable.

    Realtor

    Realtors are your go-to professionals for buying or selling property. They provide market insights, negotiate deals, and manage the legal aspects of real estate transactions. With their knowledge of local market trends and property values, realtors help you make informed decisions whether you’re purchasing a home, investing in real estate, or selling property.

    Legal & Estate Professional

    Legal and estate professionals play a vital role in your financial planning by handling the legal side of things, such as estate planning, wills, trusts, and probate. They make sure your assets are distributed according to your wishes and that all the necessary legal documents are properly set up. Their guidance helps you reduce estate taxes and smoothly navigate the legal processes, ensuring your wealth is transferred to future generations just as you intended.

    Having a network of financial professionals is essential for achieving financial well-being. Each member brings their own expertise to address different aspects of your finances, from investments and insurance to legal and real estate matters. As your financial advisor, I act as the coordinator, ensuring that all these professionals work together seamlessly. By leveraging their combined knowledge and skills, you can gain financial clarity and know that every aspect of your financial life is taken care of.

    Ready to take control of your financial future? Contact us today.

    https://crossroadsfinancial.ca/wp-content/uploads/2024/06/Network-of-Professionals-FI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-06-03 12:01:592024-06-03 12:21:51Network of Professionals

    How To Use Insurance To Provide Your Family With Financial Protection

    May 1, 2024/in Blog, life insurance/by Crossroads Financial Inc.

    How To Use Insurance To Provide Your Family With Financial Protection

    The best way to provide your family with financial protection is with solid insurance planning. These three types of insurance will ensure your family has the financial resources they need if you die, are injured, or become ill:

    • Life insurance.
    • Critical illness insurance.
    • Disability insurance.

    Life Insurance

    Life insurance is an inexpensive way to ensure your family will have access to a tax-free lump sum payment after your death. Whether you want to give your grandchildren a helping hand getting started in life or provide financial resources for a stay-at-home parent, life insurance can be a great way to do it!

    You have two main options when it comes to life insurance – term insurance and permanent life insurance.

    With term insurance, you’ve got life insurance coverage for a set period (for example, five years). Premiums for term insurance are lower than for permanent life insurance, but they will rise as you age or your health changes.

    With permanent life insurance, you’ve got lifetime coverage. You’ll pay more in premiums at first, but the cost will be less overall than if you buy term insurance for your entire life. Some permanent life insurance policies also allow you to contribute money beyond your premiums, where it can grow tax-free.

    Not sure which type is best for you? We can help you figure this out!

    Critical Illness Insurance

    With critical illness insurance, you will be eligible for a tax-free lump sum of money if you’re diagnosed with a significant illness such as cancer or a stroke. While anyone can benefit from this insurance, it’s essential for self-employed people who don’t have employee benefits to help tide them over while recovering or receiving treatment.

    You can spend the lump sum any way you want, including paying off your mortgage, paying for treatment not covered by provincial health care, or putting aside money for your children’s future.

    Depending on the type of critical illness policy you select, you may be able to get a “return of premium” option, which means your premiums will be returned to you if you never make a claim. We can explain how to option works and what coverage we think is best for you.

    Disability Insurance

    Most people assume that they’ll never become disabled. But the stark reality is that 1 in 5 Canadians are considered to be living with a disability. If you couldn’t work anymore because you became disabled, this could have a disastrous impact on your family’s financial stability – especially if you’re self-employed.

    With disability insurance, you’ve got financial protection to ensure you can pay your bills and maintain your family’s standard of living. We can explain how to minimize the cost of your premiums while still getting the coverage you need.

    Protect Your Family

    Book a meeting with us today to get started with insurance planning.

    https://crossroadsfinancial.ca/wp-content/uploads/2024/05/How-to-use-insurance.png 250 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-05-01 06:00:002024-05-01 06:09:04How To Use Insurance To Provide Your Family With Financial Protection

    Retirement Planning

    August 1, 2023/in Blog, Family, health benefits, life insurance, Retirees, retirement, rrsp/by Crossroads Financial Inc.

    brandableContent

    Most of us understand the benefits of sensible retirement planning. Still, it doesn’t feel relatively straightforward when it comes to creating your retirement strategy and putting it into effect. The reality is that, while there are lots of variables to consider, it isn’t as challenging to create an effective plan for retirement as you may think.

    Firstly, let’s consider the merits of a retirement plan. Firstly, the plan will aid you in setting clear goals for your retirement, such as the age that you want to finish work and what you want your retirement to look like in terms of lifestyle. Secondly, it will help you establish how much you need to save to have a retirement that meets your objectives. Thirdly, a plan will allow you to choose your investment options wisely.

    How you know how much you need to save is a common question. This depends on three factors:

    • Your age. It makes sense that starting to save for retirement when you are younger means that you need to save less money than starting later in life.

    • Benefits available to you. There is a range of federal government benefits that you might be eligible for, such as the Canada Pension Plan or Old Age Security.

    • Your plans for your retirement will inevitably affect how much you need to save to fund it.

    If you haven’t started saving for your retirement yet or have less in your retirement savings plan than you would like, take a look at our top tips to accelerate your savings.

    • Make the most of RRSPs and TFSAs to minimize your tax bill and make your money grow faster.

    • Take advantage of any pensions or savings plans that your workplace offers, as your employer’s contributions can add extra value to your fund.

    • Look at your spending habits to identify opportunities to cut back outgoings and save more.

    • Think about putting spare money into your retirement fund.

    Taking steps to create an effective retirement plan is a decision that will pay off as you approach later life, allowing you to have the savings for the retirement that you deserve.

    Talk to us; we can help.

    https://crossroadsfinancial.ca/wp-content/uploads/2023/08/Retirement-planning.png 281 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2023-08-01 06:00:002023-08-01 06:23:55Retirement Planning

    Life Insurance after 60- is it necessary?

    May 1, 2023/in Blog, Insurance, life insurance/by Crossroads Financial Inc.

    You may have had life insurance for as long as you can remember. You wanted to make sure that your family would be taken care of and be able to pay their bills if anything happened to you.

    But now that you’re older and your children are grown – and hopefully your mortgage is paid off – you may not feel you still need life insurance. This could be a valid assumption; however, there are some circumstances under which it may still make sense for you to have life insurance. They are:

    • You still have substantial debt.

    • You have dependent children or grandchildren.

    • You want to leave a financial legacy.

    You still have substantial debt

    No one likes the thought of leaving their loved ones to pay their debts if they die. If, however, someone has co-signed a loan with you – for example, for a mortgage or a car – and you die, then they will be on the hook for the entire amount.

    If you have life insurance and name your co-signer as the beneficiary, this will help relieve any financial burden your death could cause them.

    You have dependent children or grandchildren

    If you have children who are still dependent on you because they have a mental or physical disability, life insurance can be an excellent way to ensure they will still have access to funds after you die.  Lifelong care can be expensive, and a life insurance benefit will go a long way to helping fund it.

    You may have grandchildren you are caring for or that you are not responsible for but want to leave money they can use towards higher
    education.  A life insurance payout can be a great way to help a grandchild get a good start in life without having to go into debt.

    You want to leave a financial legacy

    You may not have dependent children or grandchildren but still want to leave them something when you die. Life insurance can be a great way to do this without cutting back on your spending during your lifetime.

    Life insurance can also help make sure that you have something to leave everyone in your will. If you have a family cottage, it can
    be complicated to leave it to more than one person or family. Life insurance gives you the option to leave one person or family the cottage and another person or family the cash equivalent.

    We can help you!

    If you’re unsure whether or not it still makes sense to have life insurance after the age of 60, we’d be happy to sit down with you and talk through your options. Give us a call or email us today!

    https://crossroadsfinancial.ca/wp-content/uploads/2023/05/Life-Insurance-after-60.jpg 281 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2023-05-01 06:00:002023-05-01 06:03:18Life Insurance after 60- is it necessary?

    Permanent versus Term Life Insurance – What are the Differences?

    March 2, 2023/in Blog, life insurance/by Crossroads Financial Inc.

    Permanent versus Term Life Insurance – What are the Differences?

    You know you need life insurance – but you’re not sure which kind is best for you. We can help you with that decision.

    There are two main kinds of life insurance:

    • Permanent, which lasts for your entire life.

    • Term, which is only good for a set amount of time.

    No matter which type of life insurance you buy – permanent or term – you can rest easy knowing you’ve provided financial protection for your family.

    Permanent life insurance

    Permanent life insurance is good for your entire life unless you choose to cancel it. It’s an excellent choice to give you peace of mind that you’ll always be covered, even if you develop major health issues later in life.

    There are also benefits to having permanent life insurance beyond guaranteed lifelong coverage:

    • You can use the policy to build up a cash value – making it a good choice for low-risk investing.

    • You may be able to use your permanent life insurance policy as collateral for a loan, making it a good choice for business owners.

    The main drawback to permanent life insurance policies is that the premiums are often more expensive than term life insurance premiums. If, however, you’re thinking long-term and can afford the premiums, permanent life insurance is a great way to ensure you’re always protected and can have some guaranteed money for your estate.

    Term life insurance

    Term life insurance is either valid for a set amount of time (such as five or ten years) or until you reach a set age – for example, 60. You should generally be able to renew your life insurance at the end of each term, but your premiums may go up.

    Term life insurance premiums are cheaper than permanent life insurance premiums – at least, you are younger and healthier (as the risk of you dying is lower). Your premiums will increase as you age or develop health issues.

    You can’t use term life insurance as collateral for a loan or use the policy to build up a cash value. There are lots of benefits to term life insurance, though – it’s a good choice for you if you want low premiums, easy-to-understand insurance, and only need it for a set amount of time – such as while you have a mortgage or young children.

    We can help you decide between permanent and term life insurance

    If you’re not sure what kind of life insurance is best for you, we can help. We’re happy to talk to you to get more information about your insurance needs. We can then discuss what each type of insurance will cost you and which type of insurance we feel is best for you.

    Give us a call today!

    https://crossroadsfinancial.ca/wp-content/uploads/2023/03/Permanent-vs-Term.png 281 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2023-03-02 06:00:002023-03-02 12:19:05Permanent versus Term Life Insurance – What are the Differences?

    Retirement Planning for Business Owners – Checklist

    October 1, 2021/in Blog, Business Owners, corporate, health benefits, life insurance, long term care, pension plan, rrsp, Tax Free Savings Account/by Crossroads Financial Inc.

    As a business owner, one of your challenges is learning how to balance between reinvesting into the business and setting money aside for personal savings. Since there are no longer employer-sponsored pension plans and the knowledge that retirement will come eventually, it’s important to have a retirement plan in place.

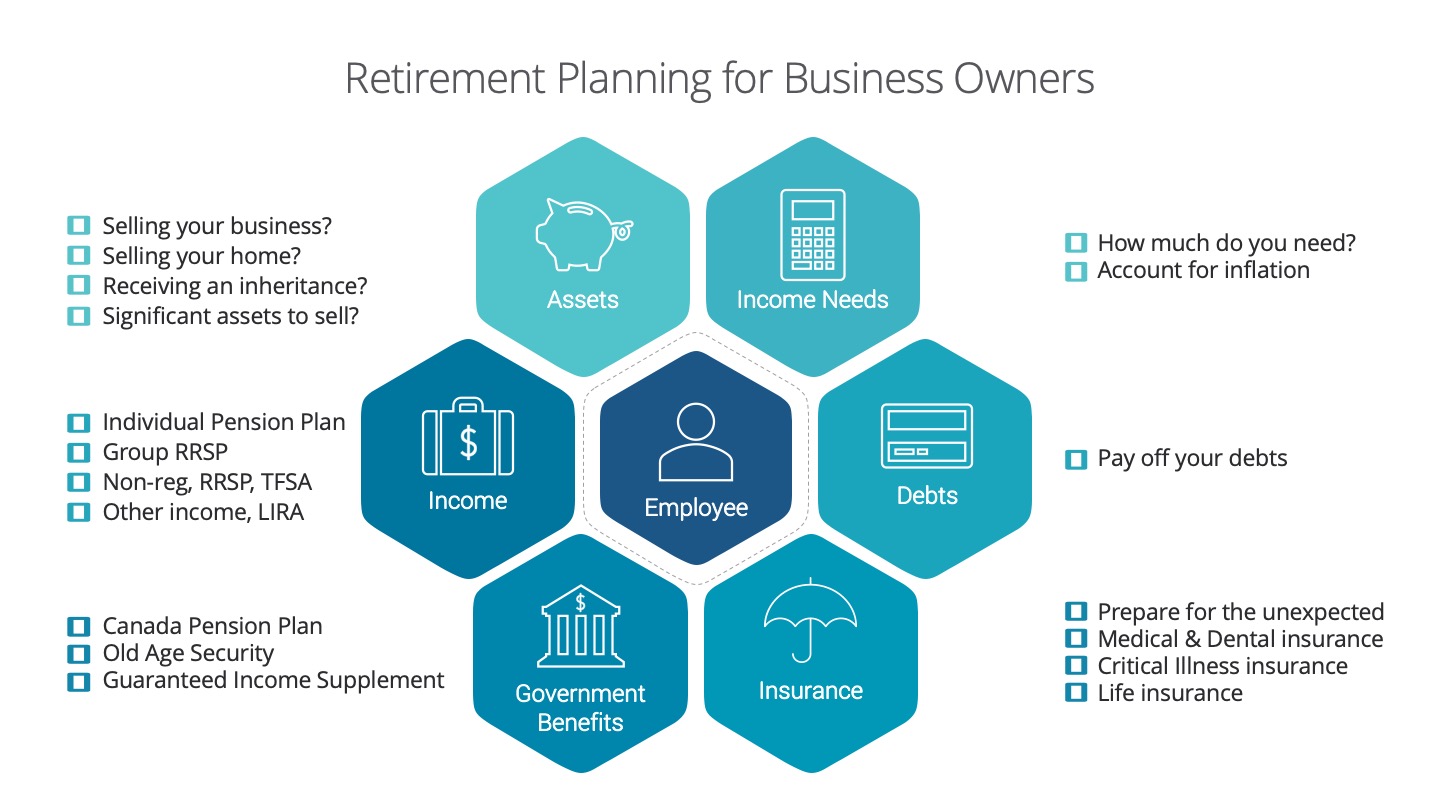
    We’ve put together an infographic checklist that can help you get started on this. We know this can be a difficult conversation so we’re here to help and provide guidance to help you achieve your retirement dreams.

    Income Needs

    • Determine how much income you will need in retirement.

    • Make sure you account for inflation in your calculations.

    Debts

    • You should try to pay off your debts as soon as you can; preferably before you retire.

    Insurance

    • As you age, your insurance needs change. Review your insurance needs, in particular your medical and dental insurance because a lot of plans do not provide health plans to retirees.

    • Review your life insurance coverage because you may not necessarily need as much life insurance as when you had dependents and a mortgage, but you may still need to review your estate and final expense needs.

    • Prepare for the unexpected such as a critical illness or a need for long-term care.

    Government Benefits

    • Check what benefits are available for you upon retirement.

    • Canada Pension Plan- decide when would be the ideal time to apply and receive CPP payments. Business owners are in a unique position to control how much can be contributed to CPP by deciding to pay salary or dividends. (Dividends don’t trigger CPP contributions.)

    • Old Age Security- check pension amounts and see if there’s a possibility of clawback.

    • Guaranteed Income Supplement- if your income is low enough, you could apply for GIS.

    Income

    • Are you a candidate for an individual pension plan (IPP)? IPPs can provide higher contributions than typically permitted to an RRSP and the ability to create a lifelong pension.

    • Check if your business is a candidate for a group RRSP or company pension plan. This is a great way for you to build retirement savings and provide benefits for your employees and business too.

    • Make sure you are saving on a regular basis towards retirement- in an RRSP, TFSA, or non-registered. Since you can control how you get paid, salary or dividends, dividends are not considered eligible income to create RRSP room, therefore you should make sure you have the optimal mix of both to achieve your financial goals.

    • Ensure your investment mix makes sense for your situation.

    • Don’t forget to check if there are any other income sources.  (ex. rental income, side hustle income, etc.)

    Assets

    • The sale of your business can be part of your retirement nest egg. Therefore, you should make sure you know the valuation of your business and your plan to sell the business to your family, employees, partners or a third party. You should also know when you decide to sell your business too.

    • Are you planning to use the sale of your home or other assets to fund your retirement?

    • Will you be receiving an inheritance?

    One other consideration that’s not included in the checklist is divorce. This can be an uncomfortable question, however divorce amongst adults ages 50 and over is on the rise and this can be financially devastating for both parties.

    Next steps…

    • Contact Us about helping you get your retirement planning in order so your retirement dreams can be achieved.

    https://crossroadsfinancial.ca/wp-content/uploads/2021/10/retirementPlanningBO.jpeg 810 1440 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2021-10-01 06:00:002021-10-01 06:06:07Retirement Planning for Business Owners – Checklist

    Paying for Education

    September 1, 2021/in Blog, Debt, Family, life insurance/by Crossroads Financial Inc.

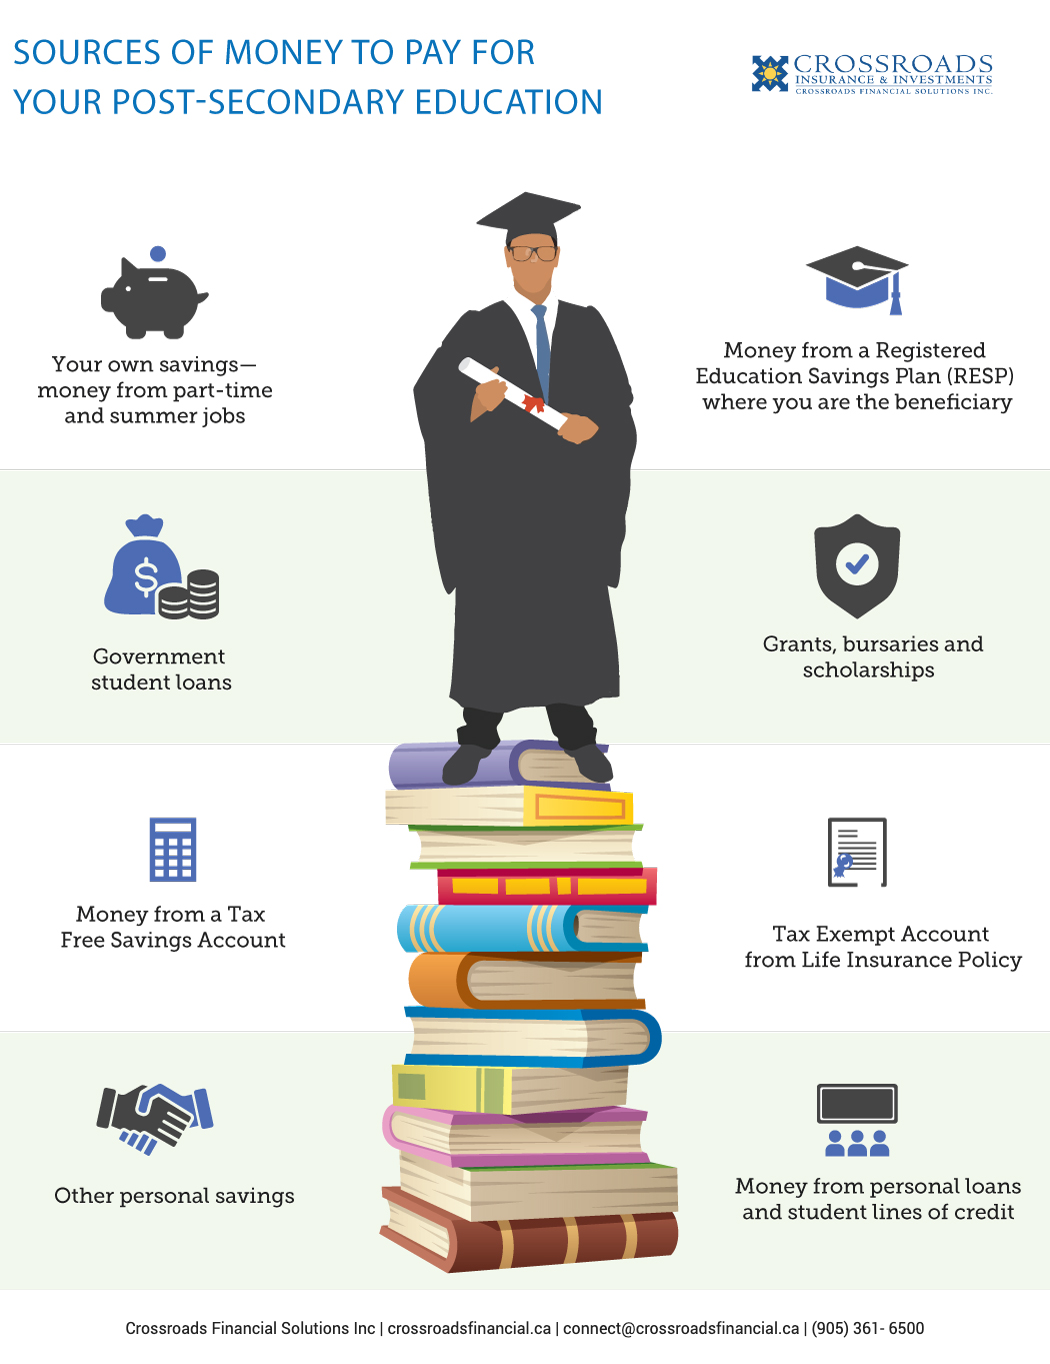
    Post-secondary education can be expensive, however having the opportunity to plan for it helps with making sure that you’re capable to meet the costs of education. In addition, when you have a plan, it’s easier to make financial decisions that align with your goals and provide peace of mind. In the infographic, we outline 7 sources of funds for paying for post-secondary education: 

    • Registered Education Savings Plan

    • Tax Free Savings Account

    • Life Insurance

    • Scholarships, grants, bursaries

    • Personal Loans, Lines of Credit

    • Government Student Loan

    • Personal Savings 

    If you need help planning to save for your child’s post-secondary education, contact us!

    https://crossroadsfinancial.ca/wp-content/uploads/2021/09/PayingForEducation.png 500 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2021-09-01 06:00:002021-09-01 16:15:06Paying for Education
    Page 1 of 212

    Book a Meeting

    Search Blog Posts

    Search Search

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    Categories

    • 2020
    • 2020 Only
    • 2021
    • 2022
    • 2022 Only
    • 2023
    • 2024
    • 2025
    • 2026
    • Accountants
    • Blog
    • Budget
    • Business Owners
    • business owners
    • buy sell
    • Center of Influences
    • Charitable Gifting
    • Coronavirus
    • Coronavirus – Associates
    • Coronavirus – Practice Owners
    • Coronavirus – Practice Owners
    • Coronavirus – Retired
    • Coronavirus – Retiring
    • Coronavirus – Students
    • corporate
    • critical illness insurance
    • Debt
    • dental benefits
    • disability
    • disability insurance
    • Estate Planning
    • Family
    • farmers
    • financial advice
    • Financial Planning
    • Government Budget
    • Group Benefits
    • health benefits
    • incorporated professionals
    • individuals
    • Insurance
    • Investment
    • life insurance
    • long term care
    • mortgage
    • Ontario Only
    • pension plan
    • personal finances
    • Professional Corporations
    • Professionals
    • rdsp
    • Registered Education Savings Plan
    • Retirees
    • retirement
    • rrsp
    • tax
    • Tax Free Savings Account
    • travel insurance

    Get in Touch

    Crossroads Financial Solutions Inc.
    Tel: (905) 361- 6500
    Email: connect@crossroadsfinancial.ca
    TF: 1-877-607-6237

    4255 Sherwoodtowne Blvd, Suite 102
    Mississauga, Ontario
    L4Z 1Y5

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    About

    Everyone has their own dreams. Protecting those goals is our mission. We believe there is no “One Size Fits All” when it come to planning your insurance needs and investment goals.
    We encourage you to have a discovery meeting with us.

    ©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
      Scroll to top Scroll to top Scroll to top