Crossroads Insurance & Investments
  • HOME
  • SERVICES
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING FOR YOUNG FAMILIES
      • ESTATE PLANNING FOR RETIREES & MATURE FAMILIES
      • CHARITABLE GIVING
      • MANULIFE ONE
    • NEW IMMIGRANTS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
      • SUCCESSION PLANNING
      • GROUP BENEFITS
        • HEALTH BENEFITS
        • RETIREMENT BENEFITS
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
    • INSURANCE
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • MORTGAGE LIFE INSURANCE
      • LONG TERM CARE
      • CROSS BORDER INSURANCE
    • INVESTMENT
      • REGISTERED EDUCATION SAVINGS PLAN
      • TAX FREE SAVINGS ACCOUNT
      • REGISTERED RETIREMENT SAVINGS PLAN
      • REGISTERED RETIREMENT INCOME FUND
      • ANNUITIES
  • ABOUT
    • ABOUT
    • PROCESS
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
    • CALCULATORS
  • CONTACT
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

    Archive for category: Professionals

    2025 Federal Budget Highlights

    November 5, 2025/in 2025, Blog, business owners, Estate Planning, Family, Financial Planning, incorporated professionals, individuals, Investment, mortgage, personal finances, Professional Corporations, Professionals, Retirees, retirement, tax/by Crossroads Financial Inc.

    2025 Federal Budget Highlights

    On November 4, 2025, the budget was delivered by the Honourable François-Philippe Champagne, Minister of Finance and National Revenue.

    The 2025 Federal Budget focuses on stability, simplicity, and long-term growth. There are no broad tax increases or major new spending programs. Instead, the government is emphasizing restraint, modernization, and productivity.

    For individuals and business owners, the goal is clear: help Canadians access benefits more easily, encourage investment in innovation and clean energy, and update trust and estate rules to maintain fairness across the system.

    Economic Overview

    Canada’s federal deficit is projected at $78.3 billion for 2025–26. The government aims to stabilize the debt-to-GDP ratio while maintaining funding for priorities such as housing, defence, and clean energy.

    Spending will focus on programs that improve productivity, while efficiency reviews across departments are expected to reduce overlap and administrative costs. This marks a shift toward sustainable fiscal management and practical, targeted investments.

    Personal and Family Tax Measures

    Several measures are designed to make life more affordable, particularly for first-time home buyers, caregivers, and lower-income households.

    Eliminating the GST for First-Time Home Buyers

    First-time home buyers will not pay the 5 percent federal GST on new homes priced up to $1 million. For new homes between $1 million and $1.5 million, a partial GST reduction applies. This change provides meaningful savings and makes new construction more accessible for Canadians entering the housing market.

    Home Accessibility Tax Credit

    Starting in 2026, expenses can no longer be claimed under both the Home Accessibility Tax Credit and the Medical Expense Tax Credit. The rule prevents duplicate claims but continues to support renovations that make homes safer and more accessible for seniors or individuals with disabilities.

    Top-Up Tax Credit

    To balance the reduction in the lowest federal tax bracket—from 15 percent to 14.5 percent in 2025, and 14 percent in 2026—the government introduced a Top-Up Tax Credit to preserve the value of non-refundable credits such as tuition, medical, and charitable amounts. This temporary measure, available from 2025 through 2030, ensures Canadians receive the same credit value even as rates decrease.

    Personal Support Workers (PSW) Tax Credit

    A new refundable tax credit equal to 5 percent of eligible income, up to $1,100 per year, will be available for certified personal support workers beginning in 2026. The measure acknowledges the importance of care professionals and provides direct relief to those in long-term and community-care roles.

    Automatic Federal Benefits

    Starting in 2025, the Canada Revenue Agency will begin automatically filing simple tax returns for eligible Canadians who do not normally file. This will allow low-income earners and seniors to receive benefits such as the Canada Workers Benefit, GST/HST Credit, and Canada Carbon Rebate automatically. Those with more complex financial situations will continue to file regular returns.

    Registered Plans, Trusts, and Estate Planning

    The budget introduces several changes affecting trusts and registered plans—key tools in long-term financial and estate planning.

    Bare Trust Reporting Rules

    Implementation of new bare trust reporting requirements has been delayed. The rules will now apply to taxation years ending December 31, 2026, or later. This postponement gives individuals, trustees, and professionals more time to prepare for the new filing obligations.

    The 21-Year Rule for Trusts

    Trusts—particularly most personal or family trusts—are generally considered to have sold and repurchased their capital property every 21 years (a “deemed disposition”). This rule prevents indefinite deferral of capital-gains tax on assets that grow in value.

    When property is moved on a tax-deferred basis from one trust to another, the receiving trust normally inherits the original 21-year anniversary date so that tax timing does not reset.

    Some estate-planning arrangements have transferred trust property indirectly—for example, through a corporation or a beneficiary connected to a second trust—so that the transfer did not appear to be trust-to-trust. These arrangements effectively extended the period before capital gains would be recognized.

    Budget 2025 broadens the anti-avoidance rule to include indirect transfers. Any transfer of property made on or after November 4, 2025, that effectively moves assets from one trust to another will retain the original 21-year schedule.

    For families that use trusts in estate or business-succession planning, this change reinforces the importance of reviewing structure and timing. Trusts remain valuable for asset protection, legacy planning, and income distribution—this update simply ensures consistent application of the 21-year rule.

    Qualified Investments for Registered Plans

    Beginning January 1, 2027, all registered plans—RRSPs, TFSAs, FHSAs, RDSPs, and RESPs—will follow a single harmonized list of qualified investments. Small-business shares will no longer qualify for new contributions, though existing holdings will remain grandfathered. The update simplifies compliance and clarifies which assets can be held in registered accounts.

    Business and Investment Incentives

    For business owners, Budget 2025 provides opportunities to reinvest, innovate, and modernize operations, with emphasis on manufacturing, research, and clean technology.

    Immediate Expensing for Manufacturing and Processing Buildings

    Businesses can now claim a 100 percent deduction for eligible manufacturing and processing buildings acquired after Budget Day and available for use before 2030. This full write-off improves cash flow and encourages earlier expansion. The benefit will gradually phase out after 2033.

    Scientific Research and Experimental Development (SR&ED)

    The refundable SR&ED tax credit limit has increased from $3 million to $6 million per year, effective for taxation years beginning after December 16, 2024. This expansion strengthens support for small and medium-sized Canadian businesses investing in innovation and technology.

    Tax Deferral Through Tiered Corporate Structures

    To prevent deferrals of tax on investment income, new rules will suspend dividend refunds for affiliated corporations with mismatched fiscal year-ends. This ensures consistent taxation within corporate groups and aligns refund timing with income recognition.

    Agricultural Co-operatives

    The tax deferral for patronage dividends paid in shares has been extended to December 31, 2030, continuing to support agricultural co-operatives and their members.

    Clean Technology and Clean Electricity Investment Credits

    Clean-technology and clean-electricity incentives have been expanded to include additional critical minerals—such as antimony, gallium, germanium, indium, and scandium—used in advanced manufacturing and renewable energy production. The Canada Growth Fund can now invest in qualifying projects without reducing the amount of credit companies can claim, keeping the incentive structure attractive for green investment.

    Canadian Entrepreneurs’ Incentive

    The government has confirmed it will not proceed with the previously proposed Canadian Entrepreneurs’ Incentive. The existing Lifetime Capital Gains Exemption remains unchanged and continues to apply to the sale of qualified small-business shares.

    Tax Simplification and Repealed Measures

    To simplify administration and reduce complexity, two taxes are being repealed:

    – Underused Housing Tax, beginning in 2025

    – Luxury Tax on aircraft and vessels for purchases made after November 4, 2025

    In addition, the Canada Carbon Rebate will issue its final household payment in April 2025, with no rebates available for returns filed after October 30, 2026. These changes are meant to streamline compliance and eliminate programs that were costly to administer.

    Government Direction and Spending Priorities

    Beyond taxation, the budget sets out the government’s broader policy priorities.

    Downsizing Government: A comprehensive efficiency review is underway to eliminate duplication across departments and generate long-term savings.

    Cuts to Immigration: To ease pressure on housing and infrastructure, temporary-resident levels will be reduced by about 20 percent over two years, while maintaining pathways for essential workers.

    Defence Spending: Canada will invest an additional $7 billion over five years to strengthen NATO participation, Arctic defence, and cybersecurity. By 2030, defence spending is expected to reach 1.8 percent of GDP.

    Oil and Gas Emission Cap: A phased-in cap starting in 2026 will allow companies to meet targets through carbon-capture and clean-tech investments rather than penalties.

    Final Thoughts

    For individuals, the most relevant updates include GST relief for first-time home buyers, improved benefit access, and continued tax relief for caregivers and support workers. For business owners, the focus remains on productivity—through immediate expensing, expanded SR&ED credits, and clean-tech investment incentives. For families using trusts or inter-generational structures, the clarified 21-year rule reinforces transparency in estate planning.

    If you’d like to review what these changes mean for you or your business, please get in touch. We can look at your goals and make sure you’re well prepared for the year ahead.

    https://crossroadsfinancial.ca/wp-content/uploads/2025/11/Federal-Budget-2025.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2025-11-05 11:23:512025-11-05 11:24:032025 Federal Budget Highlights

    Tax Tips for Filing Your 2024 Income Tax Return

    March 31, 2025/in 2025, Blog, financial advice, incorporated professionals, individuals, Investment, pension plan, personal finances, Professionals, tax/by Crossroads Financial Inc.

    The deadline for filing your 2024 income tax return is April 30, 2025. Stay informed about the latest tax changes and benefits available to maximize your savings and ensure compliance. This guide outlines the key updates and important deductions and credits separated into sections for Individuals and Families, and Self-Employed Individuals.

    For Individuals and Families

    Alternative Minimum Tax (AMT)

    • Increased minimum tax rate and basic exemption threshold.

    • Modified calculation for adjusted taxable income affecting foreign tax credits and minimum tax carryovers.

    • Limited value on most non-refundable tax credits.

    Canada Pension Plan (CPP) Enhancement

    • The standard CPP contribution rate remains at 5.95% for both employees and employers on earnings up to $68,500 (the Year’s Maximum Pensionable Earnings or YMPE) in 2024.

    • Additionally, employees and employers each contribute an extra 4% on earnings between the YMPE ($68,500) and the Year’s Additional Maximum Pensionable Earnings (YAMPE) of $73,200 in 2024.

    Home Buyers’ Plan (HBP)

    • Withdrawal limit increased from $35,000 to $60,000 after April 16, 2024, with temporary repayment relief available.

    Volunteer Firefighters and Search and Rescue Volunteers

    • Amounts increased from $3,000 to $6,000 for eligible individuals completing at least 200 hours of combined volunteer service.

    Basic Personal Amount (BPA)

    • For 2024, the Basic Personal Amount (BPA) has increased to $15,705 for taxpayers with net income up to $173,205.

    • For taxpayers with net incomes above this amount, the BPA is gradually reduced, reaching a minimum of $14,138 at incomes of $235,675 or higher.

    Short-term Rentals

    • Expenses related to non-compliant short-term rentals are no longer deductible after January 1, 2024.

    Popular Tax Credits and Deductions

    Canada Training Credit (CTC) Eligible taxpayers aged 26 to 65 can claim this refundable tax credit to cover a portion of eligible tuition and fees for training or courses to enhance their skills.

    Canada Caregiver Credit (CCC) This non-refundable tax credit supports individuals caring for family members or dependents with a physical or mental impairment. The amount varies based on the dependent’s relationship, net income, and circumstances.

    Child Care Expenses Child care expenses, such as daycare, nursery schools, day camps, and boarding schools, are deductible if incurred to enable a parent or guardian to work, pursue education, or conduct research.

    Disability Tax Credit (DTC) The DTC provides a non-refundable tax credit for individuals with disabilities or their caregivers to reduce the amount of income tax payable. Applicants must have a certified disability lasting at least 12 months.

    Moving Expenses Deductible moving expenses include transportation and storage costs, travel expenses, temporary living costs, and incidental expenses incurred when relocating at least 40 kilometers closer to a new work location, educational institution, or business location.

    Interest Paid on Student Loans Interest paid on eligible student loans can be claimed as a non-refundable tax credit. The loans must be under federal, provincial, or territorial student loan programs.

    Donations and Gifts Donations made to registered charities or other qualified organizations qualify for non-refundable federal and provincial tax credits. Typically, you can claim eligible amounts up to 75% of your net income.

    GST/HST Credit The GST/HST credit is a quarterly refundable payment designed to offset the impact of sales tax on low to moderate-income individuals and families. Eligibility is automatically assessed based on your annual tax return.

    For Self-Employed Individuals

    CPP Contributions

    • Enhanced CPP contribution rate for self-employed individuals.

    Filing and Payment Deadlines

    • Tax Return Deadline: June 16, 2025 (June 15 is Sunday).

    • Balance due must be paid by April 30, 2025.

    Reporting Business Income

    • Report income on a calendar-year basis for sole proprietorships and partnerships.

    Digital Platform Operators

    • New reporting rules requiring platform operators to collect and report seller information.

    Mineral Exploration Tax Credit

    • Eligibility extended for flow-through share agreements signed before April 2025.

    Need Assistance?

    If you’re unsure about your eligibility for specific credits or deductions, reach out to your tax consultant or tax advisor for personalized guidance. They can help you optimize your tax return, maximize your savings, and ensure compliance with CRA regulations.

    Sources

    • Canada Revenue Agency. “What’s New for the 2024 Tax-Filing Season.” Canada.ca, Government of Canada, www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/whats-new.html

    • Canada Revenue Agency. “Maximum Pensionable Earnings and Contributions for 2024.” Canada.ca, Government of Canada, www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2023/maximum-pensionable-earnings-contributions-2024.html

    • “7 Biggest Tax Changes Canadians Need to Know in 2025.” TurboTax Canada, Intuit, turbotax.intuit.ca/tips/7-biggest-tax-changes-canadians-need-to-know-in-2025?srsltid=AfmBOoq7eGj8qrkZ6vLpu4Cogfkln4e7PFGD3aYMrdADQ4za4cbHxo5F

    • “Popular Canadian Tax Benefits, Deductions and Credits in 2023.” TurboTax Canada, Intuit, turbotax.intuit.ca/tips/popular-canadian-tax-benefits-deductions-and-credits-in-2023-14180

    • “Personal Tax: What’s New for the 2024 Tax Year.” CPA Canada, Chartered Professional Accountants Canada, www.cpacanada.ca/news/Accounting/Tax/personal-tax-2024

    • Canada Revenue Agency. “Basic Personal Amount.” Canada.ca, Government of Canada, www.canada.ca/en/revenue-agency/programs/about-canada-revenue-agency-cra/federal-government-budgets/basic-personal-amount.html

    https://crossroadsfinancial.ca/wp-content/uploads/2025/03/Tax-Tips-for-Filing-Your-2024-Income-Tax-Return.png 300 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2025-03-31 05:38:172025-03-31 05:38:22Tax Tips for Filing Your 2024 Income Tax Return

    What is disability insurance?

    August 5, 2024/in Blog, Business Owners, disability, disability insurance, Family, farmers, financial advice, health benefits, incorporated professionals, individuals, Insurance, Professionals/by Crossroads Financial Inc.

    If you cannot work because you are seriously injured or ill, disability insurance will provide you with a monthly, tax-free income to help replace your lost wages.  An injury does not have to be as blatant as a broken leg or arm – suffering from chronic pain or dealing with mental health issues can also qualify you for a disability insurance payout.  

    Why do I need disability insurance?

    Unfortunately, people become disabled – whether temporarily or permanently – quite often. In 2017, over 20 percent of Canadians had one or more disabilities. 

    If you’re disabled, you may lose one of your most valuable assets – your ability to work and bring in a paycheck. Disability insurance can help replace that paycheck for as long as you need it to. Being able to rely on a disability insurance payout means you won’t have to dip into your savings if anything happens to you.

    Disability insurance is especially important if you are self-employed, particularly if you are the family’s sole income earner.

    What if I already have disability insurance through work?

    If you have disability insurance through work, that’s great – but it may not replace 100 percent of your paycheck, especially if you’re off work for a long time. If you purchase private disability insurance, you can:

    • Choose how much coverage you want.
    • Adjust your coverage as needed.
    • Not have to worry if you leave your employer – you won’t lose your disability insurance coverage.

    Having private disability insurance will give you peace of mind that you either have additional coverage if you are employed and at least some disability coverage if you lose your job.

    How does disability insurance work?

    We’d be happy to answer any questions you have about disability insurance. There are five main steps to disability insurance:

    1. Determine the amount of coverage you want. The higher your salary, the more coverage you should get.
    2. Pay your monthly premiums. Factors like your health, your age, and the amount of coverage you have will all impact the cost of your premiums.
    3. File a claim if you become disabled – we can help you with this.
    4. Receive your monthly payments once your waiting period has passed – a longer waiting period can lower your premiums, but it does mean you’ll go longer without any income.
    5. When you are healthy enough to return to work, or your coverage period runs out, you will stop receiving disability insurance payments.

    We’re Here To Help

    If you’d like to know more about disability insurance – from how much it would cost you to what you can file a claim for – we’re here to help! Give us a call today.

    https://crossroadsfinancial.ca/wp-content/uploads/2024/08/What-is-disability-insurance.jpg 300 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-08-05 06:00:072024-08-05 11:37:22What is disability insurance?

    Getting Ready for Money Emergencies

    July 2, 2024/in Blog, Debt, Family, financial advice, Financial Planning, incorporated professionals, individuals, Investment, personal finances, Professionals/by Crossroads Financial Inc.

    brandableContent

    Life can throw unexpected events your way that can hit you in the wallet. Whether it’s falling ill, getting laid off, or facing hefty repair bills for your car or home, these situations can strain your finances. To stay ahead and avoid falling into debt, it’s a good idea to have an emergency fund. This is cash you set aside specifically to handle unforeseen expenses, so you’re not left scrambling for money when the unexpected happens.

    Why Emergency Funds Matter

    An emergency fund is like an insurance policy for unexpected expenses that everyone can benefit from. It’s a stash of money specifically saved to cover daily living costs during emergencies that catch you off guard, such as:

    • Sudden car repairs

    • Vet visits

    • Losing your job

    • Sudden home repairs

    • Medical emergencies

    Creating an emergency fund helps you to:

    • Deal with surprise costs without going into debt

    • Stay away from expensive loans like payday loans or credit card cash advances

    • Keep control of your finances

    • Feel less worried about unexpected expenses.

    An emergency fund offers peace of mind during life’s surprises, preventing debt by covering costs without needing to use up savings or retirement funds, which could result in extra fees.

    How much do you need?

    The amount you should save depends on your financial situation, like how much you earn, what you spend each month, and if you have any dependents. A good rule is to have enough money to cover three to six months of necessary expenses, like rent, groceries, bills, and childcare.

    How to Build Your Emergency Fund

    Building an emergency fund to cover three to six months of essential living expenses might feel overwhelming, but the key is to start saving gradually. Even putting away a small amount regularly can add up significantly over time.

    Here are some ways to build up your emergency fund:

    1. Automate your savings: Pick how much money you want to save, when you want to save it, and how often. Then, arrange for the money to be automatically moved from your regular account to your savings account. You can set up this automatic transfer to happen on your payday. That means the money you’ve chosen to save will be moved as soon as your paycheque is put into your account.

    2. Take advantage of opportunities to boost your emergency fund whenever you can. This might happen when you get extra money, like a tax refund, a pay raise at work, or when you sell things such as a car. Even receiving money as a gift or getting a bonus from your job can help. Additionally, when you finish paying off a loan, consider putting the money you used for payments into your emergency fund instead. Since you’re already used to budgeting for those payments, it’s an easy way to increase your savings without much extra effort.

    3. Make it a habit: Make saving a regular part of your routine by incorporating it into your daily habits. Here are some simple tips to help you get started: drop any loose change into a container whenever you come home, set up a savings, mark your saving dates in advance on your calendar, and use sticky notes on your fridge to remind yourself to save regularly. These small actions can make a big difference in building your savings over time.

    Where to keep your emergency fund?

    Given that emergencies can occur unexpectedly, having quick access to your funds is important. Although a regular chequing account may offer immediate access to your money, it’s best to keep your emergency fund separate from your regular account. This prevents accidental spending on non-emergencies. Look for an account that:

    • Is distinct from your regular spending account

    • Has minimal or no transaction fees

    • Permits penalty-free withdrawals

    • Earns interest on your savings

    Consider exploring “cash equivalents” as an option to invest your money. They’re a bit like cash but can also help your money grow with interest. They’re safe and easy to get your money from. But before you decide, make sure you understand how and when you can take your money out and if there are any extra fees or charges. Examples of cash equivalents include:

    • Savings accounts

    • Chequing accounts

    • High-interest rate savings accounts (HISA)

    • Guaranteed Investment Certificates (GIC)

    • Money market funds

    Having an emergency fund can be a lifeline during tough financial times, preventing you from falling into debt. While there’s no fixed amount you should stash away, assessing your financial situation can guide you in determining your ideal emergency fund size. If you need assistance in planning your emergency fund, don’t hesitate to reach out to us for personalized guidance and support.

    Contact Us

    https://crossroadsfinancial.ca/wp-content/uploads/2024/07/Getting-Ready-for-Money-Emergencies.png 300 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-07-02 15:19:462024-07-02 16:03:51Getting Ready for Money Emergencies

    2024 Federal Budget Highlights

    April 17, 2024/in Blog, Business Owners, Estate Planning, Family, Financial Planning, incorporated professionals, individuals, Investment, mortgage, personal finances, Professional Corporations, Professionals, Retirees, retirement, tax/by Crossroads Financial Inc.

    On April 16, 2024, Canada’s Deputy Prime Minister and Finance Minister, Chrystia Freeland, presented the federal budget.

    While there are no changes to federal personal or corporate tax rates, the budget introduces:

    • An increase in the portion of capital gains subject to tax, rising from 50% to 66.67%, starting June 25, 2024. However, individual gains up to $250,000 annually will retain the 50% rate.

    • The lifetime exemption limit for capital gains has been raised to $1.25 million. Additionally, a new one-third inclusion rate is set for up to $2 million in capital gains for entrepreneurs.

    • The budget confirms the alternative minimum tax changes planned for January 1, 2024 but lessens their impact on charitable contributions.

    • This year’s budget emphasizes making housing more affordable. It provides incentives for building rental properties specifically designed for long-term tenants.

    • Introduces new support measures to aid people buying their first homes.

    • Costs for specific patents and tech equipment and software can now be written off immediately.

    • Canada carbon rebate for small business.

    Capital Gains Inclusion Rate

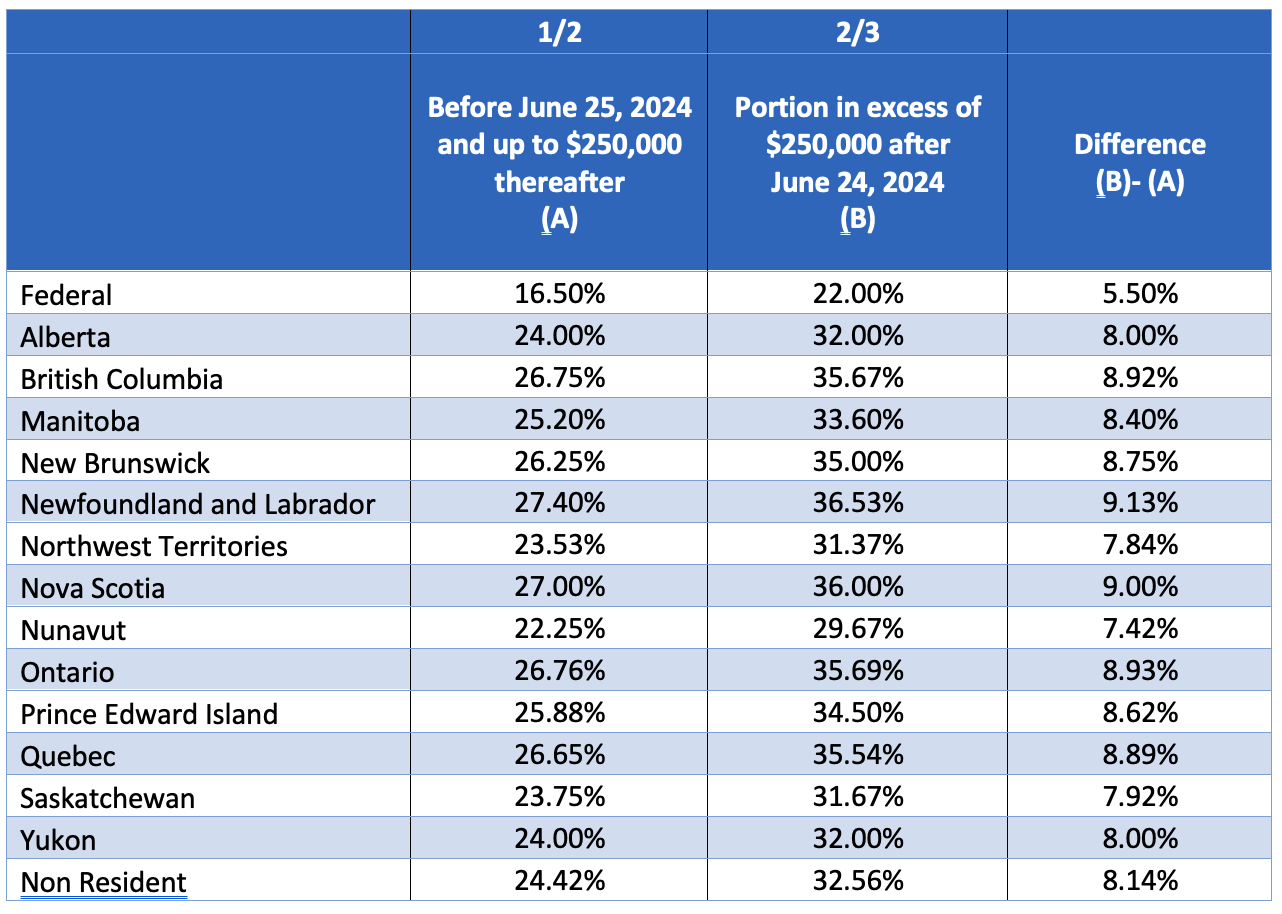
    The budget suggests raising the inclusion rate on capital gains after June 24, 2024:

    • Corporations and trusts, from 50% to 66.67%.

    • Individuals, on capital gains over $250,000 annually, also from 50% to 66.67%.

    For individuals, the $250,000 annual threshold that applies to net capital gains—the amount remaining after offsetting any capital losses. This includes gains acquired directly by an individual or indirectly through entities such as partnerships or trusts. Essentially, this threshold acts as a deductible, considering various factors to determine the net gains eligible for the increased capital gains tax rate.

    Individuals in the highest income bracket, who earn above the top marginal tax rate threshold, will face a higher tax rate on capital gains exceeding $250,000 due to these changes. Furthermore, the budget modifies the tax deduction for employee stock options to align with the updated capital gains taxation rates yet maintains the initial 50% deduction for the first $250,000 in gains. Regarding previously incurred financial losses, the budget plans to adjust the value of these net capital losses from past years so that they are consistent with the current gains, upholding the uniformity with the new inclusion rate.

    The budget outlines transitional rules for the upcoming tax year that straddles the implementation date of the new capital gains rates. If the tax year begins before June 25, 2024, but ends afterward, capital gains realized before June 25 will be taxed at the existing rate of 50%. However, gains accrued after June 24, 2024, will be subject to the increased rate of 66.67%. It’s important to note that the new $250,000 threshold for higher tax rates will only apply to gains made after June 24.

    Consequently, for individuals earning capital gains beyond the $250,000 threshold and who fall into the highest income tax bracket, new rates will be effective as outlined in the table below. Specifically, this pertains to individuals with taxable incomes exceeding $355,845 in Alberta, $252,752 in British Columbia, $1,103,478 in Newfoundland and Labrador, $500,000 in the Yukon, and $246,752 in all other regions.

    Further details and guidance on these new rules are expected to be provided in future announcements.

    Lifetime Capital Gains Exemption

    The budget proposes raising the Lifetime Capital Gains Exemption (LCGE) for qualified capital gains from $1,016,836 to $1.25 million, effective for sales made after June 24, 2024. Additionally, the exemption will once again be adjusted for inflation starting in 2026. This change aims to increase the tax benefits for individuals selling certain types of property, such as small business shares or farming and fishing assets.


    Canadian Entrepreneurs’ Incentive

    The Canadian Entrepreneurs’ Incentive is a new tax measure which provides a reduced inclusion rate on capital gains from the disposition of qualifying small business shares.

    Qualifications for the incentive include:

    • Shares must be of a small business corporation directly owned by an individual.

    • For 24 months before selling, over half the corporation’s assets must be actively used in a Canadian business or be certain connected assets.

    • The seller needs to be a founding investor who held the shares for at least five years.

    • The seller must have been actively involved in the business continuously for five years.

    • The seller must have owned a significant voting share throughout the subscription period.

    • The incentive does not apply to shares linked to professional services, financial, real estate, hospitality, arts, entertainment, or personal care services sectors.

    • The shares must have been acquired at their fair market value.

    • The incentive allows for a reduced inclusion rate of 1/3 for up to $2 million in capital gains during an individual’s lifetime, with this limit being phased in over 10 years.

    This measure will apply to dispositions after December 31, 2024.

    Alternative Minimum Tax (AMT)

    The 2023 budget included updates to the AMT, with proposed changes outlined in the summer of 2023. The budget suggests revising the charitable donation tax credit for AMT calculations, increasing the claimable amount from 50% to 80%.

    Further proposed changes to the AMT include:

    • Permitting deductions for the Guaranteed Income Supplement, social assistance, and workers’ compensation benefits.

    • Exempting employee ownership trusts (EOTs) entirely from AMT.

    • Allowing certain tax credits, like federal political contributions, investment tax credits (ITCs), and labour-sponsored funds tax credit, to be carried forward if disallowed under the AMT.

    These changes would take effect for tax years beginning after December 31, 2023. Additionally, the budget proposes technical amendments that would exempt specific trusts benefiting Indigenous groups from the AMT.

    Employee Ownership Trust (EOT) Tax Exemption

    The budget proposes a tax exemption on up to $10 million in capital gains for individuals selling their businesses to an EOT if certain criteria are met:

    • Sale of shares must be from a non-professional corporation.

    • The seller, or their spouse or common-law partner, must have been actively involved in the business for at least two years prior to the sale.

    • The business shares must have been solely owned by the seller or a related person or partnership for two years before the sale, and mainly used in active business.

    • At least 90% of the EOT’s beneficiaries must be Canadian residents after the sale.

    • If multiple sellers are involved, they must jointly decide how to divide the $10 million exemption

    • If the EOT doesn’t maintain its status or if the business assets used in active business drop below 50% at any point within 36 months after the sale, the tax exemption may be revoked.

    • For Alternative Minimum Tax purposes, the exempted gains will face a 30% inclusion rate.

    • The normal reassessment period for the exemption is extended by three years.

    • The measure now also covers the sale of shares to a worker cooperative corporation.

    This exemption is valid for sales occurring from January 1, 2024, to December 31, 2026.

    Home Buyers Plan (HBP)

    The budget proposes enhancements to the HBP for 2024 and beyond, effective for withdrawals after April 16, 2024. These include:

    • Raising the RRSP withdrawal limit from $35,000 to $60,000 to support first-time homebuyers and purchases for those with disabilities.

    • Extending the grace period before repayment starts from two to five years for withdrawals made between January 1, 2022, and December 31, 2025, deferring the start of the repayment period and thereby providing new homeowners additional time before they need to commence repayments

    Interest Deductions and Purpose-Built Rental Housing

    The budget proposes a selective exemption from the Excessive Interest and Financing Expenses Limitation (EIFEL) rules for certain interest and financing expenses related to arm’s length financing. This exemption is for the construction or purchase of eligible purpose-built rental housing in Canada and applies to expenses incurred before January 1, 2036. To qualify, the housing must be a residential complex with either at least four private apartment units, each with its own kitchen, bathroom, and living areas, or 10 private rooms or suites. Additionally, at least 90% of the units must be designated for long-term rental. This exemption will be effective for tax years starting on or after October 1, 2023, in line with the broader EIFEL regulations.

    Accelerated Capital Cost Allowance (CCA) – Purpose built rental housing

    The budget introduces an accelerated CCA of 10% for new rental projects that start construction between April 16, 2024, and December 31, 2030, and are completed by December 31, 2035. This accelerated depreciation applies to projects that convert commercial properties into residential complexes or expand existing residential buildings that meet specific criteria under the EIFEL rules. However, it does not cover renovations to existing residential complexes.

    Additionally, these investments will benefit from the Accelerated Investment Incentive, which allows for immediate depreciation deductions for properties put into use before 2028. Starting in 2028, the regular depreciation rules, including the half-year rule, will apply.

    Accelerated Capital Cost Allowance (CCA)- Productivity-enhancing assets

    The budget introduces immediate expensing for newly acquired properties that become operational between April 16, 2024, and December 31, 2026. This applies to specific categories such as:

    • Class 44- Patents and rights to patented information

    • Class 46- Data network infrastructure and related software

    • Class 50- General electronic data-processing equipment and software

    Properties that are put into use between 2027 and 2028 will continue to benefit from the Accelerated Investment Incentive.

    To qualify for this accelerated depreciation, the property must not have been previously owned by the taxpayer or someone closely connected to them, and it must not have been received as part of a tax-deferred deal. Also, if a tax year is shorter, the depreciation will be adjusted accordingly and will not carry over to the next year.

    Canada Carbon Rebate for Small Businesses

    The budget introduces a Canada Carbon Rebate for small businesses, offering a new refundable tax credit automatically. To be eligible, a Canadian-controlled private corporation must:

    • File a tax return for its 2023 tax year by July 15, 2024, for the fuel charge years from 2019-20 to 2023-24. For subsequent fuel charge years, it must file a tax return for the tax year that ends within that fuel charge year.

    • Employ 499 or fewer people across Canada during the year that corresponds with the fuel charge year.

    The amount of the tax credit for each eligible business will depend on:

    • The province where the company had employees during the fuel charge year.

    • The number of employees in that province multiplied by a rate set by the Minister of Finance for that year.

    • The CRA will automatically calculate and issue the tax credit to qualifying businesses.

    We can help!

    Wondering how this year’s budget will impact your finances or your business? We can help – give us a call today!

    https://crossroadsfinancial.ca/wp-content/uploads/2024/04/Federal-Budget-2024-Highlights.jpg 300 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-04-17 17:41:352024-04-17 17:54:442024 Federal Budget Highlights

    TFSA vs RRSP – 2024

    February 1, 2024/in 2024, Blog, Business Owners, Estate Planning, Family, financial advice, Financial Planning, individuals, Investment, personal finances, Professionals, retirement, rrsp, Tax Free Savings Account/by Crossroads Financial Inc.

    Tax-Free Savings Account vs Registered Retirement Savings Plan

    When looking to save money in a tax-efficient manner, Tax-Free Savings Accounts (TFSA) and Registered Retirement Savings Plans (RRSP) can offer significant tax benefits. To assist you in understanding the distinctions, we will compare the following:

    • The differences in deposits between TFSAs and RRSPs

    • The differences in withdrawals between TFSAs and RRSPs

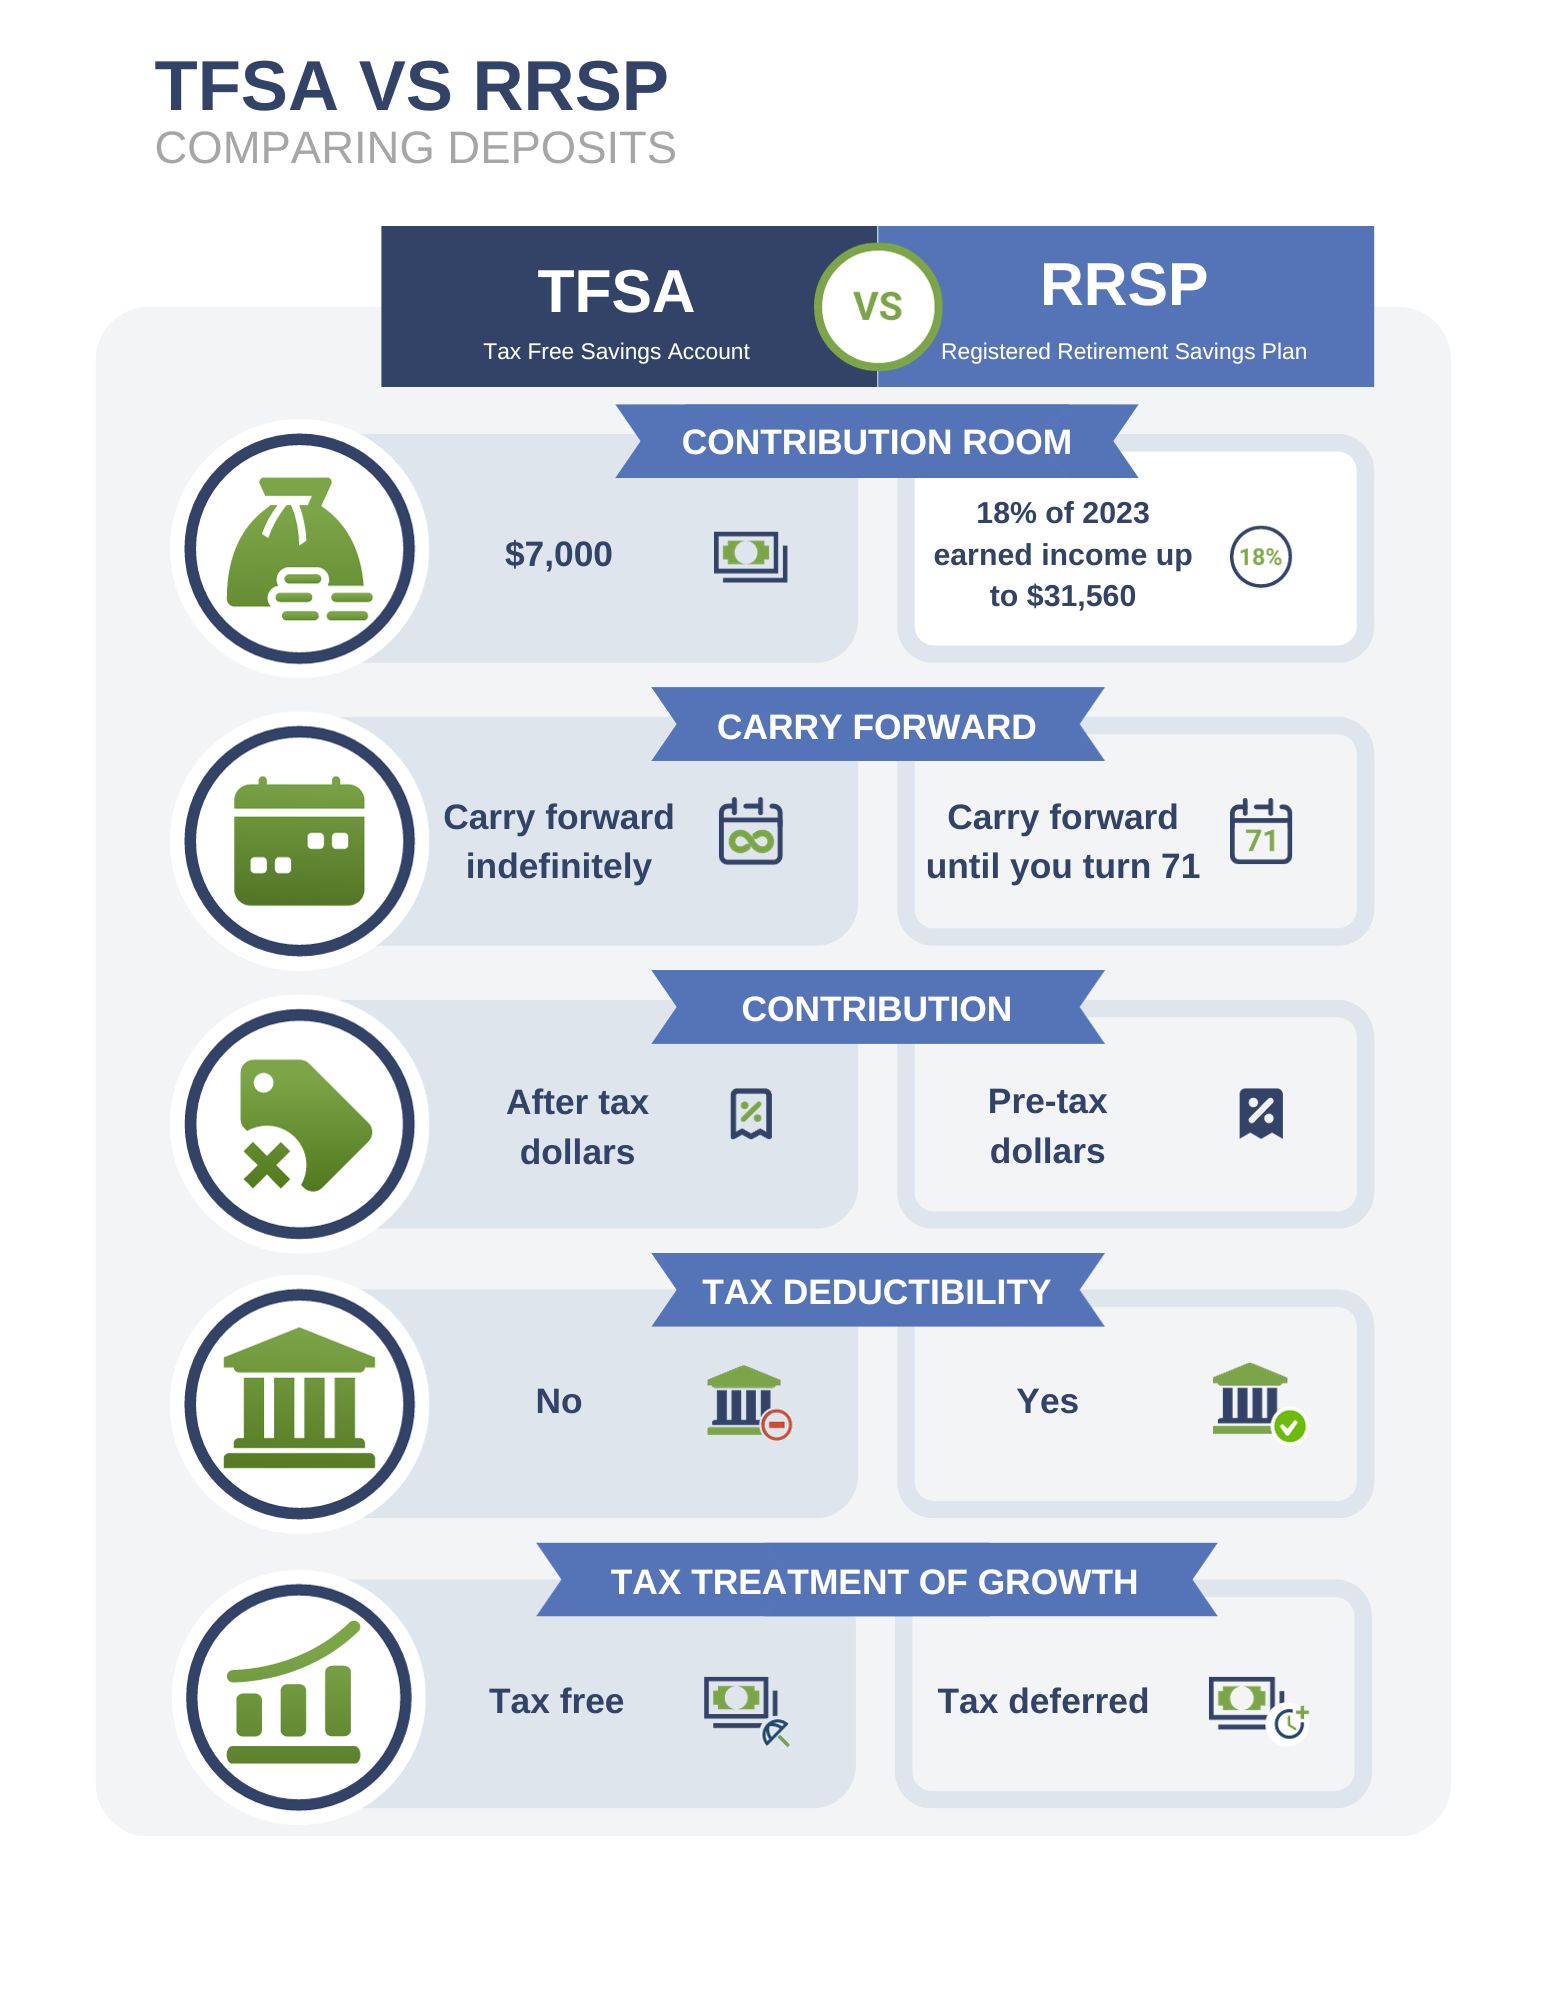
    TFSA versus RRSP – Difference in deposits 

    When comparing deposit differences between TFSAs and RRSPs, there are several key considerations: 

    • The amount of contribution room available

    • The ability to carry forward unused contributions

    • The tax deductibility of contributions

    • The tax treatment of growth in the account


    How much contribution room do I have? 

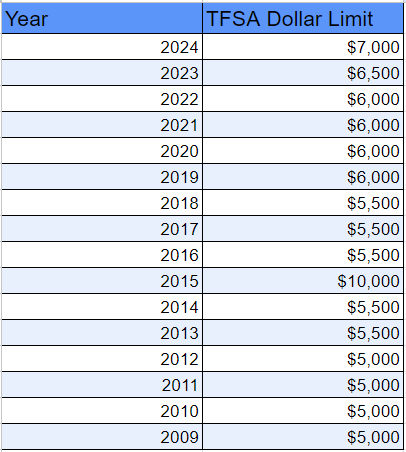
    If you have never contributed to a TFSA, you can contribute up to $95,000 today. This table outlines the contribution amount you are allowed each year since TFSAs were created, including this year:

    Regarding RRSPs, the limit for tax deductions is 18% of your pre-tax earned income from the previous year, with a maximum limit of $31,560. To illustrate, if your pre-tax income in 2023 was $60,000, your deduction limit for 2024 would be $10,800 (18% x $60,000). If your pre-tax income was $200,000, the maximum limit of $31,560 would apply. 

    How much contribution room can I carry forward? 

    Suppose you opt not to contribute to your TFSA each year or do not contribute the maximum amount. In that case, you can carry forward your unused contribution room indefinitely, provided you are a Canadian resident, over 18 years of age, and have a valid social insurance number. If you make a withdrawal, the amount withdrawn will be added to your annual contribution room for the next calendar year. 

    In contrast, for an RRSP, you can carry forward your unused contribution room until age 71. Once you reach 71, you are required to convert your RRSP into an RRIF. Withdrawals from an RRSP do not create additional contribution room.

    The tax deductibility of contributions

    Your TFSA contributions are not tax-deductible and are made with after-tax dollars. 

    Your RRSP contributions are tax-deductible and made with pre-tax dollars. 

    Tax Treatment of Growth 

    It is essential to contribute to both RRSP and TFSA because of the different tax treatment of the growth within them. 

    A TFSA is ideal for short-term goals, such as saving for a down payment on a house or a vacation, as its growth is entirely tax-free. When withdrawing from your TFSA, you will not have to pay any income tax on the amount withdrawn. On the other hand, the growth within an RRSP is tax-deferred. This means you will not pay taxes on your RRSP gains until age 71, at which point you convert the RRSP into an RRIF and start withdrawing money. 

    RRSPs are more suitable for long-term goals such as retirement because, in retirement, you will have a lower income and be in a lower tax bracket, resulting in less tax on your RRIF income.

    TFSA versus RRSP – Differences in withdrawals 

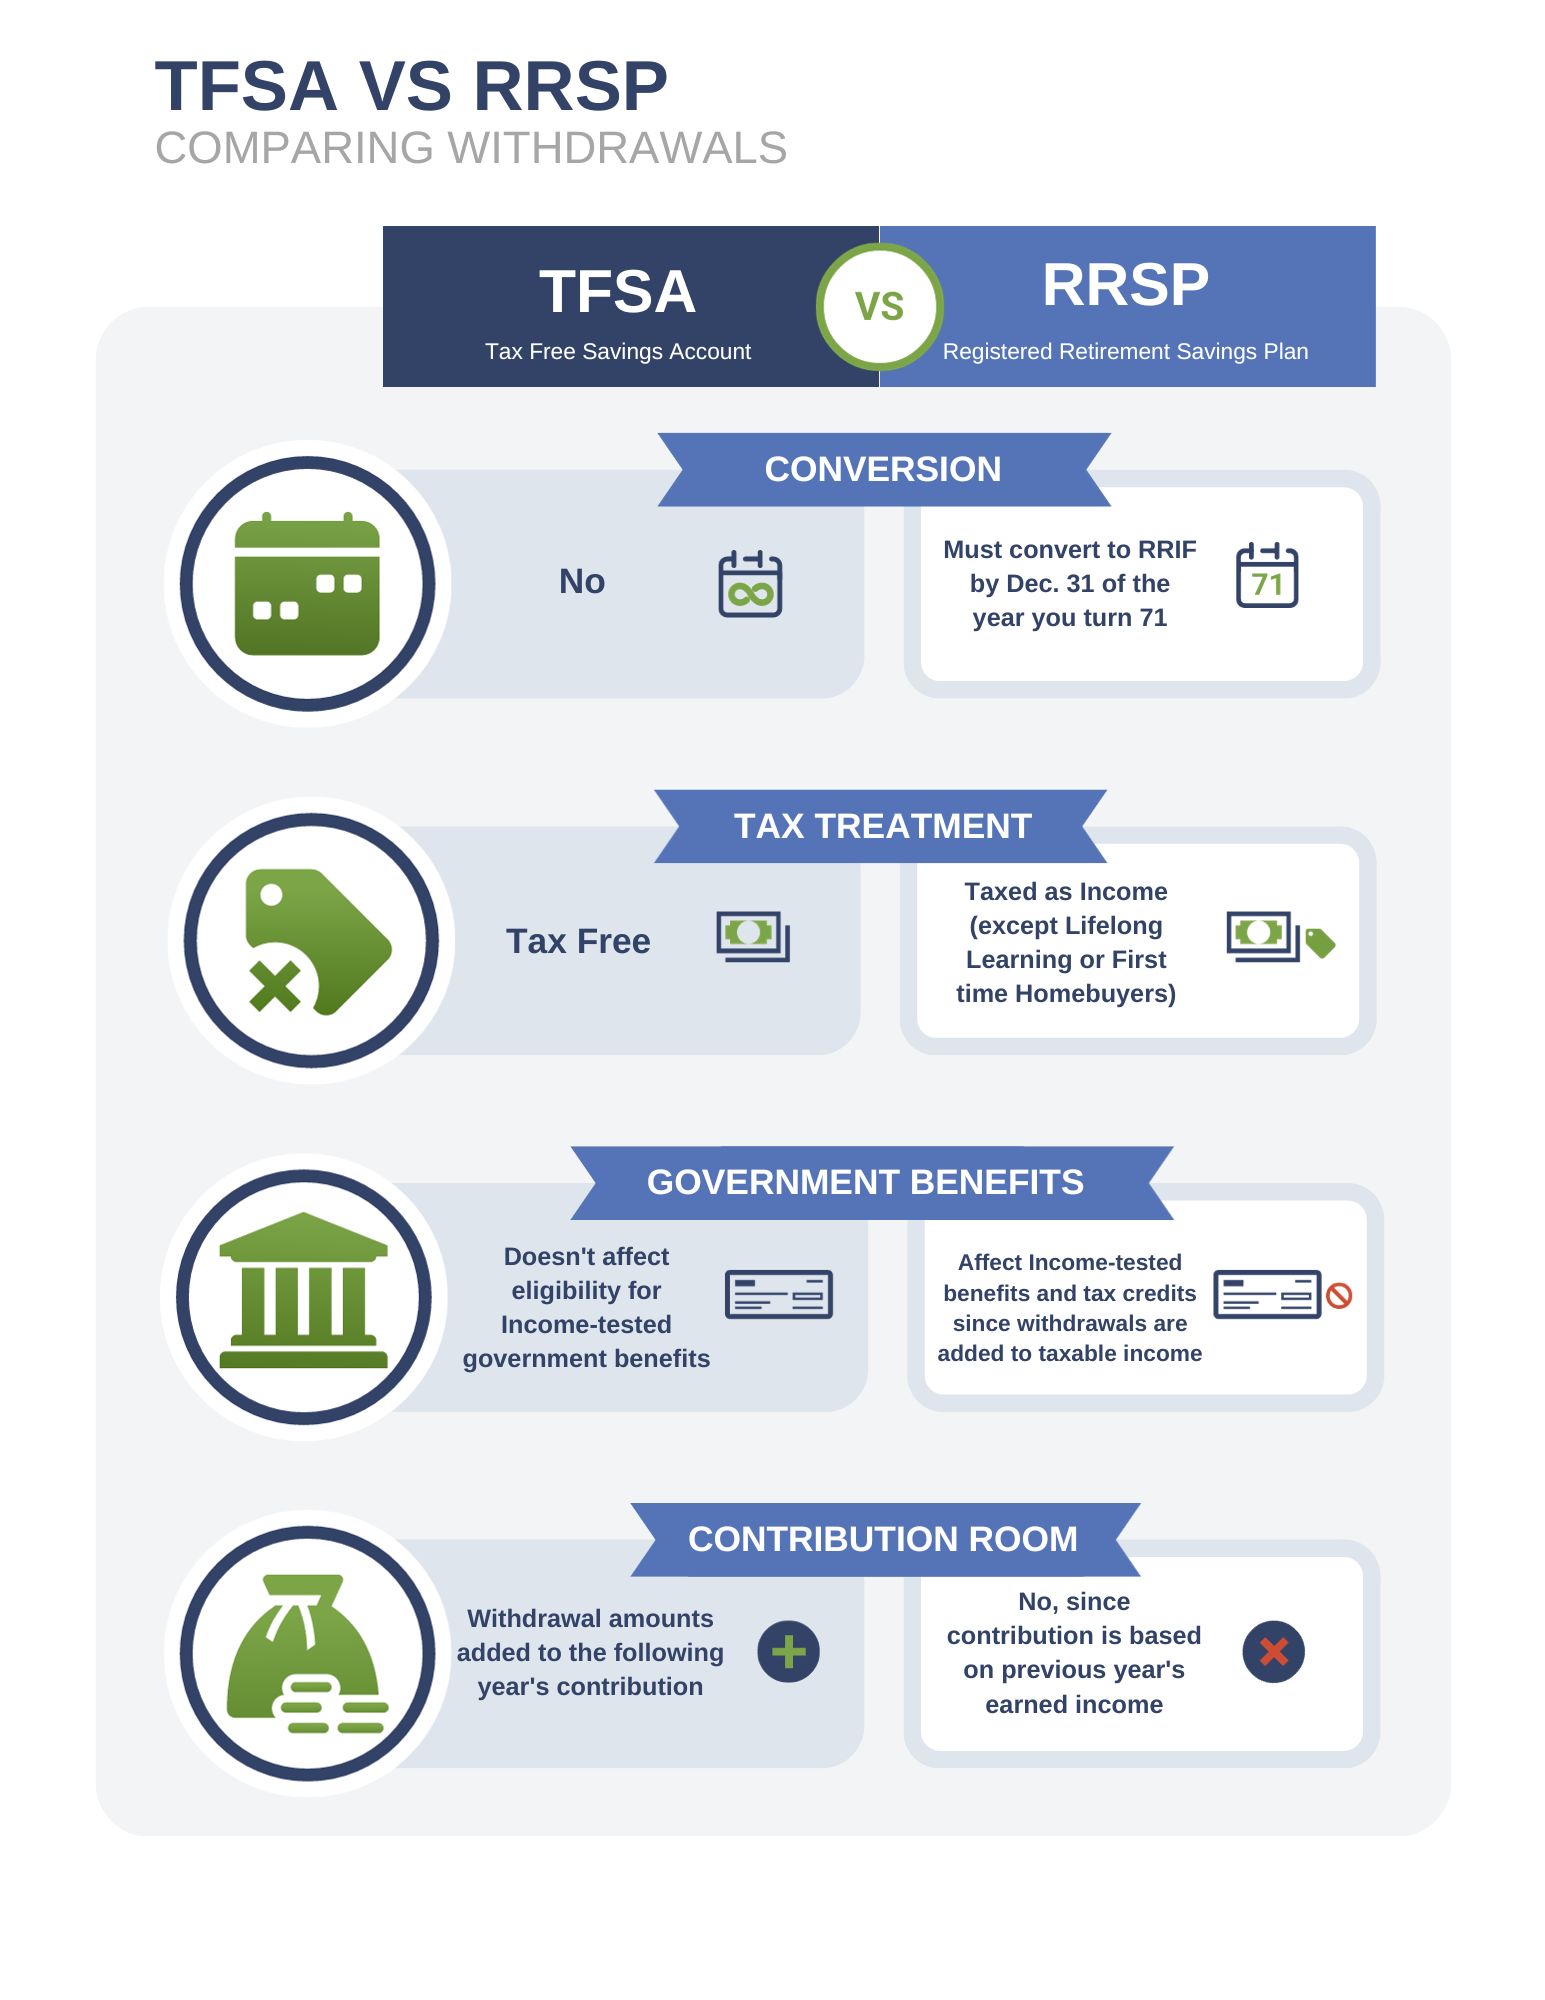
    There are several areas to focus on when comparing differences in withdrawal: 

    • Conversion Requirements 

    • Tax Treatment 

    • Government Benefits 

    • Contribution Room 

    Conversion Requirements 

    For a TFSA, there are never any conversion requirements as there is no maximum age for a TFSA. 

    For an RRSP, you must convert it to a Registered Retirement Income Fund (RRIF) if you turn 71 by December 31st, 2024. 

    Tax Treatment of Withdrawals 

    One of the most attractive things about a TFSA is that all your withdrawals are tax-free! Therefore, they are recommended for short-term goals; you don’t have to worry about taxes when you take money out to pay for a house or a dream vacation. 

    With an RRSP, if you make a withdrawal, it will be taxed as income except in two cases: 

    • The Home Buyers Plan lets you withdraw up to $35,000 tax-free, but you must pay it back within fifteen years. 

    • The Lifelong Learning Plan lets you withdraw up to $20,000 ($10,000 maximum per year) tax-free, but you must pay it back within ten years. 

    How will my government benefits be impacted? 

    If you are withdrawing from your TFSA or RRSP, it’s essential to know how that will affect any benefits you receive from the government. 

    Since TFSA withdrawals are not considered taxable income, they will not impact your eligibility for income-tested government benefits. 

    RRSP withdrawals are considered taxable income and can affect the following: 

    • Income-tested tax credits such as Canada Child Tax Benefit, the Working Income Tax Benefit, the Goods and Services Tax Credit, and the Age Credit. 

    • Government benefits including Old Age Security, Guaranteed Income Supplement and Employment Insurance. 

    How will a withdrawal impact my contribution room? 

    If you withdraw from your TFSA, the amount you withdrew will be added on top of your annual contribution room for the following calendar year. If you withdraw from your RRSP, you do not open any additional contribution room. 

    The Takeaway 

    RRSPs and TFSAs can both be great savings vehicles. However, there are significant differences between them which can affect your finances. If you need help navigating these differences, please do not hesitate to contact us. We’re here to help.

    https://crossroadsfinancial.ca/wp-content/uploads/2024/02/TFSA-vs-RRSP-2024.png 300 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-02-01 10:20:162024-02-01 11:09:56TFSA vs RRSP – 2024

    2024 Financial Calendar

    January 1, 2024/in 2024, Blog, Business Owners, financial advice, Financial Planning, individuals, personal finances, Professional Corporations, Professionals, Retirees, tax/by Crossroads Financial Inc.

    2024 Financial Calendar

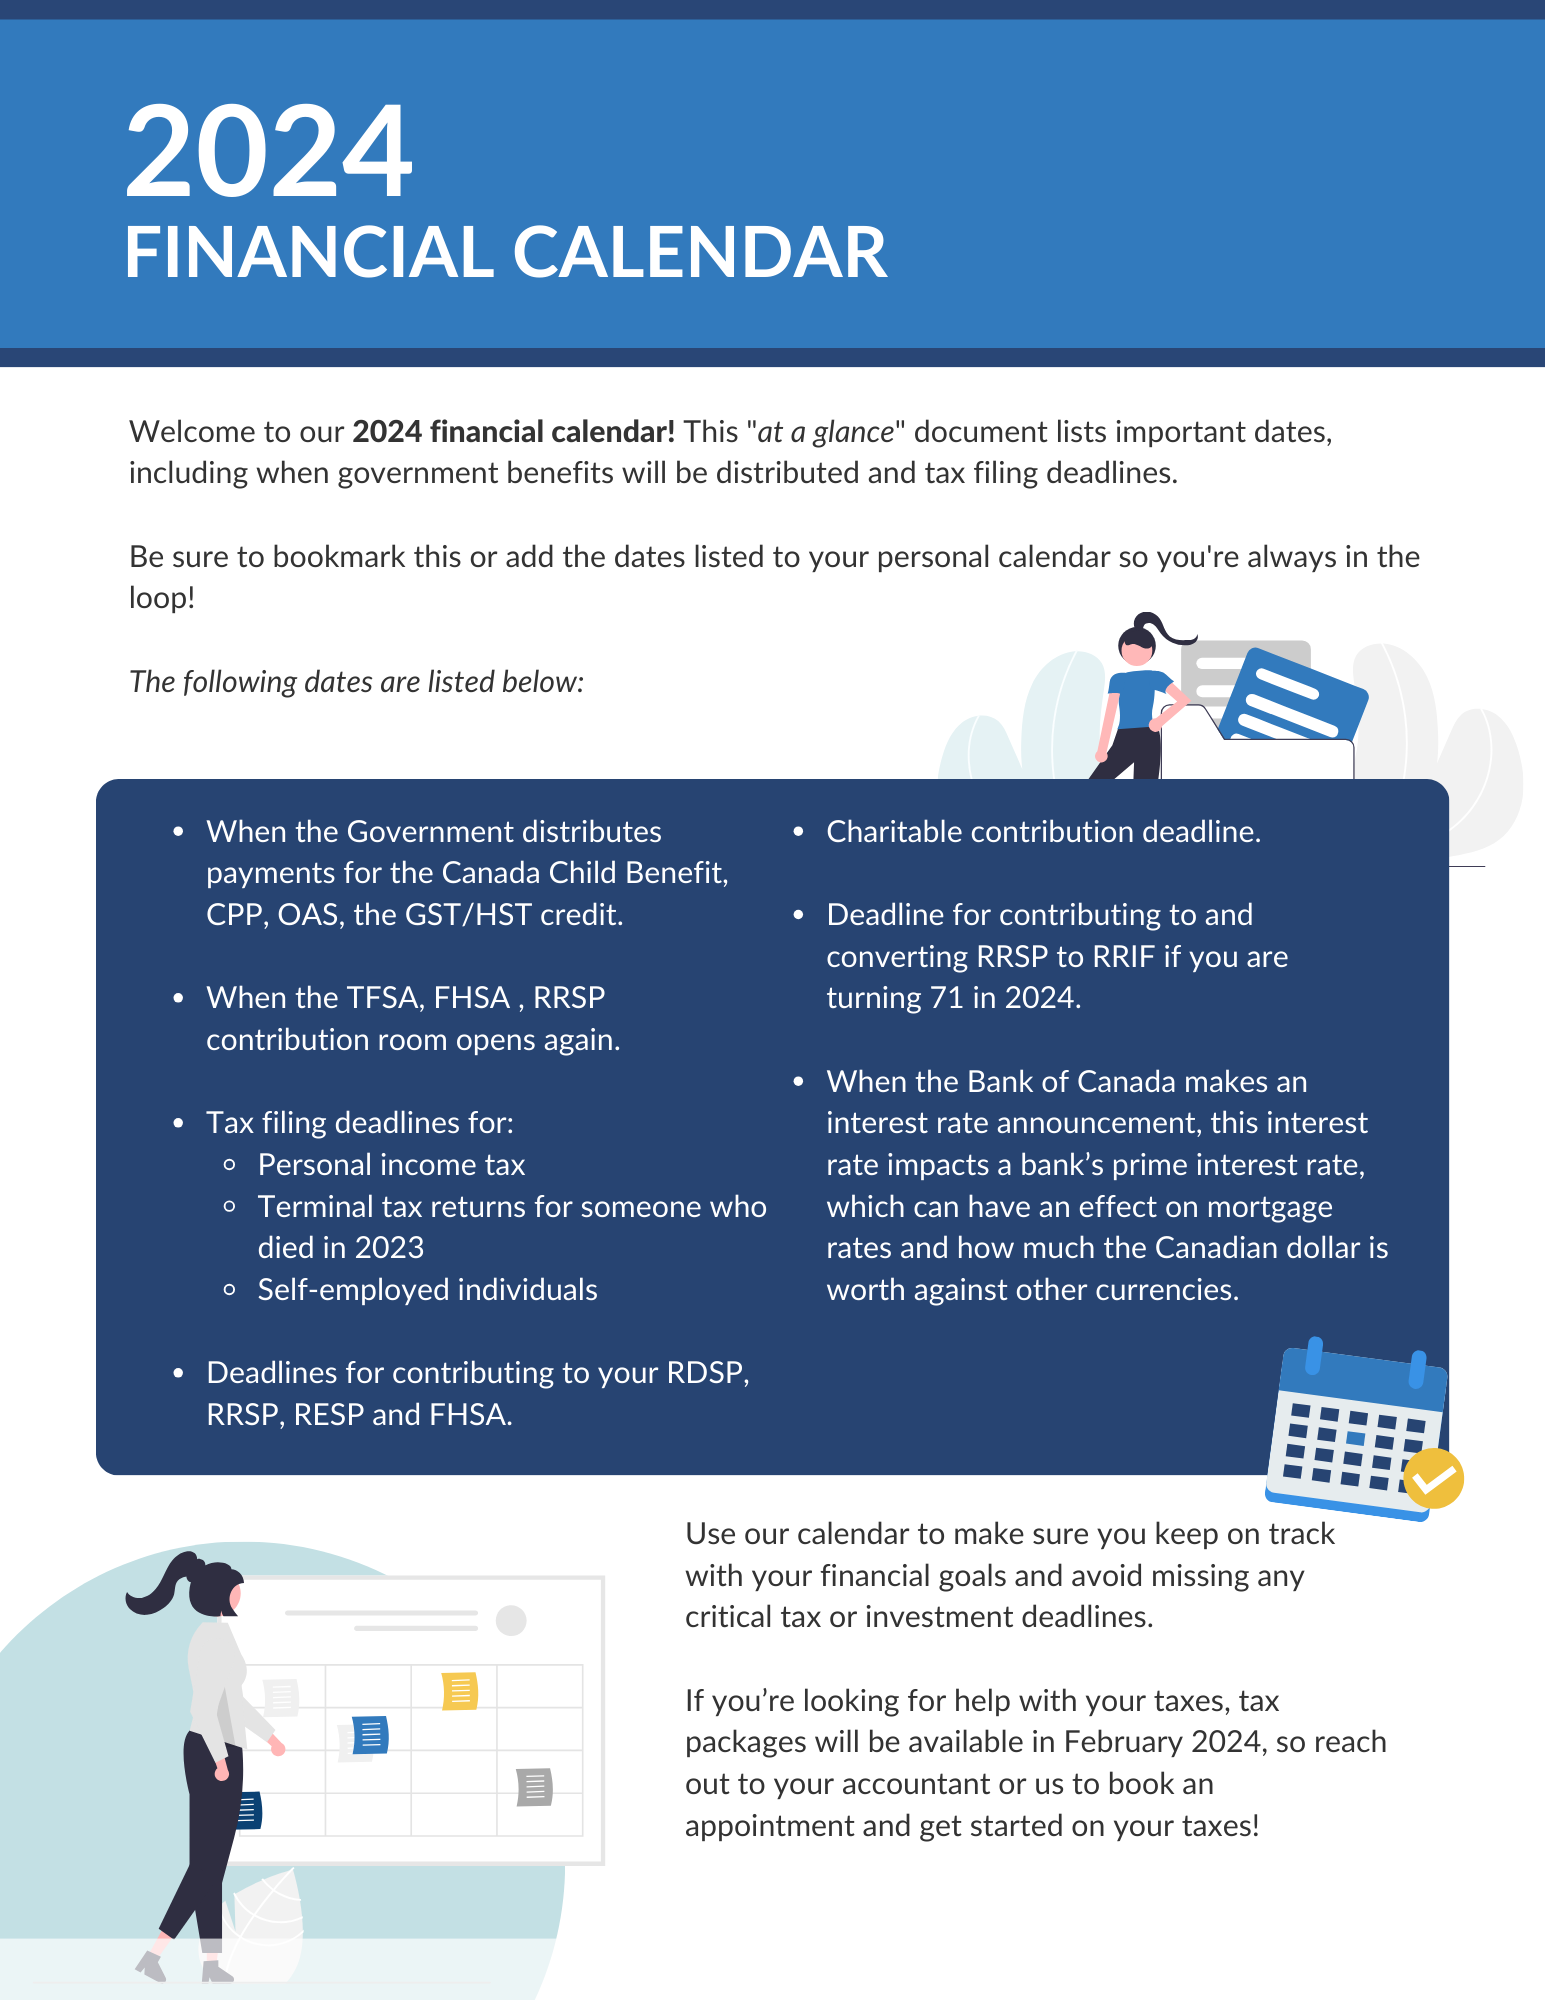
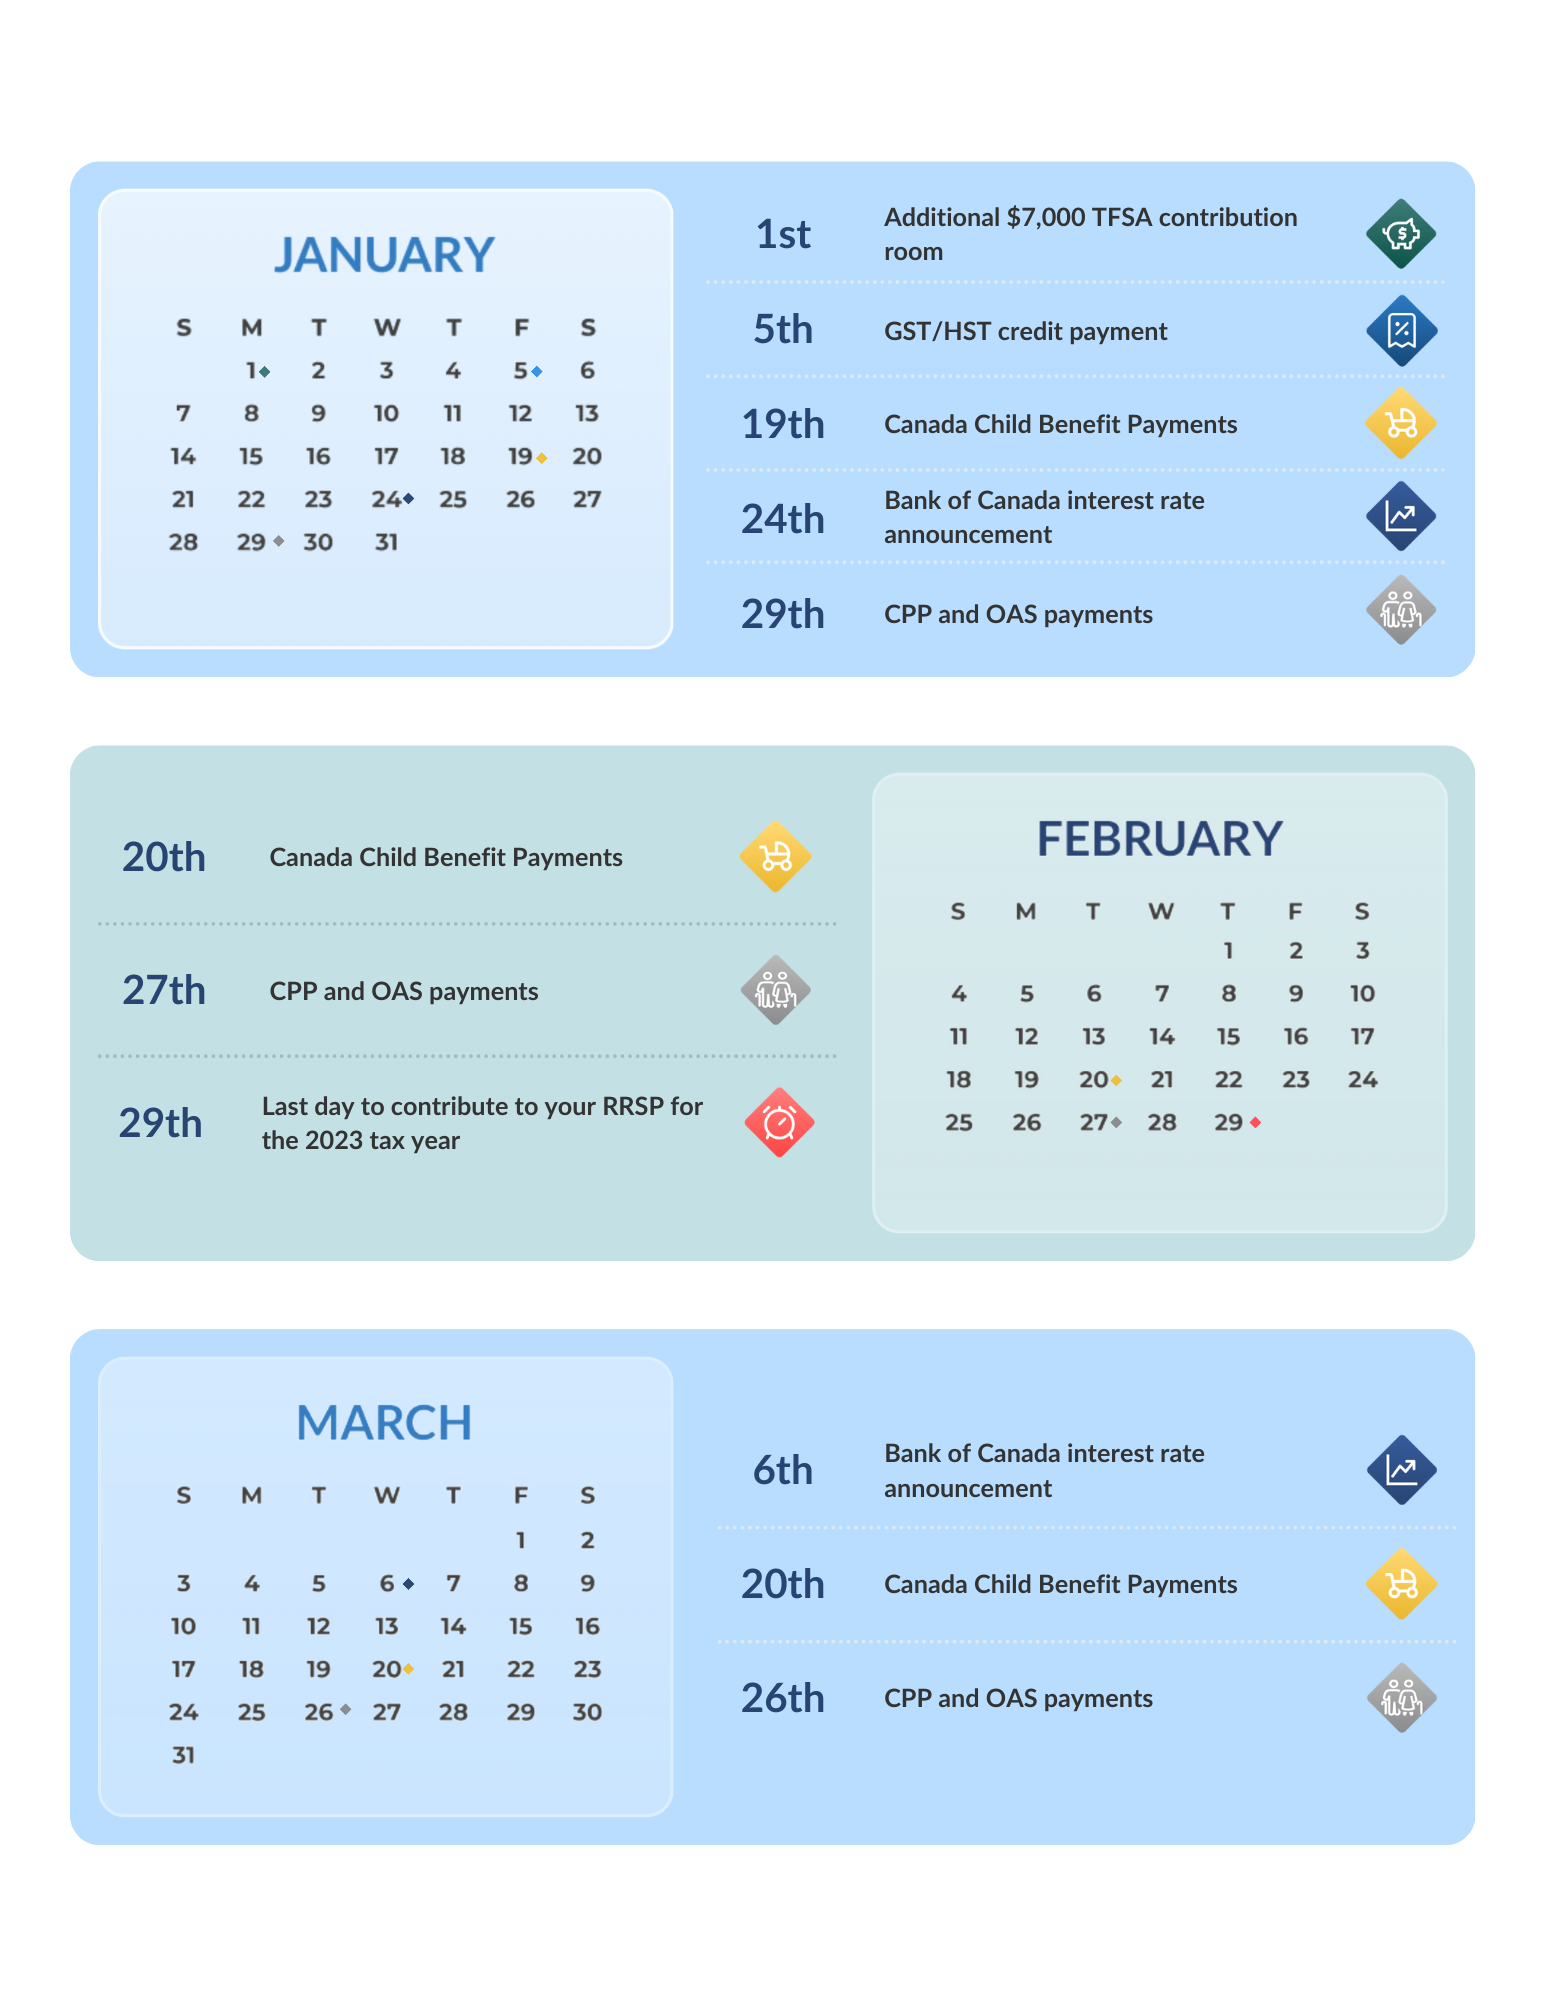
    Welcome to our 2024 financial calendar! This calendar is designed to help you keep track of important financial dates and deadlines, such as tax filing and government benefit distribution. You can bookmark this page for easy reference or add these dates to your personal calendar to ensure you don’t miss any important financial obligations.

    If you need help with your taxes, tax packages will be available starting February 2024. Don’t wait until the last minute to get started on your tax return – make an appointment with your accountant to ensure you’re ready to go when tax season arrives.

    Important 2024 Dates to Know

    On January 1, 2024 the contribution room for your Tax Free Savings Account opens again. The maximum contribution for 2024 is $7,000.

    If you qualify, on January 1, 2024 the contribution room for your First Home Savings Account opens. The maximum contribution for 2024 is $8,000. 

    For your Registered Retirement Savings Plan contributions to be eligible for the 2023 tax year, you must make them by February 29, 2024.

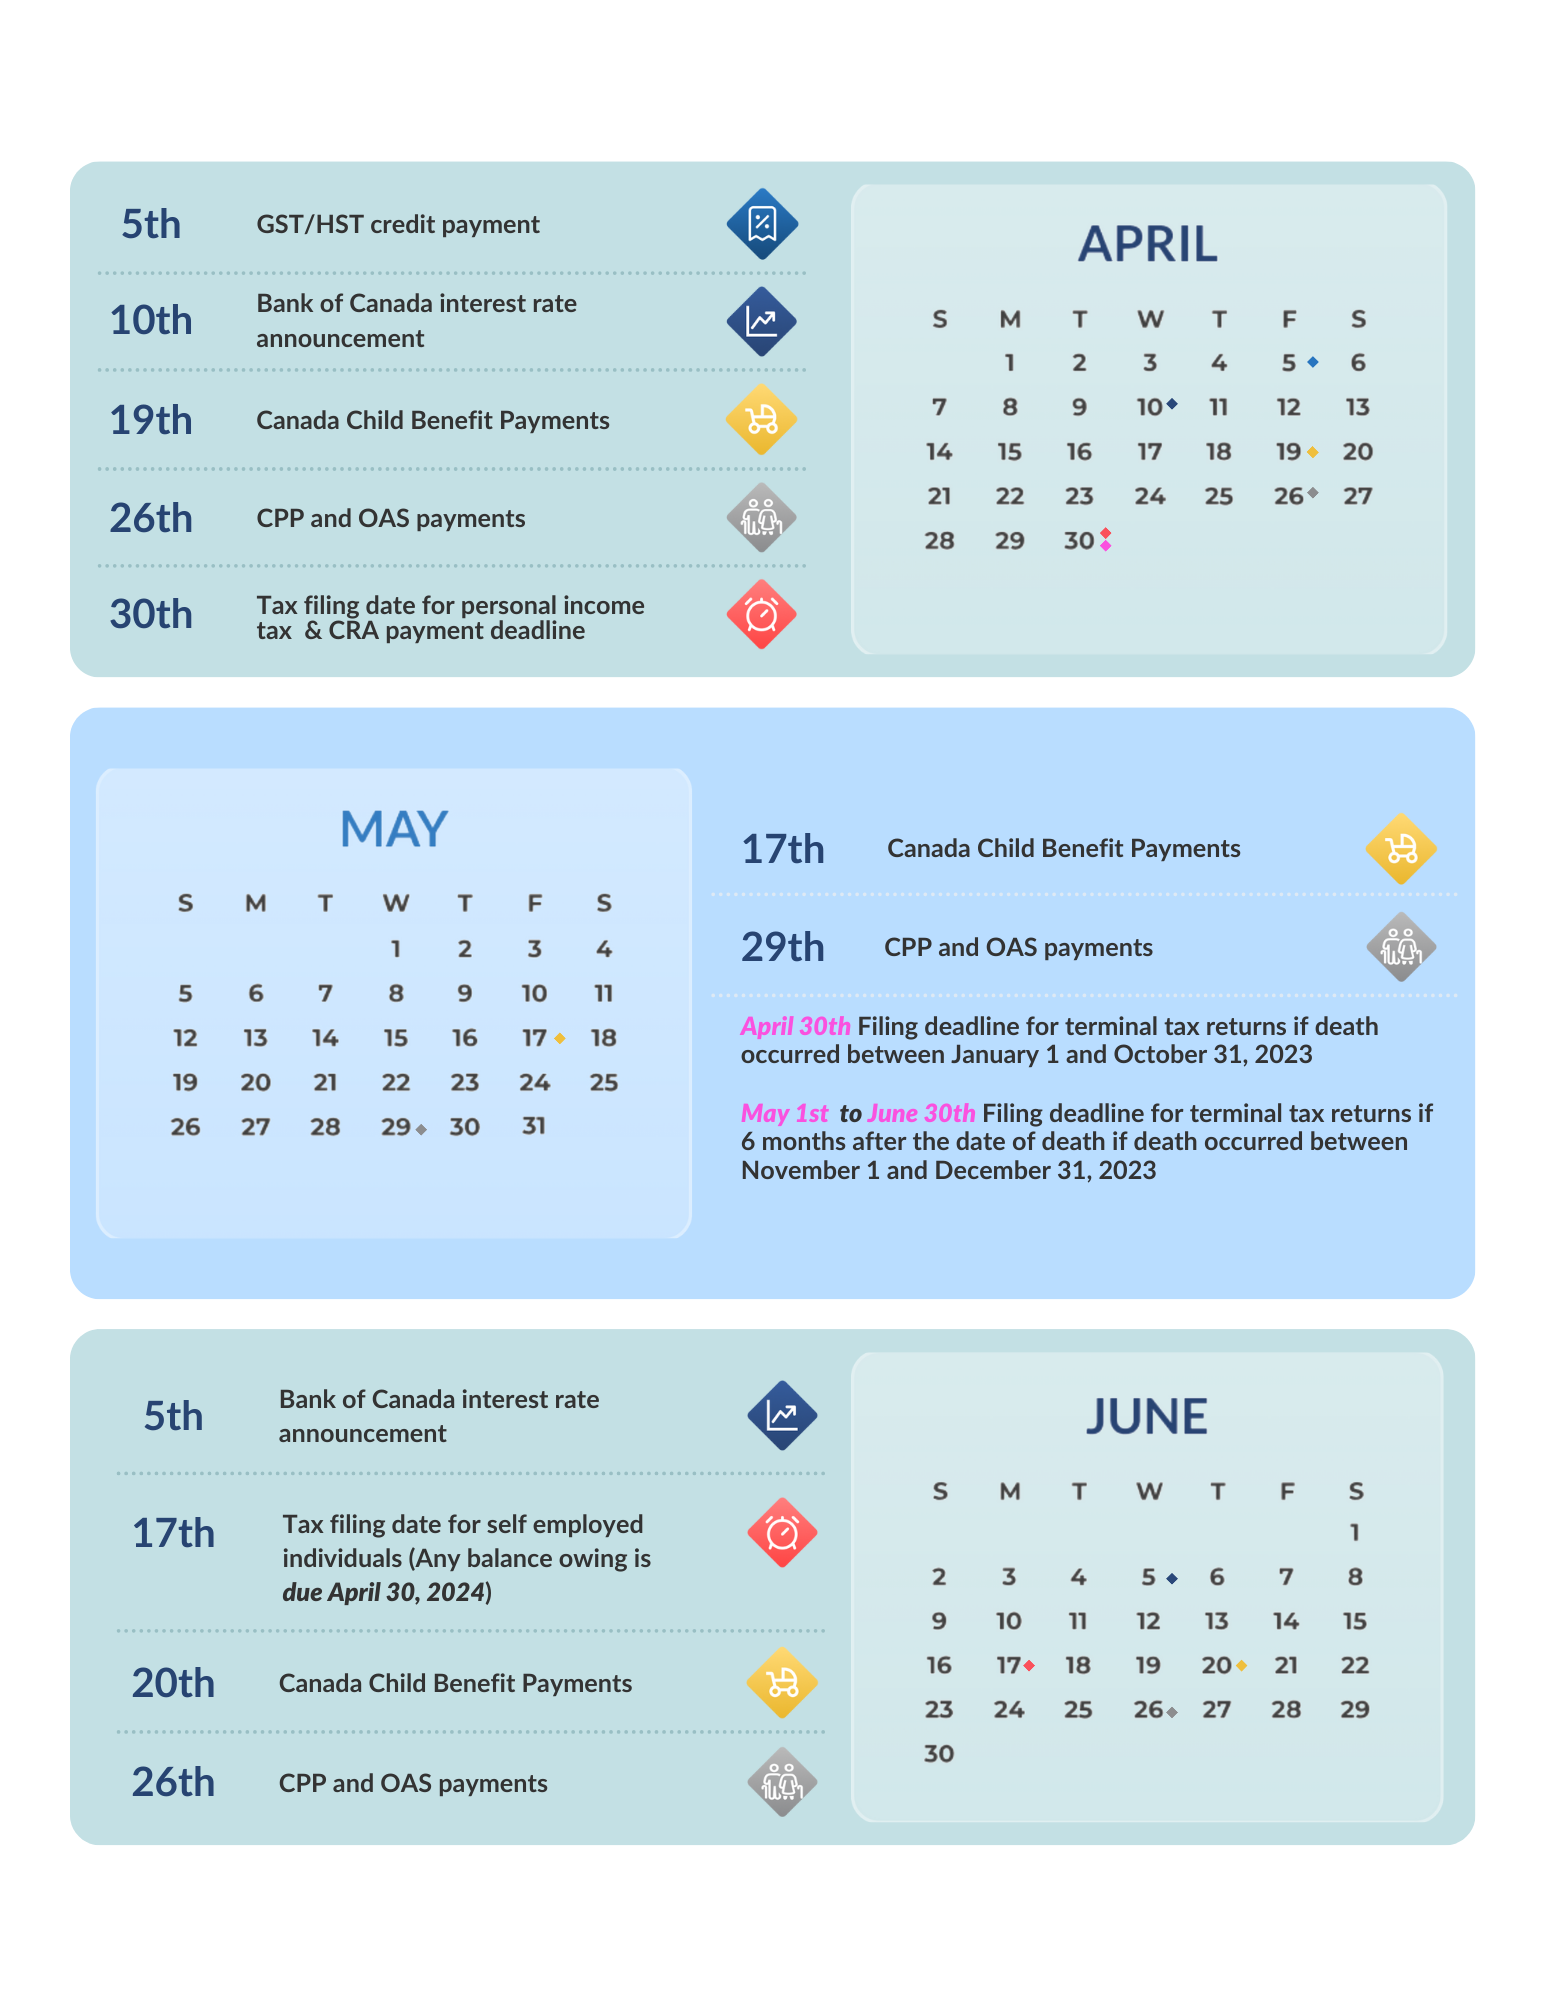
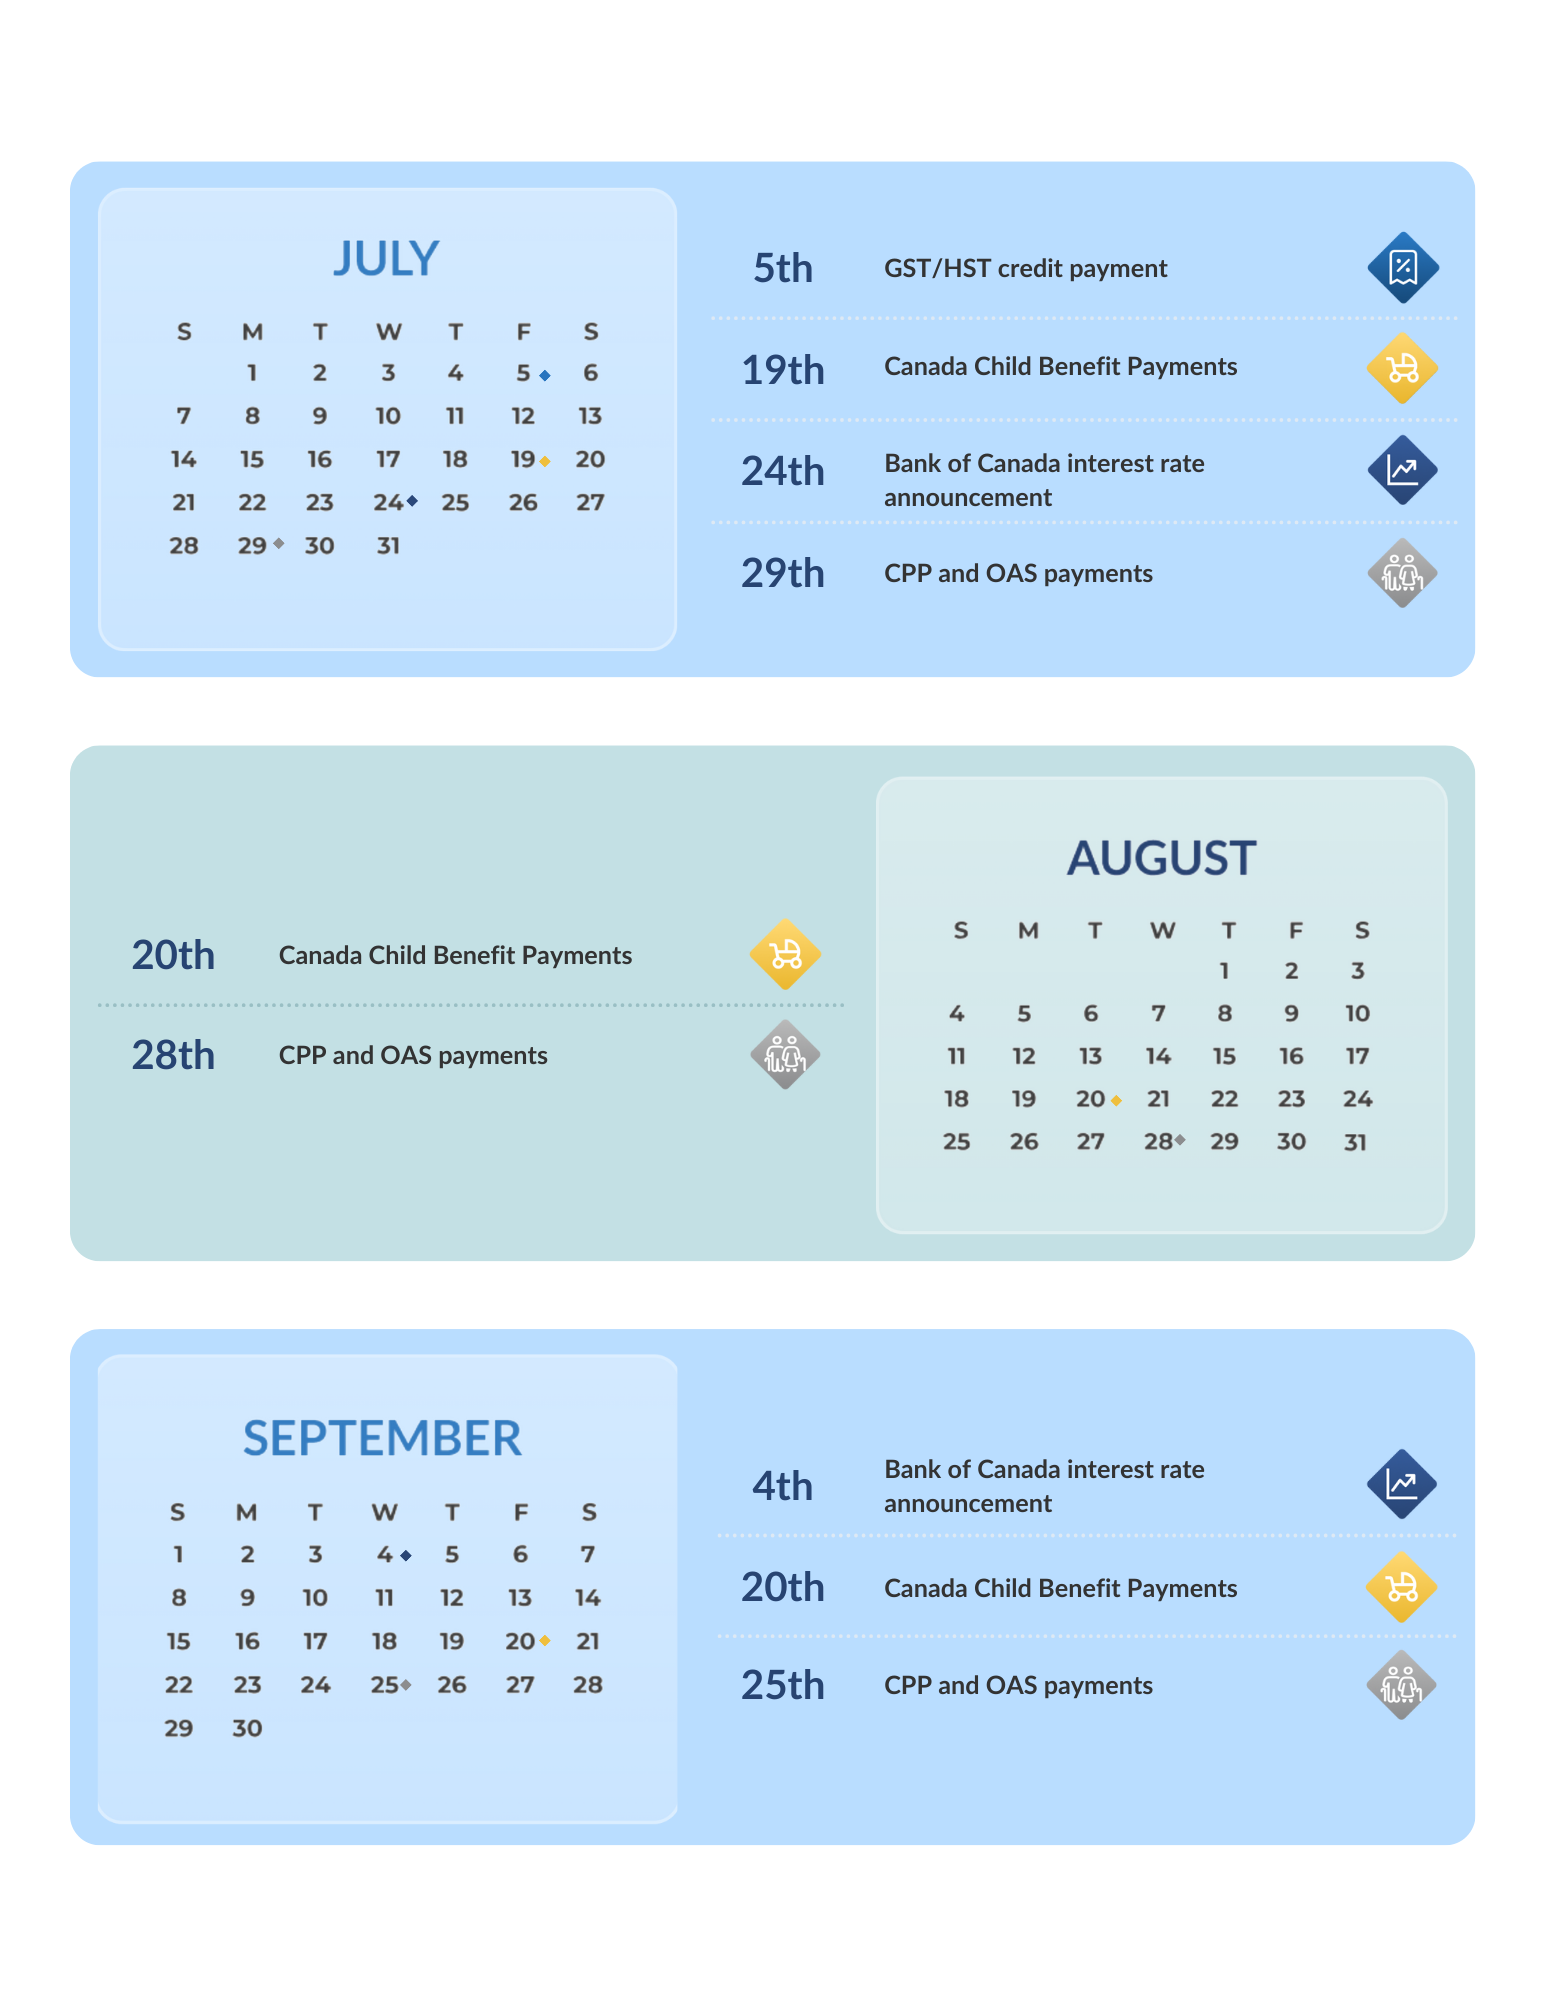
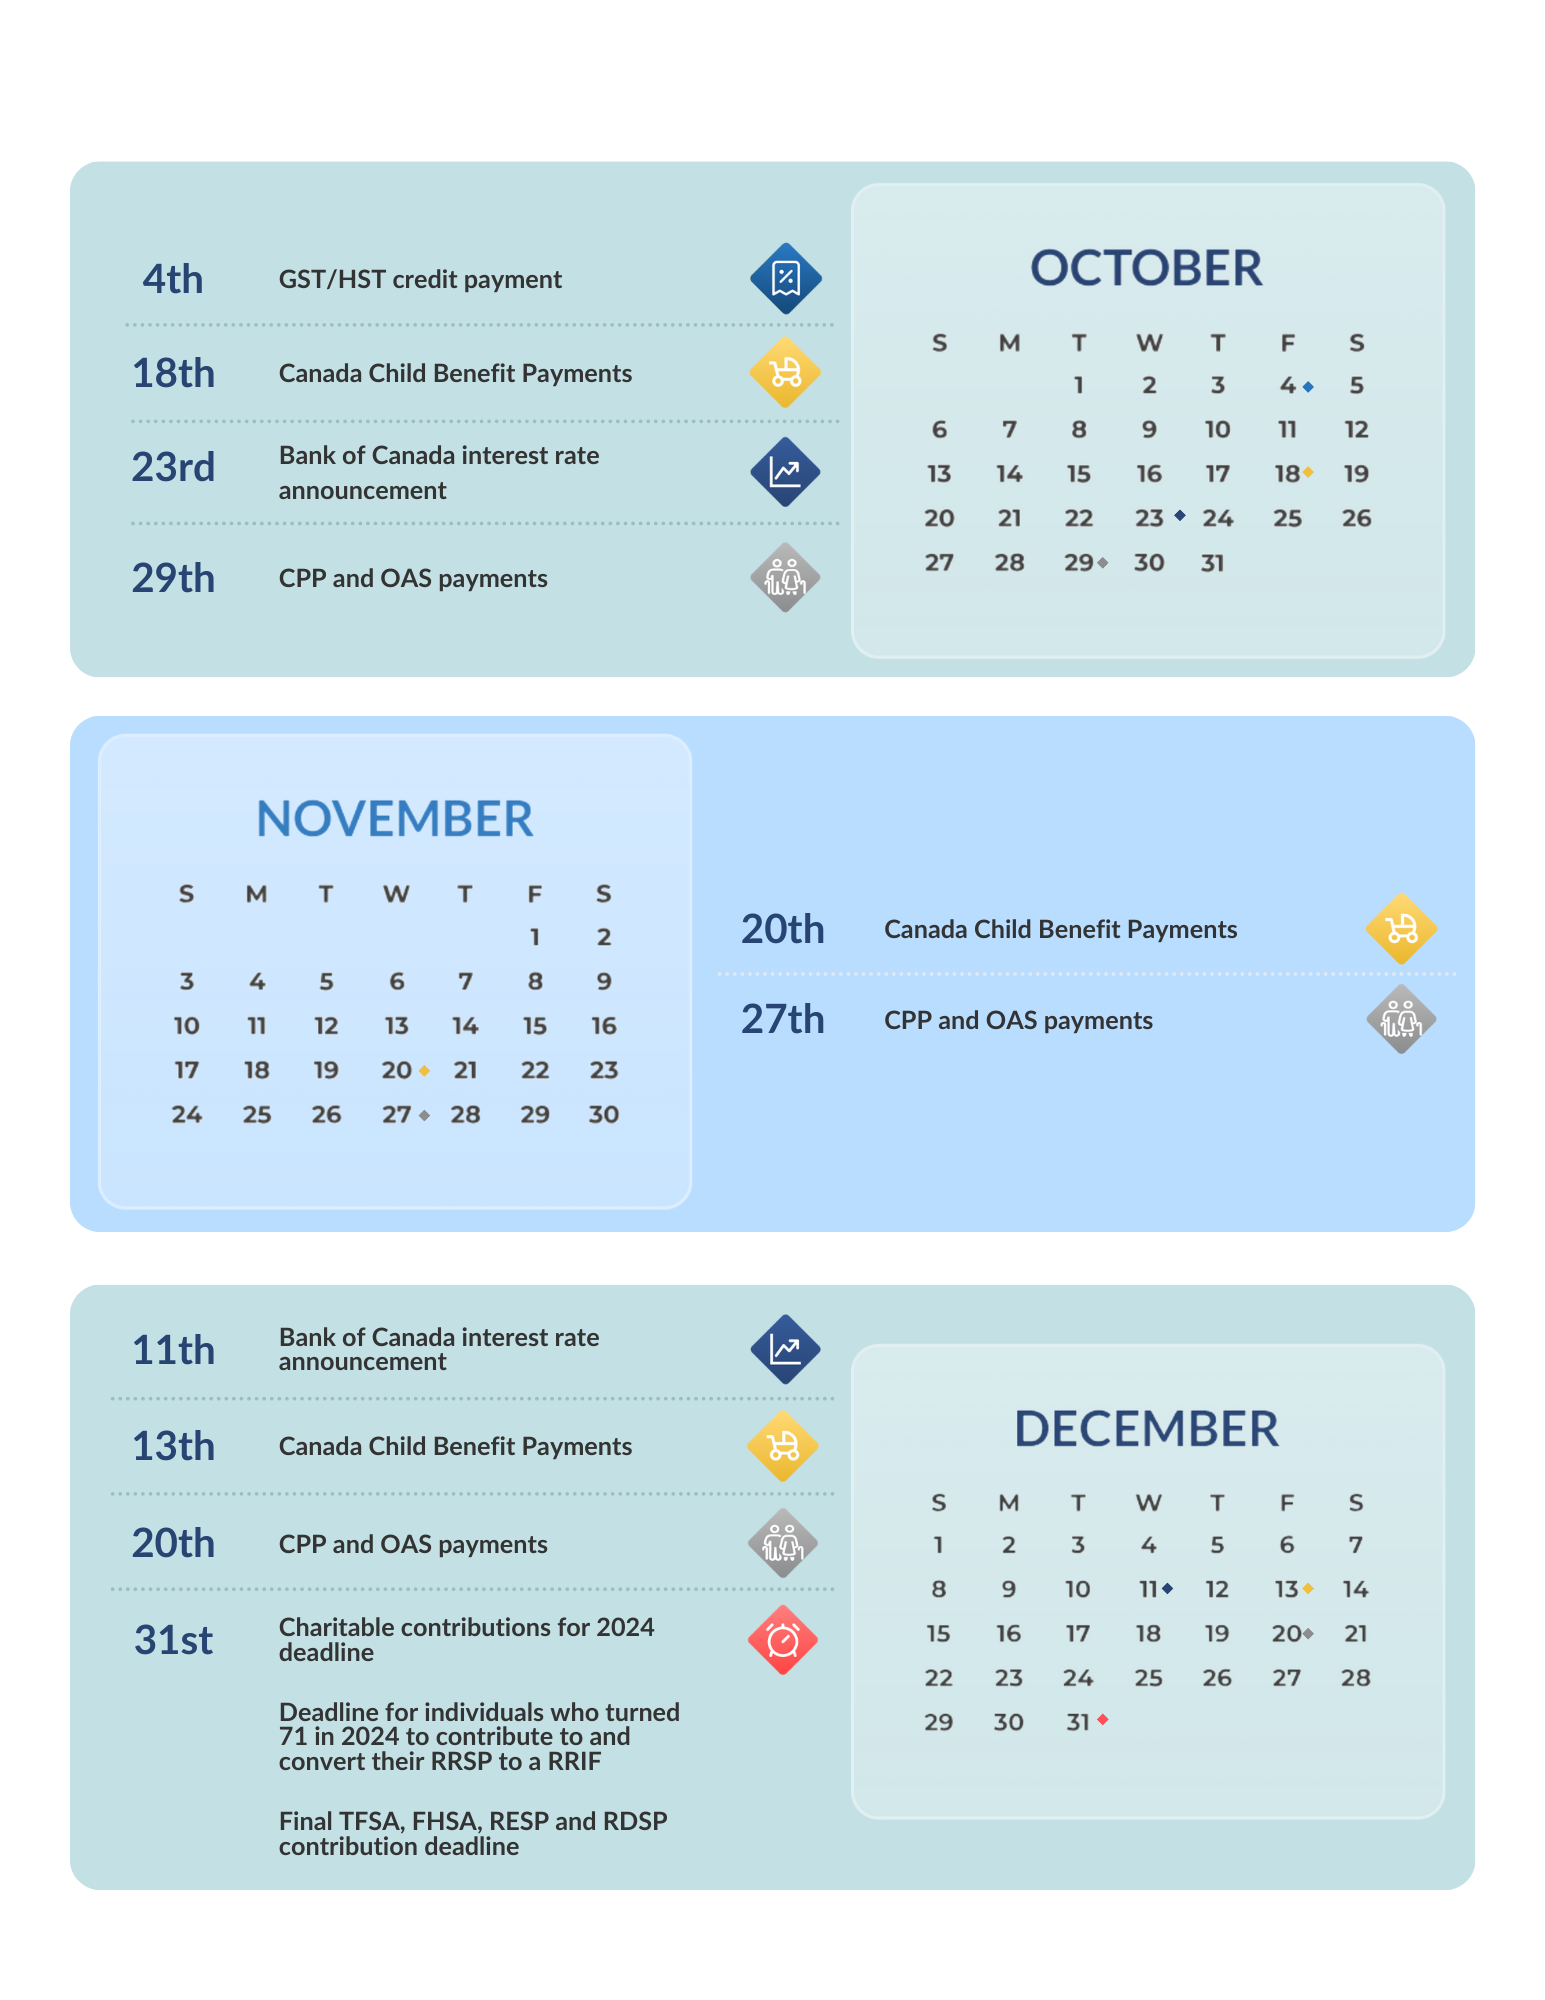
    GST/HST credit payments will be issued on:  

    • January 5

    • April 5

    • July 5

    • October 4

    Canada Child Benefit payments will be issued on the following dates: 

    • January 19

    • February 20

    • March 20

    • April 19

    • May 17

    • June 20

    • July 19

    • August 20

    • September 20

    • October 18

    • November 20

    • December 13

    The government will issue Canada Pension Plan and Old Age Security payments on the following dates: 

    • January 29

    • February 27

    • March 26

    • April 26

    • May 29

    • June 26

    • July 29

    • August 28

    • September 25

    • October 29

    • November 27

    • December 20

    The Bank of Canada will make interest rate announcements on:

    • January 24

    • March 6

    • April 10

    • June 5

    • July 24

    • September 4

    • October 23

    • December 11

    April 30, 2024 is the last day to file your personal income taxes, and tax payments are due by this date. This is also the filing deadline for final returns if death occurred between January 1 and October 31, 2023.

    May 1 to June 30, 2024 would be the filing deadline for final tax returns if death occurred between November 1 and December 31, 2023. The due date for the final return is six months after the date of death.

    The tax deadline for all self-employment returns is June 17, 2024. Payments are due April 30, 2024. 

    The final Tax-Free Savings Account, First Home Savings Account, Registered Education Savings Plan and Registered Disability Savings Plan contributions deadline is December 31.

    December 31 is also the deadline for 2024 charitable contributions.

    December 31 is also the deadline for individuals who turned 71 in 2024 to finish contributing to their RRSPs and convert them into RRIFs.

    Please reach out if you have any questions. 

    Sources: 

    https://www.canada.ca/en/services/benefits/calendar.html

    https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/important-dates-rrsp-rrif-rdsp.html

    https://www.bankofcanada.ca/2023/07/2024-schedule-policy-interest-rate-announcements-major-publications/

    https://crossroadsfinancial.ca/wp-content/uploads/2024/01/2024-Financial-Calendar.jpg 350 500 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2024-01-01 09:00:002024-01-01 09:07:412024 Financial Calendar

    Book a Meeting

    Search Blog Posts

    Search Search

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    Categories

    • 2020
    • 2020 Only
    • 2021
    • 2022
    • 2022 Only
    • 2023
    • 2024
    • 2025
    • 2026
    • Accountants
    • Blog
    • Budget
    • Business Owners
    • business owners
    • buy sell
    • Center of Influences
    • Charitable Gifting
    • Coronavirus
    • Coronavirus – Associates
    • Coronavirus – Practice Owners
    • Coronavirus – Practice Owners
    • Coronavirus – Retired
    • Coronavirus – Retiring
    • Coronavirus – Students
    • corporate
    • critical illness insurance
    • Debt
    • dental benefits
    • disability
    • disability insurance
    • Estate Planning
    • Family
    • farmers
    • financial advice
    • Financial Planning
    • Government Budget
    • Group Benefits
    • health benefits
    • incorporated professionals
    • individuals
    • Insurance
    • Investment
    • life insurance
    • long term care
    • mortgage
    • Ontario Only
    • pension plan
    • personal finances
    • Professional Corporations
    • Professionals
    • rdsp
    • Registered Education Savings Plan
    • Retirees
    • retirement
    • rrsp
    • tax
    • Tax Free Savings Account
    • travel insurance

    Get in Touch

    Crossroads Financial Solutions Inc.
    Tel: (905) 361- 6500
    Email: connect@crossroadsfinancial.ca
    TF: 1-877-607-6237

    4255 Sherwoodtowne Blvd, Suite 102
    Mississauga, Ontario
    L4Z 1Y5

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    About

    Everyone has their own dreams. Protecting those goals is our mission. We believe there is no “One Size Fits All” when it come to planning your insurance needs and investment goals.
    We encourage you to have a discovery meeting with us.

    ©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
      Scroll to top Scroll to top Scroll to top