Crossroads Insurance & Investments
  • HOME
  • SERVICES
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING FOR YOUNG FAMILIES
      • ESTATE PLANNING FOR RETIREES & MATURE FAMILIES
      • CHARITABLE GIVING
      • MANULIFE ONE
    • NEW IMMIGRANTS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
      • SUCCESSION PLANNING
      • GROUP BENEFITS
        • HEALTH BENEFITS
        • RETIREMENT BENEFITS
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
    • INSURANCE
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • MORTGAGE LIFE INSURANCE
      • LONG TERM CARE
      • CROSS BORDER INSURANCE
    • INVESTMENT
      • REGISTERED EDUCATION SAVINGS PLAN
      • TAX FREE SAVINGS ACCOUNT
      • REGISTERED RETIREMENT SAVINGS PLAN
      • REGISTERED RETIREMENT INCOME FUND
      • ANNUITIES
  • ABOUT
    • ABOUT
    • PROCESS
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
    • CALCULATORS
  • CONTACT
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

    Archive for category: 2026

    Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?

    July 15, 2026/in 2026, Blog, Group Benefits/by Crossroads Financial Inc.

    Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?

    If drug costs have been climbing on your group benefits plan, GLP-1 medications like Ozempic are likely part of the reason. These drugs have been among the fastest-growing cost drivers in employer-sponsored plans across the country. So when Health Canada approved a generic version of semaglutide, the active ingredient in Ozempic, on April 28, 2026, and a second generic followed in early May, it was welcome news for anyone managing a group drug plan. Canada was the first G7 country to approve a generic semaglutide.

    But here is the thing: lower costs are not guaranteed just because a cheaper version of the drug exists. Whether your plan actually sees savings depends almost entirely on how it is designed.

    What Happens When a Drug Goes Generic?

    When a brand-name drug loses patent protection, other manufacturers can produce and sell equivalent versions at a lower cost. The savings can be significant.

    As a rule of thumb in the industry, when one or two generics enter the market, prices may fall by 20 to 30 per cent below the brand-name drug. With more generics competing over time, those discounts can deepen further. These are general industry estimates, and actual outcomes will vary.

    For Ozempic specifically, this could translate to roughly one to two per cent savings on a plan’s total drug costs. That may sound modest, but for organizations with meaningful Ozempic spend, it adds up quickly, especially at renewal.

    Why Savings Do Not Happen Automatically

    Here is where many plan sponsors get caught off guard: the existence of a generic does not mean your plan will automatically pay for it at the lower price.

    Without specific plan design provisions in place, many members may stay on the brand-name drug. Their doctor prescribed it. They have been taking it. They may not even know a generic exists. And if your plan covers it without any substitution requirement, there is little reason to switch.

    The result is a plan that may continue paying brand-name prices for a drug that now has a lower-cost equivalent on the market.

    What Plan Sponsors Can Do Right Now

    The arrival of generic Ozempic creates a real window to act, but it requires a conversation with us. Here are the three areas worth reviewing:

    Generic substitution policies. Many plans already have mandatory substitution clauses that require members to use a generic when one is available, unless there is a medical reason not to. If your plan does not have this in place, or if it only applies to certain drug categories, now is the time to review it. Adding generic substitution for GLP-1 medications could meaningfully reduce what the plan pays.

    Prior authorization requirements. Prior authorization means a member needs approval before the plan will cover a specific drug. This is particularly useful for high-cost medications where clinical criteria should be confirmed before coverage is granted. It also creates a natural point to direct members to the generic option. If your plan does not currently require prior authorization for GLP-1 medications, that is worth exploring with your insurer.

    Brand-name pricing negotiations. In some cases, insurers may be able to negotiate pricing directly with brand-name drug manufacturers. This is not a standard plan-design feature, but it is worth asking your insurer whether it is an option and whether brand-name semaglutide pricing is available through their arrangements. If it is available, it could help reduce costs even for members who remain on the brand-name drug for medical reasons.

    The Bigger Picture on Plan Design

    Generic Ozempic is a useful reminder that drug plan management is not a set-it-and-forget-it exercise. Small design decisions, like whether a plan has a substitution clause or a prior authorization requirement for high-cost drugs, can translate into real, measurable differences in cost over time.

    For organizations that have seen drug costs climb in recent years, this is a meaningful opportunity. The savings potential is real. Whether your plan captures it depends on reviewing your plan design and having a conversation with us before your next renewal.

    This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

    Sources:

    • Generic Ozempic could trim employer drug costs, but savings depend on plan design: expert – Benefits Canada

    • Canada becomes the first G7 country to approve a generic version of semaglutide – Health Canada

    • Drug plan management and generic substitution – Canadian Life and Health Insurance Association

    https://crossroadsfinancial.ca/wp-content/uploads/2026/07/GenericOzempicFI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-07-15 10:35:142026-07-15 10:35:48Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?

    What Happens to Your Group Benefits When You Leave a Job?

    July 1, 2026/in 2026, Blog, Group Benefits/by Crossroads Financial Inc.

    What Happens to Your Group Benefits When You Leave a Job?

    Leaving a job, whether by choice or by circumstance, brings a long to-do list. Updating your resume, signing new paperwork, figuring out your finances. One item that often gets missed in the shuffle: your group benefits.

    For many Canadians, employer-provided health, dental, vision, and life insurance coverage quietly disappears the moment they leave. Here is what actually happens, what your options are, and what steps to take so you do not end up without coverage when you need it most.

    When Does Coverage End?

    The exact end date depends on your employer’s plan, but most group benefits plans terminate coverage on one of two dates:

    • The last day of active employment, meaning your coverage ends the day you stop working.

    • The last day of the month in which you stop working, which gives you a short buffer.

    Your employee handbook or HR contact can confirm which applies to your plan. If you are being laid off or terminated, sometimes an employer will extend benefits for a defined period as part of a severance arrangement, this should be spelled out in any severance agreement you receive. In some provinces, such as British Columbia, employees who are laid off may also have the option to voluntarily continue their coverage for up to six months by paying the premiums themselves.

    The takeaway: do not assume coverage continues past your last day. It usually does not, and even a brief gap can leave you on the hook for expenses.

    brandableContent

    What Coverage Goes With You, and What Disappears

    Not all group benefits disappear the same way. Here is what typically happens with each type:

    Health and dental: These end on your termination date (or end of month, depending on the plan). Most plans include a run-off period, typically 30 to 90 days, to submit claims for services you received while you were still covered. Any claims for services after your termination date will be denied. Before you leave, it is worth getting any outstanding treatments done and filling any prescriptions. Some insurers also offer conversion options for extended health and dental coverage within 60 to 90 days of losing group coverage, though this is less common than life insurance conversion.

    Vision: Same as health and dental, coverage ends, and unused benefit maximums do not transfer.

    Life insurance and accidental death and dismemberment (AD&D): Group life insurance through your employer is usually converted to an individual policy without medical evidence through a feature called the conversion privilege. This is one of the most important and least-known options available to departing employees.

    Short-term and long-term disability: These stop when employment ends. You cannot claim disability benefits from a former employer’s plan after your last day. If you are already on a disability claim when you leave, the rules get more specific, check your plan documents.

    Employee Assistance Programs: These end at termination as well.

    The Conversion Privilege: A Rarely Used but Valuable Option

    Most group life insurance plans come with a conversion privilege, the right to convert your group life coverage to an individual permanent life insurance policy without providing evidence of insurability. That means no medical questions, no physical exam.

    There is a catch: you typically have only 31 days from the date your group coverage ends to exercise this option. Miss that window, and you lose it.

    The converted policy will cost more than your group coverage did. Group rates are typically lower because the risk is pooled across all employees. An individual policy reflects your age and the fact that the insurer cannot screen for health. But for someone who has developed a health condition during employment and would otherwise have difficulty qualifying for individual coverage, this option is a lifeline.

    Contact your former employer’s benefits administrator or the insurer directly to find out the exact deadline and how to start the conversion process.

    Your Options for Replacing Health and Dental Coverage

    Once your group plan ends, you have a few paths to replacing health and dental coverage:

    A spouse or partner’s plan. If your partner has their own employer plan, losing your group coverage is typically considered a qualifying life event that allows them to add you immediately, without waiting for an open enrollment period. Act within 30 to 60 days of your coverage ending, as most plans require prompt notification.

    Individual health and dental insurance. Insurance companies offer individual health and dental plans that you can apply for on your own. Premiums are higher than group rates, and pre-existing conditions may not be covered, but this option fills the gap if no group plan is available to you. Many providers allow applications within 60 days of losing group coverage to waive certain waiting periods.

    Professional or industry associations. Some professional groups, engineers, teachers, freelancers, offer group benefit plans to members at better rates than individual plans. If you belong to or qualify for membership in an association, this can be worth exploring.

    What to Do Before Your Last Day

    A few practical steps to take before you walk out the door:

    Get a copy of your benefits booklet or summary plan document. This outlines exactly what your plan covers, how conversion works, and the deadlines involved. HR should be able to provide this.

    Use what you can before your coverage ends. Book that dental cleaning, fill outstanding prescriptions, and pick up any medical supplies covered under your plan. Most people leave money on the table simply by not timing this properly.

    Clarify your exact termination date for benefits purposes. Ask HR explicitly whether benefits end on your last day worked or at the end of that month.

    Check the conversion privilege deadline. If you have any concern about qualifying for individual life insurance, find out your deadline immediately and do not let it pass.

    Notify your partner’s employer. If you plan to join your partner’s group plan, they need to notify their plan administrator within the required window, typically 30 to 60 days.

    The Gap You Do Not Want

    Going without health and dental coverage for even a short time can be expensive. A single dental emergency, a course of prescription medication, or a specialist visit that falls outside provincial coverage can cost hundreds to thousands of dollars out of pocket.

    The good news is that a gap does not have to happen. With a bit of planning and quick action after your last day, you can move from one source of coverage to another without interruption.

    Have questions about your coverage options? We are here to help. Reach out to our team and we will walk you through what makes sense for your situation.

    This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

    Sources:

    • Leaving Your Group Benefits Plan – Sun Life

    • Group Benefits – CLHIA

    https://crossroadsfinancial.ca/wp-content/uploads/2026/07/Group-benefits-checklist-When-you-leave-a-job.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-07-01 06:01:052026-07-01 06:01:39What Happens to Your Group Benefits When You Leave a Job?

    What Is Participating Whole Life Insurance?

    June 1, 2026/in 2026, Blog, Insurance/by Crossroads Financial Inc.

    What Is Participating Whole Life Insurance?

    Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.

    Here is what it means, how it works, and whether it might be a fit for you.

    Permanent Coverage That Does Not Expire

    Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.

    That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.

    With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.

    How Dividends Work

    The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.

    These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.

    When you receive a dividend, you have a few options for how to use it:

    • Take it as cash. The dividend is paid to you directly.

    • Apply it to your premium. It reduces how much you pay out of pocket.

    • Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.

    • Leave it on deposit. The dividend sits with the insurer and earns interest.

    Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.

    The Cash Value

    One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.

    The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:

    • Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.

    • Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.

    The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.

    Who Is This Type of Policy For?

    Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.

    Some of the most common situations where it makes sense:

    Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.

    Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.

    Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.

    High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.

    How It Fits Alongside Term Insurance

    Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.

    Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.


    Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.

    What to Take Away

    Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.

    If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.

    This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.

    Sources:

    Participating Life Insurance – CLHIA

    https://crossroadsfinancial.ca/wp-content/uploads/2026/06/WhatisWholLifeFI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-06-01 12:32:132026-06-01 12:32:32What Is Participating Whole Life Insurance?

    Tax Lines to Look Out For on Your 2025 Canadian Tax Return

    April 1, 2026/in 2026, Blog/by Crossroads Financial Inc.

    Tax Lines to Look Out For on Your 2025 Canadian Tax Return

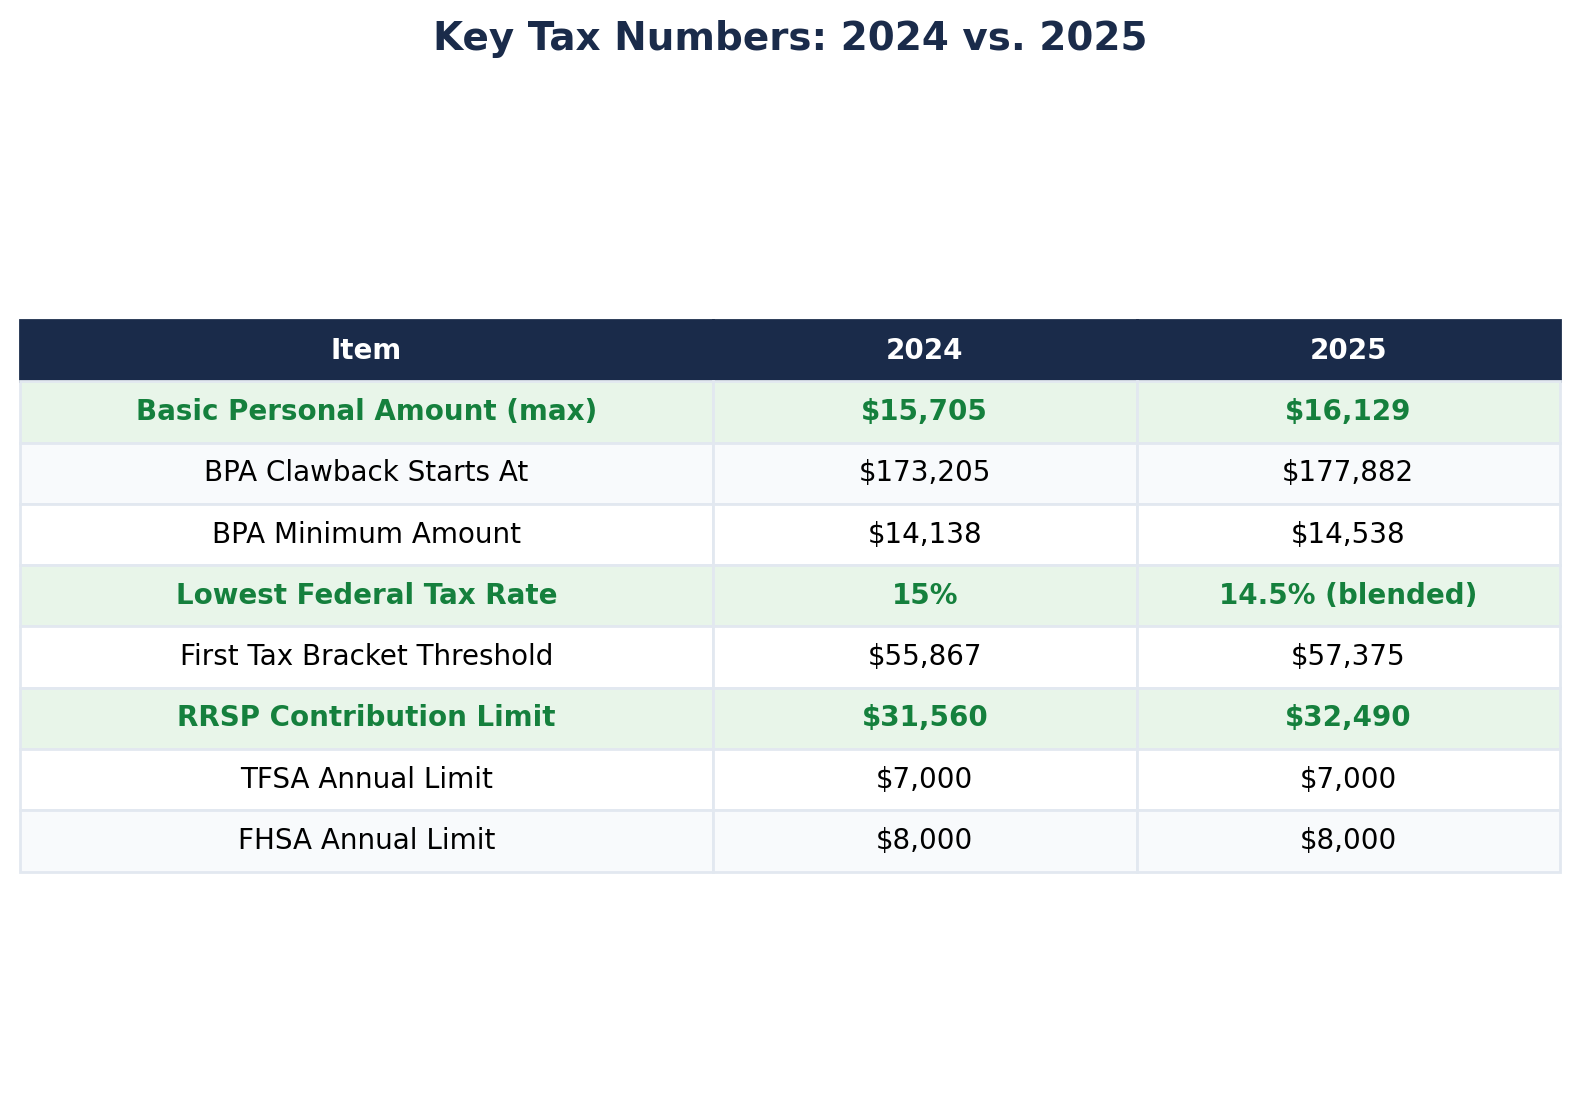
    The deadline for filing your 2025 income tax return is April 30, 2026. With several changes this year, from a lower federal tax rate to new benefits and eliminated credits, it pays to know what has changed before you file. This guide covers the key updates, deductions, and credits separated into sections for Individuals and Families, and Self-Employed Individuals.

    For Individuals and Families

    Federal Tax Rate Reduction

    Effective July 1, 2025, under draft legislation introduced May 27, 2025, the lowest federal income tax rate was reduced from 15% to 14%. Because this change took effect halfway through the year, the blended rate for 2025 is 14.5%. This applies to the first $57,375 of taxable income and could save an individual up to $420 per year, or up to $840 for a two-income household.

    Because the lowest rate also determines the value of most non-refundable tax credits, the government introduced a new top-up credit. This credit restores the full 15% value on eligible non-refundable credits claimed on amounts above $57,375, so the rate cut does not reduce the value of credits like the Basic Personal Amount, medical expenses, or tuition. This top-up credit will remain in place through the 2030 tax year.

    Basic Personal Amount (BPA)

    For 2025, the Basic Personal Amount has increased to $16,129 for taxpayers with net income up to $177,882. For those with net incomes above this amount, the BPA is gradually reduced, reaching a minimum of $14,538 at incomes of $253,414 or higher.

    Capital Gains

    The proposed increase in the capital gains inclusion rate from 50% to 66.67% on gains over $250,000 for individuals (and on all gains for corporations and most trusts) has been cancelled. The inclusion rate remains at 50% for all taxpayers. However, the lifetime capital gains exemption has been raised to $1,250,000 for qualifying dispositions of small business shares and farming or fishing property, up from $1,016,836.

    Canada Disability Benefit

    A new benefit became available in June 2025, providing up to $200 per month ($2,400 per year) for Canadian residents aged 18 to 64 who are approved for the Disability Tax Credit.

    The benefit is income-tested, with the maximum amount generally available to single individuals with adjusted family net income of $23,000 or less. For couples, the threshold is higher (generally $32,500 after a working income exemption).

    The benefit is gradually reduced as income increases. For single individuals, it is typically reduced by 20 cents for each dollar above the threshold. For couples, the reduction may be 20% or split at 10% each, depending on whether one or both partners qualify for the benefit.

    What Has Been Eliminated

    Canadian Journalism Tax Credit: The 15% non-refundable tax credit for qualifying digital news subscriptions (up to $75 per year) is no longer available for 2025.

    Home Accessibility and Medical Expense Double-Claim: Under proposed measures announced in Budget 2025 and included in Bill C-15, 2025 is expected to be the final year that certain expenses qualifying for the Home Accessibility Tax Credit can also be claimed as a medical expense. Starting in 2026, these expenses will generally need to be claimed under only one provision and cannot be double-counted. Individuals planning eligible renovations may wish to take advantage of the current rules before this change takes effect.

    Alternative Minimum Tax (AMT)

    The updated AMT rules that took effect in 2024 continue to apply. These include a higher minimum tax rate, modified calculation for adjusted taxable income affecting foreign tax credits and minimum tax carryovers, and limited value on most non-refundable tax credits.

    Popular Tax Credits and Deductions

    Canada Training Credit (CTC) Eligible taxpayers aged 26 to 65 can claim this refundable tax credit to cover a portion of eligible tuition and fees for training or courses to enhance their skills.

    Canada Caregiver Credit (CCC) This non-refundable tax credit supports individuals caring for family members or dependents with a physical or mental impairment. The amount varies based on the dependent’s relationship, net income, and circumstances.

    Child Care Expenses Child care expenses, such as daycare, nursery schools, day camps, and boarding schools, are deductible if incurred to enable a parent or guardian to work, pursue education, or conduct research.

    Disability Tax Credit (DTC) The DTC provides a non-refundable tax credit for individuals with disabilities or their caregivers to reduce the amount of income tax payable. For 2025, the disability amount is $10,138. Applicants must have a certified disability lasting at least 12 months. The expenses eligible for the disability supports deduction have also been expanded for 2025.

    Moving Expenses Deductible moving expenses include transportation and storage costs, travel expenses, temporary living costs, and incidental expenses incurred when relocating at least 40 kilometers closer to a new work location, educational institution, or business location.

    Interest Paid on Student Loans Interest paid on eligible student loans can be claimed as a non-refundable tax credit. The loans must be under federal, provincial, or territorial student loan programs.

    Donations and Gifts Donations made to registered charities or other qualified organizations qualify for non-refundable federal and provincial tax credits. Typically, eligible amounts up to 75% of net income can be claimed. Note: due to the Canada Post strike in late 2024, eligible donations made in the first two months of 2025 can also be claimed on a 2024 return.

    GST/HST Credit The GST/HST credit is a quarterly refundable payment designed to offset the impact of sales tax on low to moderate-income individuals and families. Eligibility is automatically assessed based on the annual tax return.

    RRSP Contributions The maximum RRSP contribution for 2025 has increased to $32,490 (up from $31,560 in 2024), based on 18% of the previous year’s earned income. The TFSA annual contribution limit remains at $7,000 for 2025.

    First Home Savings Account (FHSA) Contributions of up to $8,000 per year (lifetime limit of $40,000) are tax-deductible, grow tax-free, and qualifying withdrawals for a first home purchase are also tax-free. The FHSA can be used alongside the Home Buyers’ Plan, which maintains a withdrawal limit of $60,000.

    For Self-Employed Individuals

    CPP Contributions

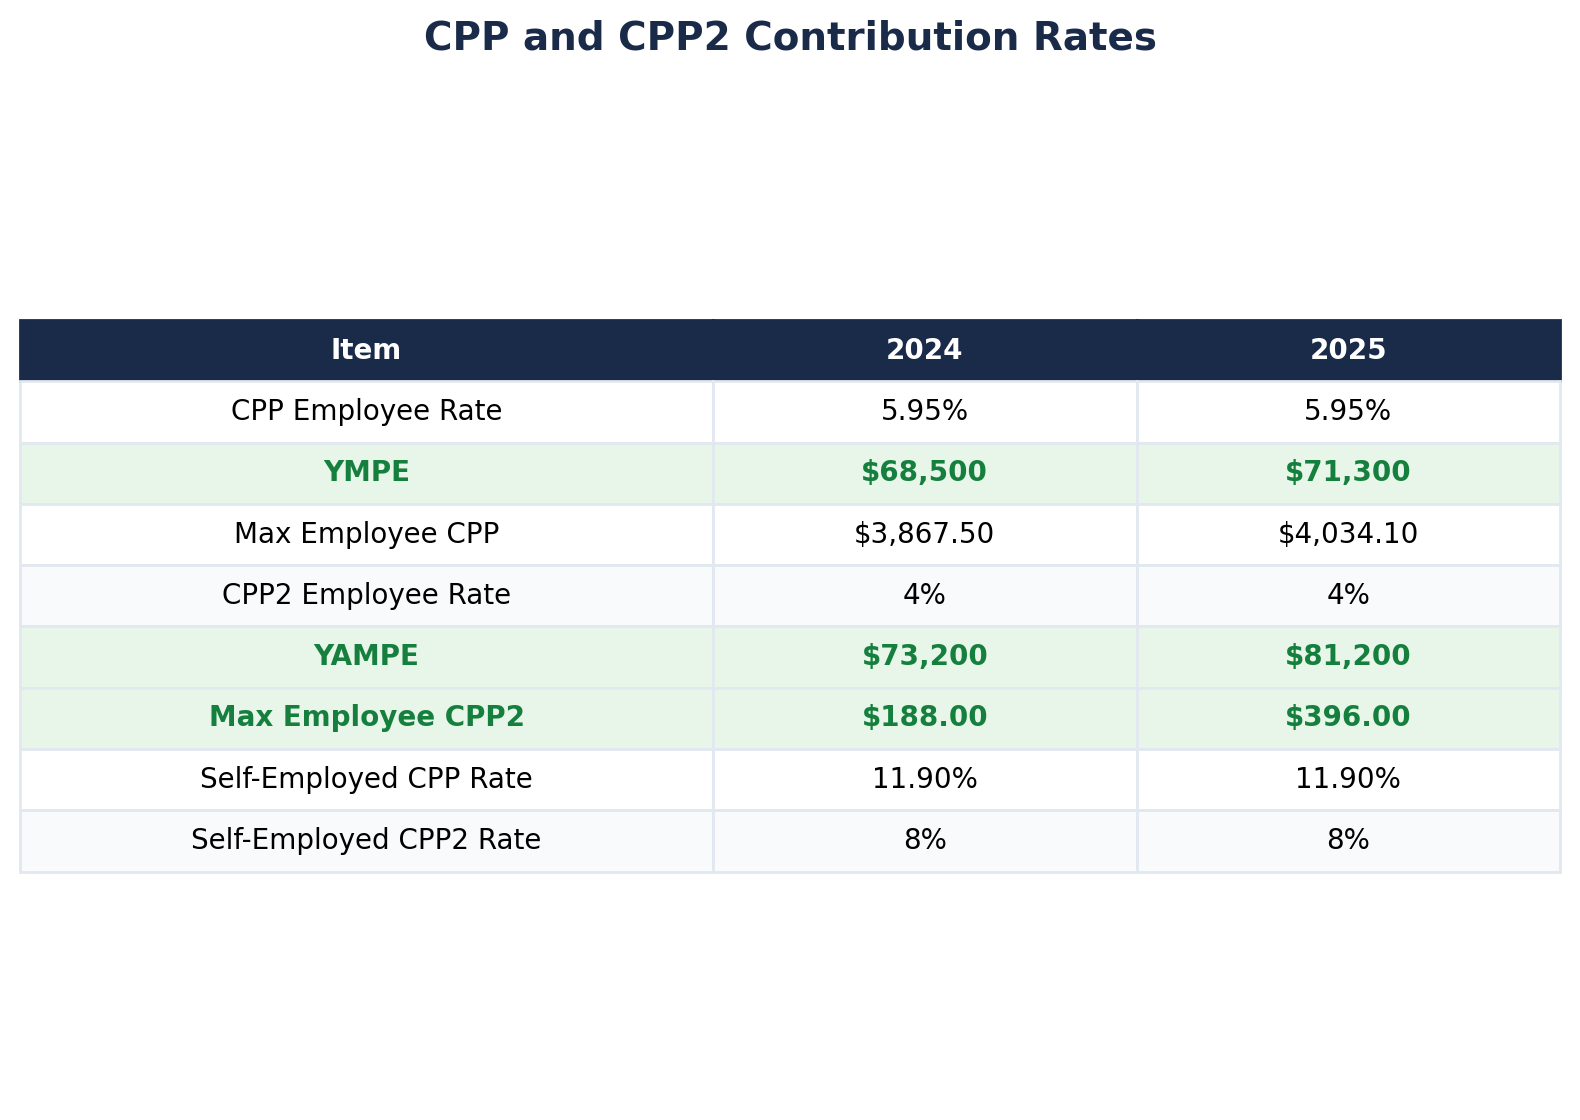
    Self-employed individuals pay both the employee and employer portions of CPP, for a combined rate of 11.90% on earnings up to the YMPE ($71,300). For CPP2, the self-employed rate is 8% on earnings between $71,300 and $81,200, with a maximum CPP2 contribution of $792.

    Filing and Payment Deadlines

    • Tax Return Deadline: June 15, 2026.

    • Balance due must be paid by April 30, 2026.

    Reporting Business Income

    Report income on a calendar-year basis for sole proprietorships and partnerships.

    Digital Platform Operators

    Reporting rules require platform operators to collect and report seller information to the CRA. If income is earned through a digital platform, it is important to ensure it is properly reported.

    Filing season for 2025 returns opens February 23, 2026. With a lower federal tax rate, increased contribution limits, and several eliminated credits and taxes, reviewing these changes before filing can help maximize savings and avoid surprises. The CRA is also no longer mailing paper tax packages, so returns and forms are available online at canada.ca or by calling 1-855-330-3305.

    Sources

    Canada Revenue Agency. “Personal income tax: What’s new for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/whats-new.html

    Canada Revenue Agency. “Important changes to the 2025 income tax package.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2025/important-changes-2025-income-tax-package.html

    Canada Revenue Agency. “Maximum Pensionable Earnings and Contributions for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2024/canada-revenue-agency-announces-maximum-pensionable-earnings-contributions-2025.html

    Canada Revenue Agency. “Basic Personal Amount.” – Canada.ca – https://www.canada.ca/en/revenue-agency/programs/about-canada-revenue-agency-cra/federal-government-budgets/basic-personal-amount.html

    Canada Revenue Agency. “Tax rates and income brackets for individuals.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/frequently-asked-questions-individuals/canadian-income-tax-rates-individuals-current-previous-years.html

    “Budget 2025 – Tax Measures” (Home Accessibility Tax Credit change) – https://budget.canada.ca/2025/report-rapport/tm-mf-en.html

    This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

    https://crossroadsfinancial.ca/wp-content/uploads/2026/04/2025-Tax-Lines-to-Look-Out-For-.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-04-01 12:08:082026-04-01 12:08:24Tax Lines to Look Out For on Your 2025 Canadian Tax Return

    Ontario Budget 2026

    March 30, 2026/in 2026, Blog/by Crossroads Financial Inc.

    What the 2026 Ontario Budget Means for Your Wallet and Your Business

    If you live or run a business in Ontario, the provincial budget released on March 26, 2026 includes several changes that could affect your taxes, your home purchase, and your bottom line. Whether you are a small business owner, a home buyer, or an investor, there are a few measures worth paying attention to in this year’s budget.

    Here is a breakdown of the biggest highlights and what they could mean for you.

    Tax Break for Small Businesses

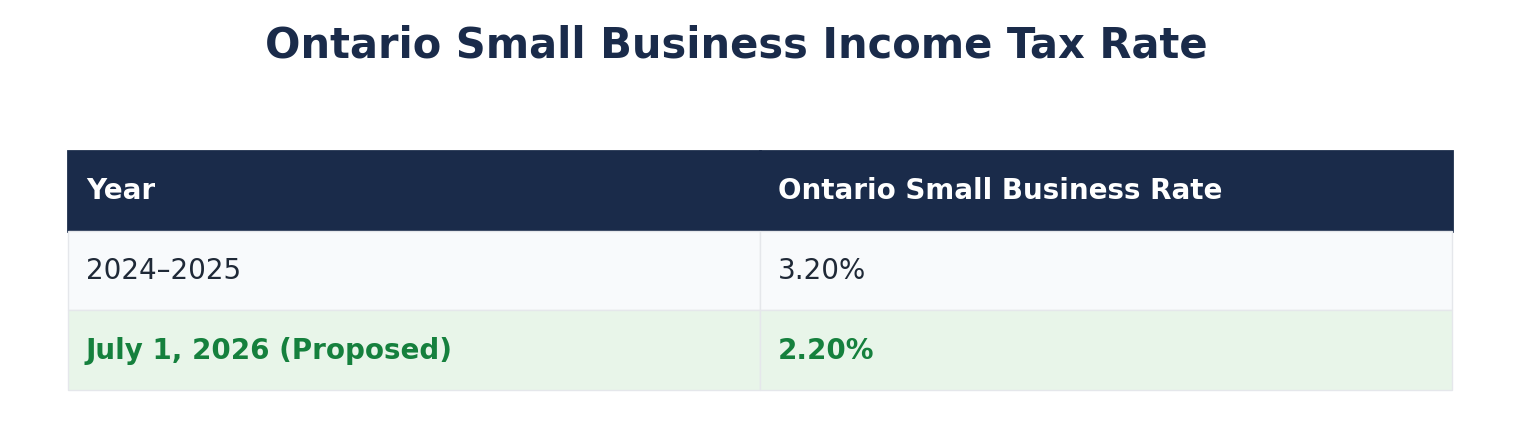
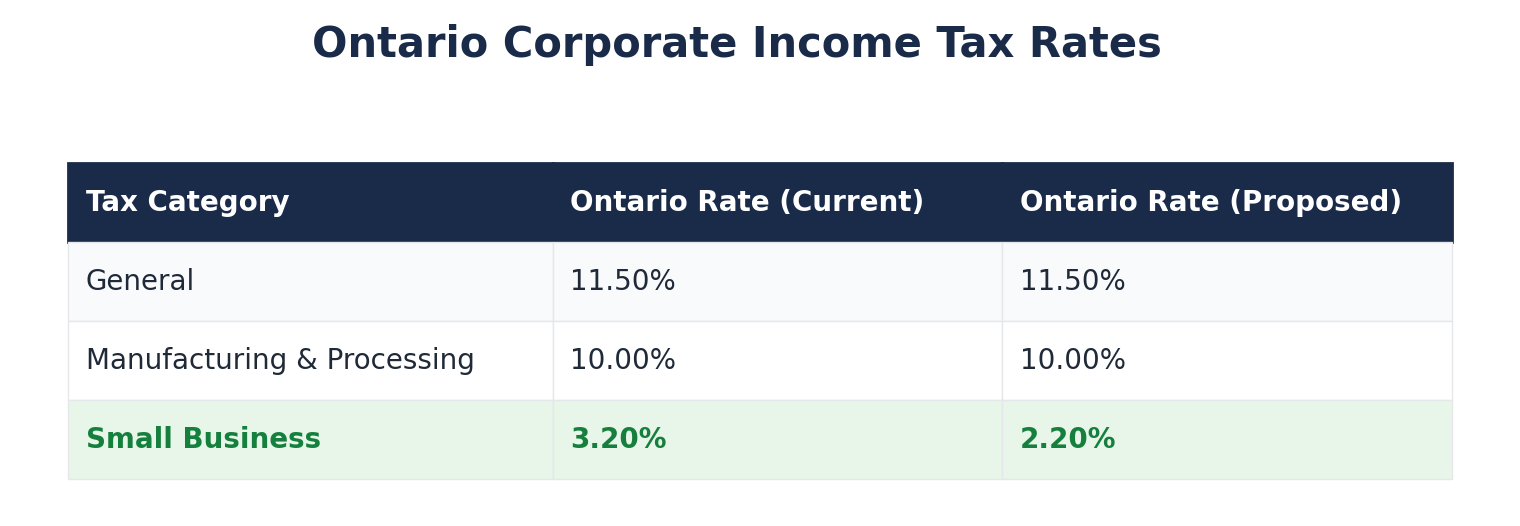
    One of the biggest changes in this budget is a proposed cut to Ontario’s small business corporate income tax rate. The rate would fall from 3.2% to 2.2%, effective July 1, 2026. That is a reduction of more than 30%, and it applies to the first $500,000 of active business income earned by eligible small Canadian-controlled private corporations.

    For a small business earning $500,000 in eligible income, that could mean savings of up to $5,000 per year. Because the change takes effect mid-year, the rate would be prorated for taxation years that straddle July 1, 2026.

    For business owners who are managing rising costs or looking to invest in growth, that kind of savings could make a meaningful difference. It may also help free up cash for hiring, equipment purchases, or day-to-day operations.

    Here is how the Ontario small business rate compares:

    Here is a look at Ontario’s corporate income tax rates, with the small business rate reflecting the proposed change:

    Small business rate applies to the first $500,000 of active business income. The proposed 2.2% rate takes effect July 1, 2026. Combined federal and provincial rates will vary depending on your specific situation — your accountant can confirm the exact figures for your business.

    Non-Eligible Dividends

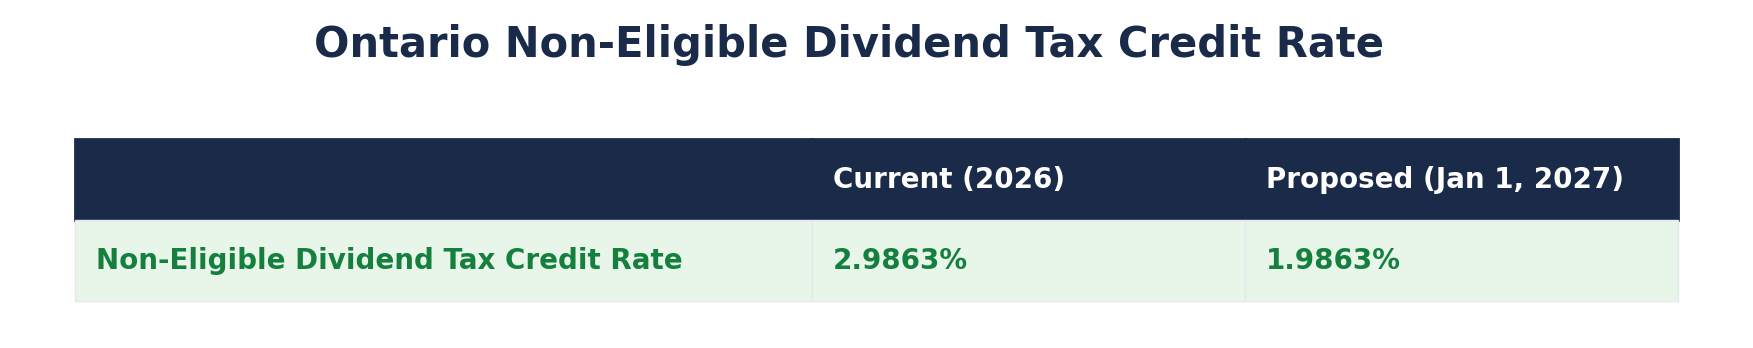
    If you receive non-eligible dividends, or if you own a corporation and pay yourself dividends, there is another change to note. Ontario is proposing to reduce the non-eligible dividend tax credit rate from 2.9863% to 1.9863%, effective January 1, 2027.

    This change is linked to the lower small business corporate tax rate. In general, when corporate tax rates fall, dividend tax credit rates are adjusted to reflect the change in after-tax corporate income.

    The budget does not directly state combined top marginal rates, but the effect of reducing the dividend tax credit is that the tax you owe on non-eligible dividends would increase. If dividends are part of your income strategy, it may be worth reviewing how this could affect your overall tax picture.

    More Flexibility for Employee Benefit Plans

    If you offer employee benefits through a funded benefit plan, Ontario is proposing a change that could improve cash flow. Starting April 1, 2026, funded benefit plans would be able to elect to be treated as unfunded plans for Insurance Premium Tax purposes.

    In practical terms, that means the tax would be triggered when benefits are paid out rather than when contributions are made into the plan. If you sponsor a benefit plan, it may be worth checking whether this election is useful for your business.

    Faster Write-Offs for Business Equipment

    The budget also proposes accelerated deductions for depreciable assets, in parallel with changes announced by the federal government. Ontario says these measures would lower the cost of investing in a broad range of assets, and they would take effect following the passage of federal legislation.

    For business owners considering major purchases, faster deductions can improve cash flow by allowing more of the cost to be deducted sooner rather than spread over several years.

    The budget also proposes to let the Regional Opportunities Investment Tax Credit expire effective January 1, 2027, with expenditures incurred on or before December 31, 2026 still eligible.

    Keeping Costs Down for Families

    Beyond tax changes, the budget includes several measures aimed at easing everyday costs for Ontario families. The Ontario Electricity Rebate continues, the Ontario One Fare Program is being extended for another two years, and tolls on the provincially owned portion of Highway 407 East have been removed.

    Ontario says the One Fare extension could save daily transit users in the Greater Toronto and Hamilton Area up to $1,600 per year, while the Electricity Rebate continues to reduce electricity bills for households.

    The budget also includes support for families and individuals through a range of spending measures in health care, education, and social programs.

    HST Relief for New Home Buyers

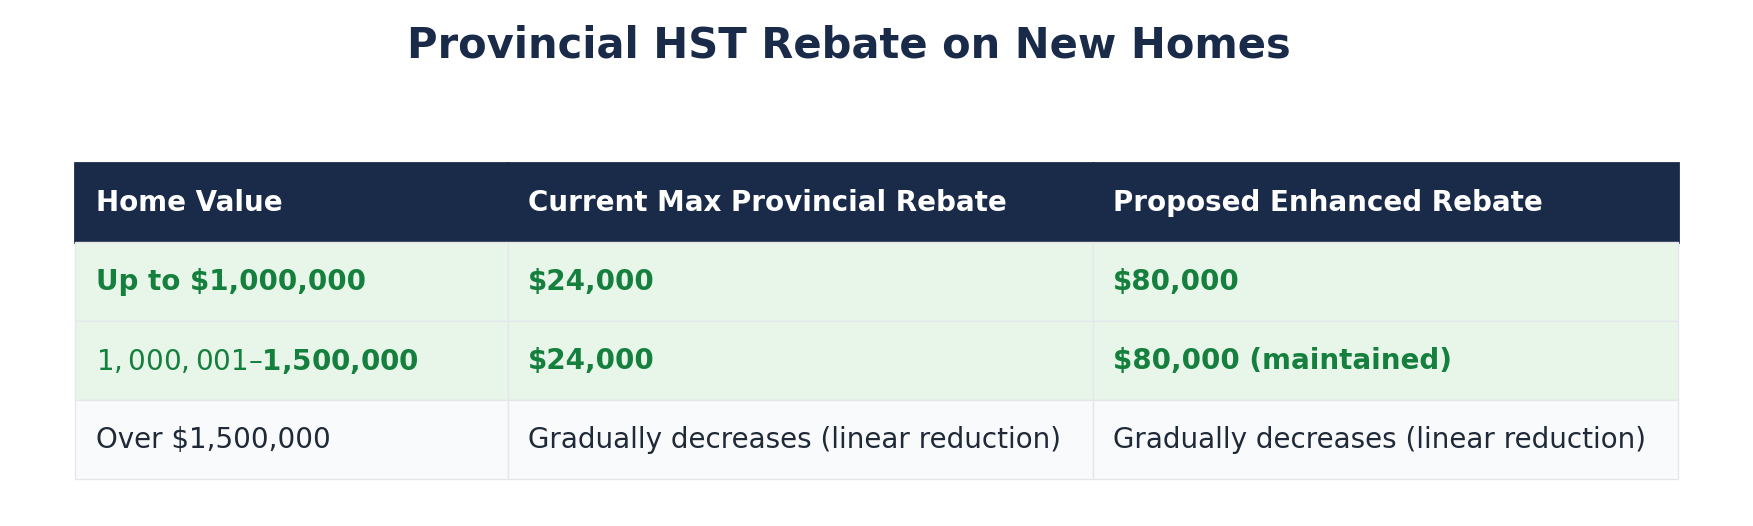
    If you are thinking about buying a new home or condo, the budget includes a major temporary expansion of Ontario’s housing rebates. Ontario is proposing to provide further relief for eligible buyers of new homes by removing the full 13% HST on qualifying new homes valued up to $1 million, subject to federal legislation. The maximum rebate amount would be maintained for homes valued up to $1.5 million.

    The federal government has agreed to cost-share, subject to the passage of federal legislation, to cover the federal 5% portion being removed. The enhanced rebate is proposed to apply from April 1, 2026 to March 31, 2027.

    Here is a quick look at what the proposed rebate change could mean depending on your home’s value:

    The budget also proposes to eliminate the provincial HST New Housing Rebate and the New Residential Rental Property Rebate after the enhancement period ends, with further transitional details to be set out later.

    Ontario is also proposing to align its first-time home buyer rebate with the federal GST/HST First-Time Home Buyers’ Rebate. These changes require federal regulatory changes, and Ontario says it will continue working with the federal government to support implementation. Under the proposal, the rebate would apply to agreements of purchase and sale entered into on or after March 20, 2025 and before 2031.

    The Big Picture

    Ontario is projecting planned capital investments of more than $210 billion over 10 years, including $37 billion in 2026–27. The province says these investments will support highways, hospitals, transit, and other infrastructure across Ontario.

    At the same time, the budget is being framed as part of the province’s response to tariffs and broader economic uncertainty.

    What This Means for You

    This budget touches a wide range of financial decisions. If you own a small business, you may want to review your tax strategy in light of the lower corporate rate and accelerated deductions. If you are a first-time home buyer or considering a new build, the enhanced HST rebate could create a valuable but time-limited opportunity. If you receive non-eligible dividends, the tax credit change beginning in 2027 is something to plan for now.

    Every situation is different, so the best next step is to review these changes and see which ones apply to you.

    Sources

    Ontario Ministry of Finance, 2026 Ontario Budget: A Plan to Protect Ontario — Highlights – https://budget.ontario.ca/2026/highlights.html

    Ontario Ministry of Finance, Annex: Details of Tax Measures and Other Legislative Initiatives – https://budget.ontario.ca/2026/annex.html

    This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

    https://crossroadsfinancial.ca/wp-content/uploads/2026/03/Ontario-Budget-2026-FI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-03-30 10:00:322026-03-30 10:00:38Ontario Budget 2026

    2026 Canada Money Facts

    March 2, 2026/in 2026, Blog, tax/by Crossroads Financial Inc.

    brandableContent

    Staying informed about financial limits and government benefits is essential for effective planning. The 2026 Canada Money Facts infographic provides a clear snapshot of key savings limits and retirement benefits, including TFSA, RRSP, FHSA, RESP, CPP, and OAS.
    Here’s what you need to know for 2026.

    Tax-Free Savings Account (TFSA)

    The 2026 TFSA contribution limit is $7,000, bringing the cumulative contribution room to $109,000 for individuals who have been eligible since the TFSA was introduced in 2009 and have never contributed.

    It’s important to note that total TFSA room depends on personal circumstances. Eligibility begins at age 18 or 19, depending on the province, and newcomers to Canada accumulate room only from the year they become residents. If you became eligible after 2009, your cumulative limit will be lower based on the years you qualified.

    The TFSA remains one of the most flexible savings tools available, allowing investments to grow tax-free and withdrawals to be made without triggering tax.

    Registered Retirement Savings Plan (RRSP)

    For 2026, the RRSP contribution limit is $33,810, calculated as 18% of earned income from the prior year, up to the annual maximum. To fully maximize RRSP contributions for 2026, an individual would need prior-year earned income of approximately $187,833.

    RRSPs continue to be a cornerstone of retirement planning, offering tax-deductible contributions and tax-deferred growth, which can be especially valuable during higher-income earning years.

    First Home Savings Account (FHSA)

    The FHSA annual contribution limit remains $8,000 in 2026, with a cumulative contribution limit of $32,000.

    As with previous years, FHSA eligibility begins at the age of majority (18 or 19, depending on the province), and contributions can only be made once the account is opened. Since the FHSA was introduced in 2023, not everyone will have access to the full cumulative room.

    FHSA contributions are tax-deductible, and qualifying withdrawals for a first home purchase are tax-free, making this account a powerful planning tool for first-time homebuyers.

    Registered Education Savings Plan (RESP)

    RESP limits remain unchanged in 2026:

    • Lifetime contribution limit: $50,000 per beneficiary

    • Annual Canada Education Savings Grant (CESG): up to $500

    • Lifetime CESG maximum: $7,200

    RESPs continue to be an effective way to save for a child’s post-secondary education while benefiting from government grants and tax-deferred growth.

    Canada Pension Plan (CPP) & Old Age Security (OAS)

    CPP benefit amounts increase for 2026:

    • Maximum CPP retirement benefit: $18,091 annually

    • Maximum CPP disability benefit: $20,894 annually

    Actual CPP payments depend on an individual’s contribution history and the age at which benefits begin, but these figures provide a useful benchmark for planning purposes.

    OAS payments for January 2026 are estimated at:

    • Ages 65–74: up to $8,907 annually

    • Ages 75+: up to $9,798 annually

    OAS is subject to a clawback for higher-income retirees. In 2026, the clawback begins when 2025 net income exceeds $93,454. Full clawback thresholds are approximately $152,062 for ages 65–74 and $157,923 for ages 75 and over. OAS benefits are reduced by 15% of income above the threshold.

    This 2026 infographic is designed as a quick reference to help Canadians stay informed and make confident planning decisions. Whether you’re maximizing registered accounts, preparing for retirement income, or saving for a home or education, understanding these updated limits helps ensure you’re making the most of available opportunities.

    Staying proactive and informed in 2026 can make a meaningful difference in your long-term financial success.

    Sources:

    TFSA contribution limits: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html

    RRSP contribution limits: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans.html

    First Home Savings Account: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/first-home-savings-account.html

    Registered Education Savings Plan: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-education-savings-plans-resps.html

    Canada Pension Plan: https://www.canada.ca/en/services/benefits/publicpensions/cpp/payment-amounts.html

    Old Age Security: https://www.canada.ca/en/services/benefits/publicpensions/cpp/old-age-security/payments.html
    – h2.1

    https://crossroadsfinancial.ca/wp-content/uploads/2026/03/Money-Facts-2026.jpg 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-03-02 11:24:082026-03-02 11:24:152026 Canada Money Facts

    Tax-Free Savings Account vs Registered Retirement Savings Plan

    February 2, 2026/in 2026, Blog, Investment, rrsp, Tax Free Savings Account/by Crossroads Financial Inc.

    Tax-Free Savings Account vs Registered Retirement Savings Plan

    When it comes to saving in a tax-efficient way, Canadians often ask the same question: Should I use a TFSA or an RRSP?

    Both accounts offer valuable tax advantages, but they work differently — and the “right” choice depends on your income, goals, and how you expect to use the money in the future. As advisors, we often help clients understand not just how these accounts work, but how to use them strategically together.

    Below, we break down the key differences between TFSAs and RRSPs, focusing on how contributions and withdrawals work — and how those differences can shape your overall plan.

    TFSA vs RRSP: Differences in Contributions

    When comparing how TFSAs and RRSPs work on the contribution side, there are four main factors we look at with clients:

    • Contribution room

    • Carry forward rules

    • Tax deductibility

    • Tax treatment of growth

    brandableContent

    How much contribution room do you have?

    TFSA

    Your TFSA contribution room is based on an annual limit set by the federal government, which is indexed and may change over time. If you don’t use your full TFSA room in a given year, the unused amount carries forward and continues to accumulate as long as you’re eligible.

    This makes the TFSA especially flexible for people who contribute irregularly or who want to prioritize liquidity.

    RRSP

    RRSP contribution room is based on your income. Each year, you can contribute up to 18% of your earned income from the prior year, up to an annual maximum set by the Canada Revenue Agency.

    Because RRSP room depends on income, contribution limits will naturally vary from person to person.

    Can unused contribution room be carried forward?

    Yes — for both accounts, but with different rules.

    TFSA

    Unused TFSA contribution room can be carried forward indefinitely. If you make a withdrawal, the amount withdrawn is added back to your available contribution room in the following calendar year.

    RRSP

    Unused RRSP contribution room can also be carried forward, but only until the year you turn 71. At that point, your RRSP must be converted to a Registered Retirement Income Fund (RRIF) or another qualifying option. Withdrawals from an RRSP do not create new contribution room.

    Are contributions tax-deductible?

    This is one of the most important distinctions.

    • TFSA contributions are made with after-tax dollars and are not tax-deductible.

    • RRSP contributions are made with pre-tax dollars and are tax-deductible, which can reduce your taxable income in the year you contribute.

    How is investment growth taxed?

    • TFSA growth is completely tax-free. You don’t pay tax on interest, dividends, capital gains, or withdrawals.

    • RRSP growth is tax-deferred. Investments can grow without tax while they remain inside the plan, but withdrawals are taxable when taken.

    This difference plays a major role in how each account is used within a broader financial strategy.

    TFSA vs RRSP: Differences in Withdrawals

    Understanding how withdrawals work is just as important as understanding contributions. When we help clients evaluate withdrawals, we focus on:

    • Conversion requirements

    • Tax treatment

    • Impact on government benefits

    • Effect on future contribution room

    brandableContent

    Are there conversion requirements?

    TFSA

    There are no conversion requirements for a TFSA. You can hold and use a TFSA at any age.

    RRSP

    An RRSP must be converted to a RRIF (or similar option) by December 31 of the year you turn 71. After conversion, minimum annual withdrawals are required.

    How are withdrawals taxed?

    TFSA

    All TFSA withdrawals are tax-free, regardless of when or why the money is withdrawn.

    RRSP

    RRSP withdrawals are taxed as income in the year they’re taken.

    There are two commonly used programs that allow temporary RRSP withdrawals:

    • The Home Buyers’ Plan (HBP)

    • The Lifelong Learning Plan (LLP)

    Withdrawals under these programs are not taxed at the time of withdrawal, provided they are repaid according to the program rules. If they are not repaid, the amounts become taxable income.

    How do withdrawals affect government benefits?

    This is an area we pay close attention to when planning withdrawals.

    • TFSA withdrawals do not count as taxable income and generally do not affect income-tested government benefits.

    • RRSP (and RRIF) withdrawals are taxable and may affect income-tested benefits and tax credits, depending on your total income.

    This distinction often makes TFSAs particularly valuable later in life or during years when benefit eligibility matters.

    Do withdrawals create new contribution room?

    • TFSA: Withdrawals restore contribution room in the following calendar year.

    • RRSP: Withdrawals do not create new contribution room.

    How advisors typically help clients choose

    In practice, the decision isn’t usually TFSA or RRSP — it’s how and when to use each.

    We often consider:

    • Current vs future tax rates

    • Income stability

    • Access to employer pension plans

    • Government benefits today or later

    • Short-term flexibility vs long-term tax deferral

    Used thoughtfully, both accounts can play an important role in a well-structured plan.

    TFSAs and RRSPs are both powerful savings tools, but they’re designed to solve different problems. Understanding how they work — and how they interact with your income, taxes, and benefits — can make a meaningful difference over time.

    If you’d like help determining how a TFSA, RRSP, or a combination of both fits into your overall strategy, we’re happy to walk through your options with you.

    Sources:

    Canada Revenue Agency. Registered Retirement Savings Plan (RRSP). Government of Canada, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/registered-retirement-savings-plan-rrsp.html

    Canada Revenue Agency. Tax-Free Savings Account (TFSA). Government of Canada, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html

    https://crossroadsfinancial.ca/wp-content/uploads/2026/02/TFSA-vs-RRSP-FI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-02-02 15:51:082026-02-02 15:51:21Tax-Free Savings Account vs Registered Retirement Savings Plan

    2026 Financial Calendar

    January 2, 2026/in 2026, Blog, Family, Financial Planning, personal finances, rrsp, tax, Tax Free Savings Account/by Crossroads Financial Inc.

    brandableContent
    brandableContent
    brandableContent
    brandableContent
    brandableContent

    Welcome to our 2026 financial calendar!

    This calendar is designed to help you keep track of important financial dates and deadlines, such as tax filing and government benefit distribution. You can bookmark this page for easy reference or add these dates to your personal calendar so you don’t miss any important financial obligations.

    If you need help with your taxes, 2025 income tax packages will be available starting January 20, 2026. Don’t wait until the last minute to get started on your tax return – make an appointment with your accountant so you’re ready when tax season arrives.

    Important Dates to Know

    On January 1, 2026, the contribution room for your Tax-Free Savings Account (TFSA) opens again. The TFSA dollar limit for 2026 is $7,000.

    For those who are eligible, the contribution room for your:

    • Registered Retirement Savings Plan (RRSP)

    • First Home Savings Account (FHSA)

    • Registered Education Savings Plan (RESP)

    • Registered Disability Savings Plan (RDSP)

    will also be available for the 2026 calendar year.

    RRSP Deadline (for the 2025 Tax Year)

    For your Registered Retirement Savings Plan (RRSP) contributions to be eligible for the 2025 income tax year, you must make them by:

    • March 2, 2026

    Contributions made after this date will generally count toward your 2026 tax return.

    GST/HST Credit Payment Dates

    GST/HST credit payments will be issued on:

    • January 5

    • April 2

    • July 3

    • October 5

    Canada Child Benefit (CCB) Payment Dates

    Canada Child Benefit payments will be issued on:

    • January 20

    • February 20

    • March 20

    • April 20

    • May 20

    • June 19

    • July 20

    • August 20

    • September 18

    • October 20

    • November 20

    • December 11

    Canada Pension Plan (CPP) and Old Age Security (OAS)

    The government will issue Canada Pension Plan (CPP) and Old Age Security (OAS) payments on the following dates:

    • January 28

    • February 25

    • March 27

    • April 28

    • May 27

    • June 26

    • July 29

    • August 27

    • September 25

    • October 28

    • November 26

    • December 22

    Bank of Canada Interest Rate Announcements

    The Bank of Canada will make interest rate announcements on:

    • January 28

    • March 18

    • April 29

    • June 10

    • July 15

    • September 2

    • October 28

    • December 9

    Personal Income Tax Deadlines

    For most individuals, April 30, 2026 is the last day to:

    • File your 2025 personal income tax return, and

    • Pay any balance owing on your 2025 taxes.

    This is also generally the filing deadline for final returns if death occurred between January 1 and October 31, 2025.

    If death occurred between November 1 and December 31, 2025, the filing deadline for the final return is six months after the date of death (which will fall between May 1 and June 30, 2026).

    Self-Employment Tax Deadlines

    If you or your spouse/common-law partner are self-employed:

    • The filing deadline for your 2025 tax return is June 15, 2026.

    • Any tax payments owing are still due by April 30, 2026.

    Filing later than these dates may result in interest and penalties.

    Year-End Contribution Deadlines

    The final contribution deadline for the 2026 calendar year for the following accounts is December 31, 2026:

    • Tax-Free Savings Account (TFSA)

    • First Home Savings Account (FHSA)

    • Registered Education Savings Plan (RESP)

    • Registered Disability Savings Plan (RDSP)

    December 31, 2026 is also the deadline for:

    • Making 2026 charitable donations that you want to claim on your 2026 tax return.

    Individuals who turn 71 in 2026 to:

    • Make their last contributions to their own RRSPs, and

    • Convert their RRSPs to RRIFs (or an annuity).

    Please reach out if you have any questions or would like help planning around any of these dates.

    Sources:

    Canada Revenue Agency. Tax-Free Savings Account (TFSA), Guide for Individuals. RC4466 (E), Canada.ca, https://www.canada.ca/en/revenue-agency/services/forms-publications/publications/rc4466/tax-free-savings-account-tfsa-guide-individuals.html.

    Canada Revenue Agency. “Registered Retirement Savings Plan (RRSP).” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/registered-retirement-savings-plan-rrsp.html.

    Canada Revenue Agency. “Registered Education Savings Plans (RESPs).” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-education-savings-plans-resps.html.

    Canada Revenue Agency. “First Home Savings Account (FHSA).” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/first-home-savings-account.html.

    Canada Revenue Agency. “GST/HST Credit – Payment Dates.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/child-family-benefits/gst-hst-credit/payment-dates.html#toc1.

    Canada Revenue Agency. “Benefit Payment Dates.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/child-family-benefits/benefit-payment-dates.html.

    Canada. “Benefit Payment Dates Calendar.” Canada.ca, https://www.canada.ca/en/services/benefits/calendar.html.

    Bank of Canada. “Bank of Canada Publishes 2026 Schedule for Policy Interest Rate Announcements and Other Major Publications.” Bank of Canada, https://www.bankofcanada.ca/2025/08/bank-canada-publishes-2026-schedule-policy-interest-rate-announcements-other-major-publications/.

    Canada Revenue Agency. “Important Dates – Individuals.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/important-dates-individuals.html.

    Canada Revenue Agency. “Important Dates for RRSPs, RRIFs, and RDSPs.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/important-dates-rrsp-rrif-rdsp.html.

    https://crossroadsfinancial.ca/wp-content/uploads/2026/01/2026-Financial-Calendar-FI.png 700 1200 Crossroads Financial Inc. https://crossroadsfinancial.ca/wp-content/uploads/2020/04/websiteLogo-300x92.png Crossroads Financial Inc.2026-01-02 11:02:002026-01-02 11:02:522026 Financial Calendar

    Book a Meeting

    Search Blog Posts

    Search Search

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    Categories

    • 2020
    • 2020 Only
    • 2021
    • 2022
    • 2022 Only
    • 2023
    • 2024
    • 2025
    • 2026
    • Accountants
    • Blog
    • Budget
    • Business Owners
    • business owners
    • buy sell
    • Center of Influences
    • Charitable Gifting
    • Coronavirus
    • Coronavirus – Associates
    • Coronavirus – Practice Owners
    • Coronavirus – Practice Owners
    • Coronavirus – Retired
    • Coronavirus – Retiring
    • Coronavirus – Students
    • corporate
    • critical illness insurance
    • Debt
    • dental benefits
    • disability
    • disability insurance
    • Estate Planning
    • Family
    • farmers
    • financial advice
    • Financial Planning
    • Government Budget
    • Group Benefits
    • health benefits
    • incorporated professionals
    • individuals
    • Insurance
    • Investment
    • life insurance
    • long term care
    • mortgage
    • Ontario Only
    • pension plan
    • personal finances
    • Professional Corporations
    • Professionals
    • rdsp
    • Registered Education Savings Plan
    • Retirees
    • retirement
    • rrsp
    • tax
    • Tax Free Savings Account
    • travel insurance

    Get in Touch

    Crossroads Financial Solutions Inc.
    Tel: (905) 361- 6500
    Email: connect@crossroadsfinancial.ca
    TF: 1-877-607-6237

    4255 Sherwoodtowne Blvd, Suite 102
    Mississauga, Ontario
    L4Z 1Y5

    Latest News

    • Why Life Insurance Should Be Part Of Your Estate PlanningSeptember 1, 2026 - 1:30 pm
    • Financial Checklist for New Parents in CanadaAugust 6, 2026 - 12:00 pm
    • Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?July 15, 2026 - 10:35 am

    About

    Everyone has their own dreams. Protecting those goals is our mission. We believe there is no “One Size Fits All” when it come to planning your insurance needs and investment goals.
    We encourage you to have a discovery meeting with us.

    ©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
      Scroll to top Scroll to top Scroll to top